Stock valuation is the process of calculating the intrinsic economic value of a company share and comparing it against its current market price. It relies on absolute models like Discounted Cash Flow (DCF) or relative market multiples like Price-to-Earnings (P/E) to determine if a stock trades at a discount or premium.
This process compares a company share's calculated intrinsic value against its current market trading price.
Stock prices swing daily based on investor emotion, news headlines, and quarterly earnings reports. Learning how analysts calculate business value helps long-term investors evaluate whether a stock trades at a discount or a premium.
This guide explains core valuation frameworks, key financial ratios, model limitations, and when broad-market index investors can bypass single-stock calculations entirely.
Quick Takeaways
01Stock valuation estimates the intrinsic economic worth of a business to determine if shares trade above or below fair value.
02Absolute valuation models calculate intrinsic value from projected future cash flows, while relative valuation compares market multiples across peer companies.
03Multiples like price-to-earnings (P/E) and enterprise value to EBITDA offer fast comparisons, but they depend heavily on accounting definitions.
04Small adjustments to growth forecasts or discount rates cause drastic shifts in calculated intrinsic value.
05Passive index fund investors holding broad market ETFs do not need to perform or track individual stock valuation metrics.
Absolute vs. Relative: Core Stock Valuation Methods
In financial analysis, analysts group stock valuation methods into two main categories: absolute valuation and relative valuation.
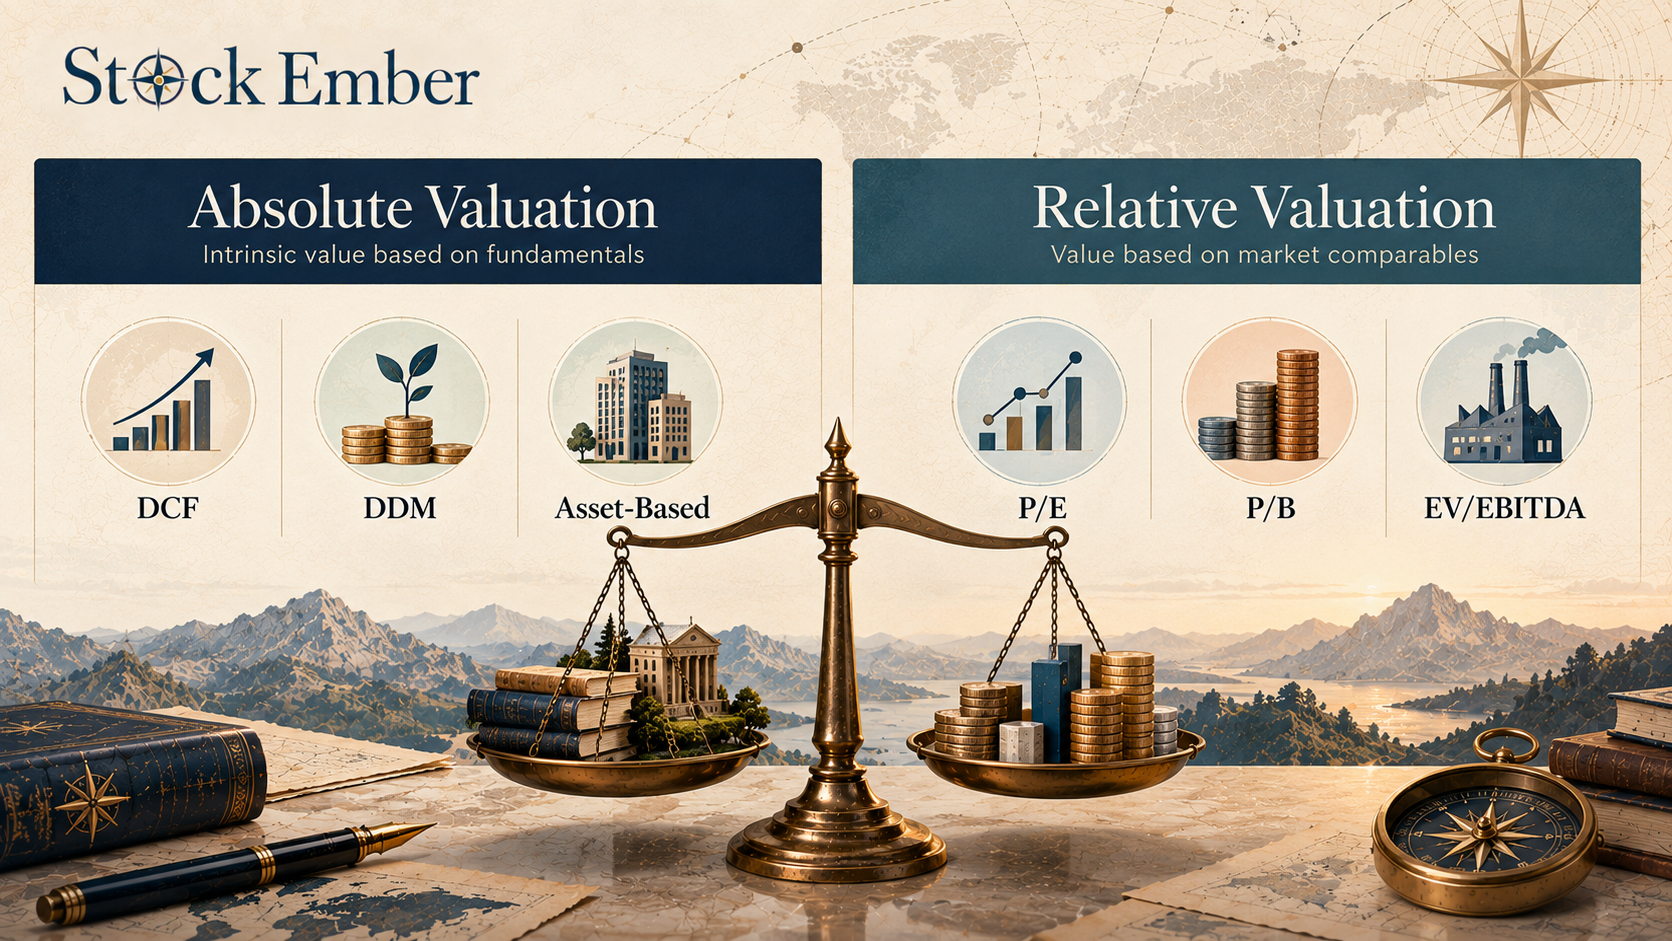
Absolute valuation models attempt to measure a company's intrinsic worth based entirely on its fundamental financial characteristics, such as expected cash flows, dividend payouts, and long-term profit growth. The most common absolute framework is the Discounted Cash Flow (DCF) model.
A DCF model projects a company's future free cash flows over five to ten years. It then discounts those future cash payments back to present-day dollars using a required rate of return known as the weighted average cost of capital (WACC).
If the total present value of all future cash flows exceeds the current market price, the stock is considered undervalued under the model's assumptions. Another absolute method is the Dividend Discount Model (DDM), which values a share based on the present value of its predicted future dividend stream.
Relative valuation models take a different approach by comparing a company's financial metrics against similar businesses in the same industry. Rather than calculating absolute intrinsic cash flows, relative valuation uses trading multiples to judge whether a stock is priced higher or lower than its peer group. While absolute models attempt to find true standalone worth, relative models reveal how the market currently prices one business relative to another.
Common Valuation Multiples and How They Work
Relative valuation relies on standardized financial ratios that allow direct comparisons across companies of different sizes.
The most widely cited relative metric is the Price-to-Earnings (P/E) ratio, calculated by dividing a stock's current price by its net income per share. A low P/E ratio suggests an investor pays less for each dollar of annual profit, while a high P/E ratio indicates that buyers expect rapid future earnings expansion. Another common metric is the Price-to-Book (P/B) ratio, which compares stock price to the accounting net asset value recorded on the balance sheet.
However, equity-only multiples like the P/E ratio can mislead analysts when comparing firms with vastly different debt loads. To account for capital structure, analysts evaluate enterprise value, which measures total business value by adding market capitalization and total debt while subtracting cash holdings.
Dividing enterprise value by earnings before interest, taxes, depreciation, and amortization (EBITDA) creates the EV/EBITDA multiple. According to research published by NYU Stern School of Business, enterprise value multiples provide a clearer comparison for acquirers and institutional investors. This is because they evaluate total operating assets independent of how a firm finances its debt.
Valuation Multiple
Formula
Primary Analytical Use
Price-to-Earnings (P/E)
Share Price / Earnings per Share
Equity valuation relative to net income
Price-to-Book (P/B)
Share Price / Book Value per Share
Asset-heavy companies and financial institutions
EV/EBITDA
Enterprise Value / EBITDA
Capital-structure neutral operational comparison
Diagram comparing absolute cash flow models and relative market multiples for stock valuation.
Why Stock Valuation Models Fall Short (And How Models Fail)
Financial valuation models offer structured analytical frameworks, but investors must remember that no model can predict future share prices or guarantee investment success.
Every absolute valuation calculation depends on forward-looking assumptions. In a DCF model, an analyst must forecast revenues, operating margins, capital expenditures, and terminal growth rates ten years into the future. Furthermore, selecting the discount rate heavily alters the final output.
Lowering the discount rate by just 1 percentage point can increase a stock's estimated fair value by 20% or more. Because human inputs shape the math, two analysts evaluating the exact same balance sheet can arrive at drastically different fair value estimates.
Relative valuation multiples carry similar drawbacks. A stock trading at a low P/E ratio of 8 may look cheap next to an industry average of 18, but that low multiple often reflects severe underlying business risks, declining product demand, or structural debt problems. Buying a stock simply because it trades at a low multiple creates a classic "value trap," where an apparently cheap share continues to lose value as earnings shrink.
In practice, many long-term investors find that treating this process as a ballpark estimate rather than an exact science prevents costly overconfidence. Relying on rigid spreadsheet models often creates a false sense of security, whereas acknowledging model uncertainty encourages wider safety margins.
Why Stock Valuation Matters for Long-Term Investors (And When Indexers Can Ignore It)
Understanding valuation principles helps individual investors avoid market euphoria during speculative bubbles, when stock prices detach from fundamental earning power.
For active stock pickers, reviewing valuation models encourages disciplined buying. Comparing market price against calculated fair value prevents investors from chasing overextended growth stocks that require unrealistic long-term profit expansion to justify their current prices.
However, perspective matters. For individuals building wealth through broad-market exchange-traded funds (ETFs) or low-cost index funds, calculating single-stock valuation metrics is completely unnecessary. Index funds automatically hold hundreds or thousands of public companies across diverse market sectors. Broad diversification bypasses the need to value individual businesses because the fund captures overall corporate economic growth over long holding periods.
Key Considerations and Common Misconceptions
Before applying valuation frameworks to individual securities, long-term investors should keep several practical principles in mind.
Market Price Is Not Fair Value: Current stock market prices represent immediate supply and demand among active buyers and sellers. An estimated intrinsic value represents a theoretical baseline, and market prices can remain far above or below calculated fair value for years.
Valuation Does Not Time Markets: An undervalued stock can continue to fall, while an overvalued stock can continue to rise. Using valuation models to time short-term market entries or exits often leads to missed gains or premature selling.
Cash Flow Quality Matters: High earnings reported on an income statement do not always equal liquid cash flow. Analyzing free cash flow alongside reported profits ensures that valuation multiples reflect genuine cash generation rather than short-term accounting adjustments.
Before spending time evaluating individual business balance sheets, mastering the basic principles of investing in stocks ensures that valuation analysis is applied within a diversified, long-term asset allocation plan.
Conclusion
Stock valuation estimates a company's economic worth by analyzing projected cash flows or comparing market multiples across industry peers. While absolute models like Discounted Cash Flow calculate standalone intrinsic value and relative metrics like P/E ratios compare peer pricing, all valuation outputs rely heavily on forward-looking assumptions. Valuation analysis provides helpful context for active stock investors, but it does not eliminate market risk or shield individual equities from price drawdowns.
When you are ready to explore trading platforms and investment accounts for managing your portfolio, our broker reviews offer detailed comparisons of account features and execution fees. Equity investments always carry the risk of capital loss, so treat stock valuation as one analytical tool within a well-balanced, long-term investment strategy.
FAQ
5 questions
What is stock valuation?
Stock valuation is the quantitative process of determining the intrinsic financial worth of a company's stock to evaluate whether current market trading prices represent fair value, a discount, or a premium.
What are the main stock valuation methods?
The two primary categories of stock valuation methods are absolute valuation (such as Discounted Cash Flow models that project future cash flows) and relative valuation (which compares financial multiples like P/E or EV/EBITDA across industry peers).
What is the difference between absolute and relative valuation?
Absolute valuation evaluates a company's standalone intrinsic worth based on fundamental cash flows and dividends, whereas relative valuation assesses business value by comparing market multiples against similar competitor companies.
Is stock valuation an exact science?
No. Stock valuation relies on forward-looking assumptions regarding revenue growth, profit margins, and discount rates. Small changes in model assumptions can produce significantly different intrinsic value estimates.
Do passive index fund investors need to perform stock valuation?
No. Investors holding broad-market index funds or ETFs do not need to perform single-stock valuations, as diversified index funds automatically capture aggregate market growth across hundreds of public corporations.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.