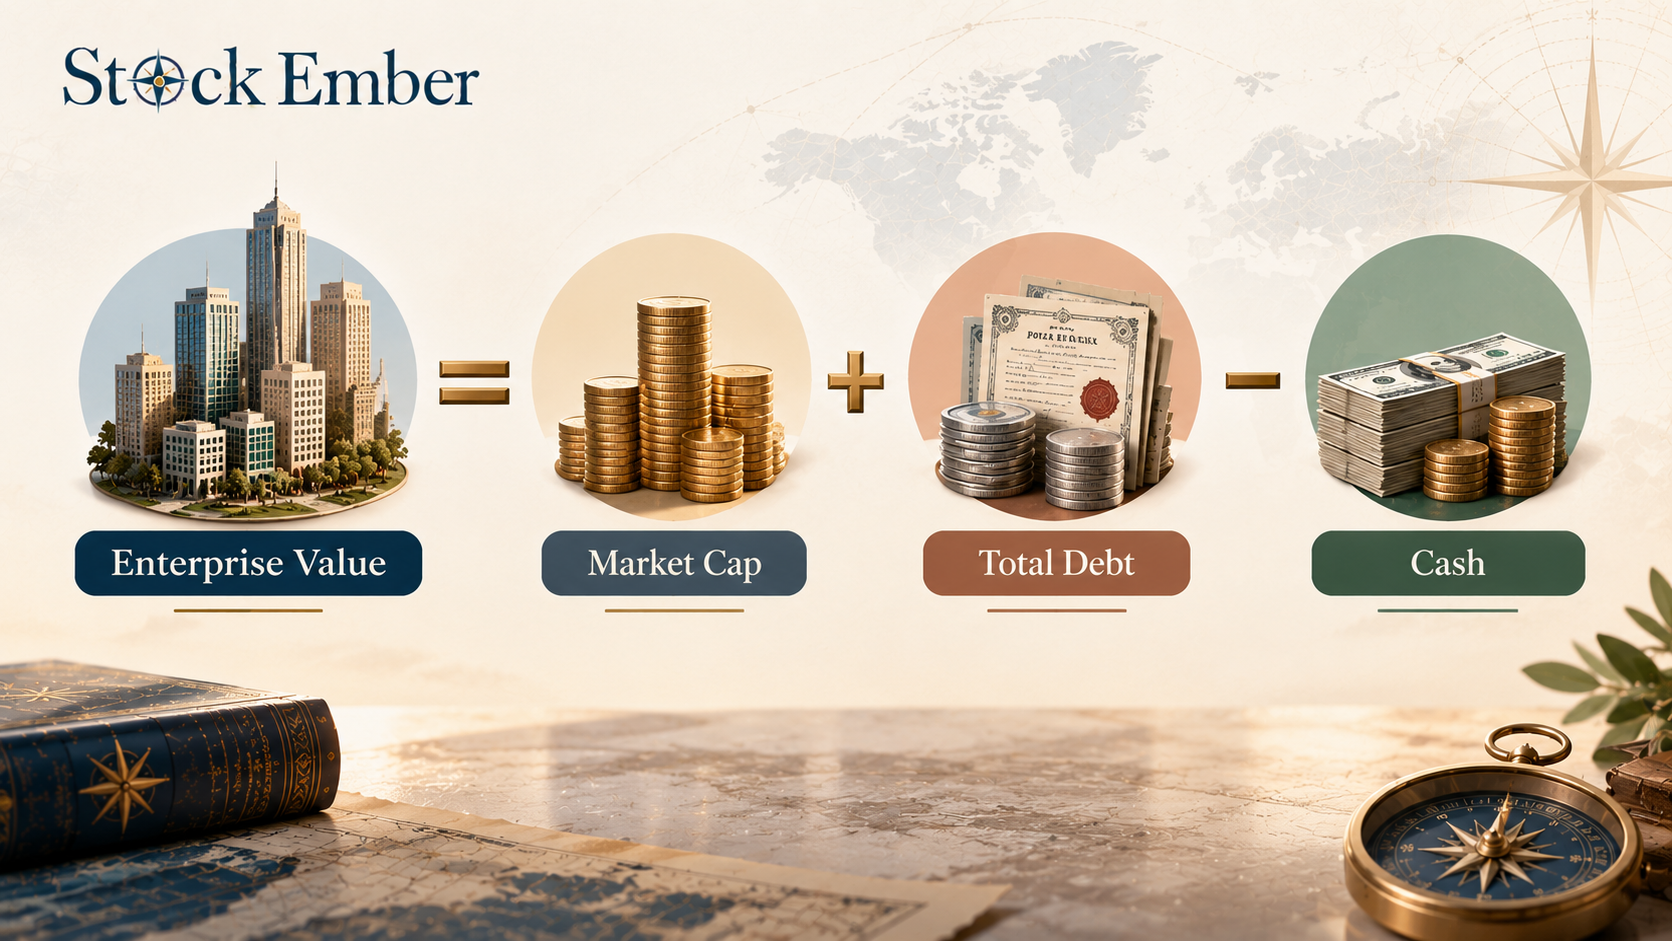
Enterprise value (EV) measures a company's total valuation by taking its market capitalization, adding total debt, and subtracting cash and cash equivalents. It represents the net theoretical price an acquirer would pay to purchase the entire operational business.
This metric measures a company's total valuation by combining its market capitalization with its net debt. It represents the theoretical price an acquirer would pay to purchase the entire business.
When evaluating stock prices, many beginners look only at market capitalization. However, market capitalization only reflects the total cost of purchasing all outstanding common shares. If a business carries heavy bank debt or sits on a large mountain of cash, market capitalization fails to show the true cost of taking over the operations.
This guide explains what EV is, how the formula works, and how to use it when comparing companies.
Quick Takeaways
01EV reflects the total price tag of a business, including both equity and net debt.
02Adding debt accounts for obligations an acquirer must take on, while subtracting cash accounts for assets that reduce the purchase price.
03EV provides a cleaner comparison than market capitalization when analyzing companies with different capital structures.
04Passive index fund investors do not need to calculate EV for individual stocks.
What Is Enterprise Value? (Core Definition)
This metric represents the complete purchase price of a company's operational assets. Think of it as the price you would pay if you decided to buy every single share of stock, pay off all existing company debt, and keep any cash sitting in the corporate bank accounts.
Market capitalization tells you what the stock market thinks the equity portion of a company is worth. However, equity is only one piece of a corporate capital structure. Most businesses also rely on loans, corporate bonds, and preferred stock to fund their operations.
When an acquirer buys a company, they inherit both its assets and its liabilities. If the target company has $50 million in debt, the new owner becomes responsible for paying off that $50 million. Conversely, if the company has $20 million in cash, the new owner can immediately use that cash to offset the purchase price. Therefore, EV adjusts equity value to show the net cost of acquiring the core business.
Visual chart showing the calculation steps for enterprise value.
The Enterprise Value Formula: How to Calculate EV
To understand how to calculate EV, you need to look at three main numbers on a company's financial statements: market capitalization, total debt, and cash reserves.
The fundamental EV formula is written as:
Enterprise Value = Market Capitalization + Total Debt − Cash and Cash Equivalents
Applying this equation involves three simple calculation steps:
Start with Market Capitalization: Multiply the current stock price by the total number of shares outstanding.
Add Total Debt: Combine short-term debt and long-term debt liabilities from the balance sheet.
Subtract Cash and Cash Equivalents: Subtract all liquid cash, bank deposits, and short-term treasury investments.
For a concrete calculation example, imagine a firm with the following balance sheet items:
In this scenario, the EV is $120 million, which is $20 million higher than its market capitalization.
Enterprise Value vs. Market Cap: Why Debt and Cash Matter
Comparing market capitalization alone can mislead investors when two businesses operate with completely different capital structures.
Consider two competing retail companies, Company A and Company B, both trading at a market capitalization of $500 million:
Company A: Market Cap = $500 million | Debt = $0 | Cash = $100 million
EV = $500M + $0 − $100M = $400 million
Company B: Market Cap = $500 million | Debt = $300 million | Cash = $10 million
EV = $500M + $300M − $10M = $790 million
Looking only at market capitalization makes both businesses appear equally priced at $500 million. However, buying Company A effectively costs $400 million because you gain $100 million in bank cash upon purchase. Buying Company B costs $790 million because you must take responsibility for $300 million in debt obligations.
According to financial reporting standards recognized by the U.S. SEC, evaluating a company's financial condition requires reviewing both reported debt liabilities and cash reserves on the balance sheet.
How Enterprise Value Is Used (EV Multiples and Valuation)
Financial analysts frequently use EV to build valuation ratios that compare businesses fairly across an entire industry.
The most common metric is the EV/EBITDA ratio, which compares EV to Earnings Before Interest, Taxes, Depreciation, and Amortization. Because EBITDA measures cash earnings before capital structure expenses, pairing it with EV provides a neutral comparison that is not distorted by differing corporate debt levels.
Another common metric is EV/Sales, which compares total business value to annual revenue. This ratio is useful for early-stage companies that have not yet turned a profit. When traditional valuation tools fail, such as when a business reports a negative P/E ratio due to temporary net losses, EV/Sales helps investors evaluate total firm value relative to underlying sales volume.
Common EV Pitfalls: What to Watch Out For
While EV is a powerful metric, relying on it in isolation introduces several analytical traps:
Ignoring cash burn rates: Subtracting cash assumes those funds will remain available. If a company loses money rapidly every quarter, that cash reserve can disappear before an investor sees any benefit.
Overlooking off-balance-sheet liabilities: Standard EV equations include reported bank debt, but they may omit operating leases, pension underfunding, or legal liabilities.
Comparing EV across unrelated industries: Capital-heavy industries like utilities naturally carry higher debt than software businesses. Comparing their valuations directly leads to false conclusions.
In practice, many long-term investors find that checking whether a company's EV is driven primarily by cash flow or by growing debt loads helps separate sound businesses from balance sheet traps.
Conclusion
EV provides a realistic picture of corporate valuation by accounting for both market capitalization and net balance sheet debt. By adding debt obligations and subtracting cash reserves, EV reveals the true purchase price required to acquire a business's operational earnings.
However, detailed balance sheet calculations require ongoing monitoring and accounting familiarity. If your strategy focuses on investing in stocks through broad index funds, you do not need to calculate EV for individual companies. Broad market index funds automatically hold hundreds of profitable businesses, letting you participate in overall market growth without analyzing individual capital structures.
Investing involves risk, including the possible loss of principal, and historical balance sheet metrics do not guarantee future corporate performance. Treat valuation figures as educational research tools. When you are ready to evaluate platforms for your long-term portfolio, our broker reviews provide a clear place to start.
FAQ
5 questions
What is enterprise value and how is it calculated?
It measures total firm value across both equity and debt holders. It is calculated by taking market capitalization, adding short-term and long-term debt liabilities, and subtracting liquid cash and cash equivalents.
What is the difference between market cap and enterprise value?
Market capitalization reflects only the value of a company's common stock. Enterprise value includes market cap plus net debt, providing a comprehensive picture of what it costs to acquire the operational assets of the business.
Why do you add debt and subtract cash in enterprise value?
Debt is added because an acquiring buyer must assume or pay off the target company's debt obligations. Cash is subtracted because the acquirer can immediately use those cash reserves to pay down part of the purchase cost.
Can enterprise value be negative?
Yes. If a company holds cash and cash equivalents that exceed its combined market capitalization and total debt liabilities, its net enterprise value will be calculated as a negative number.
What is a good EV/EBITDA ratio?
A "good" EV/EBITDA ratio varies by industry, but historical market averages, as tracked by S&P Capital IQ benchmark data, generally fall between 8 and 14. Lower multiples may indicate a company is undervalued, provided its underlying cash flows remain healthy.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.