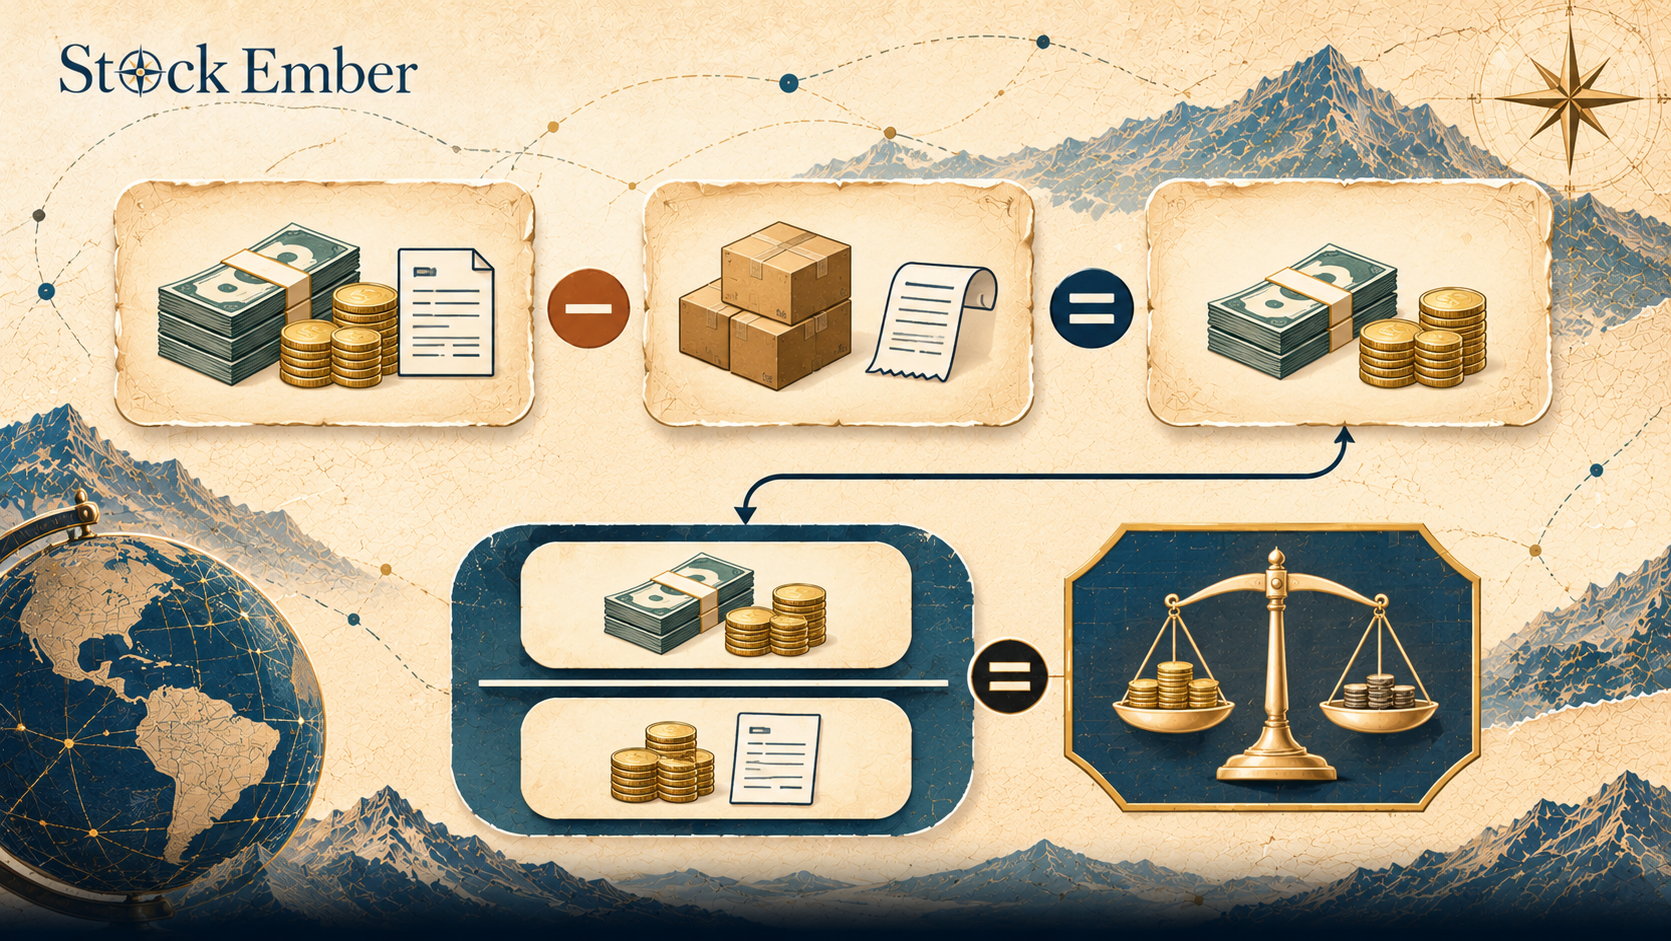
The quick ratio, also known as the acid-test ratio, evaluates whether a business can settle its debts due within one year using strictly cash, marketable securities, and accounts receivable. By excluding slower-moving inventory and prepaid expenses, it measures immediate balance-sheet liquidity and buffer strength during economic downturns. A baseline ratio of 1.0 indicates that liquid resources match short-term obligations dollar for dollar.
The quick ratio measures a company's ability to cover short-term debts using only its most liquid assets. Often called the acid-test ratio, it provides a strict test of short-term financial strength.
When market conditions tighten, businesses cannot pay bills with slow-moving inventory or factory equipment. Investors use the quick ratio to evaluate whether a company can survive an unexpected cash crunch without emergency borrowing. This guide explains how the quick ratio works, how to calculate it, and why holding too much idle cash can quietly hurt long-term investment compounding.
Quick Takeaways
01The quick ratio compares cash, marketable securities, and accounts receivable against debts due within twelve months.
02It excludes inventory and prepaid expenses because those assets cannot convert to cash quickly without steep price cuts.
03A ratio of 1.0 indicates that a business owns one dollar of liquid assets for every dollar of upcoming obligations.
04Low ratios warn of insolvency risk, while excessively high ratios over a decade create cash drag that depresses returns.
05Broad index investors do not need to track individual liquidity ratios, as broad funds absorb balance-sheet risks automatically.
What Is the Quick Ratio?
The quick ratio evaluates whether a business owns enough near-cash resources to settle short-term obligations over the next twelve months. The name comes from the historical acid test, where miners used acid on metal to separate real gold from base minerals. In financial analysis, the metric acts as a filter, removing assets that cannot convert into cash quickly.
To understand the quick ratio meaning, you must examine how assets appear on a corporate balance sheet. As outlined by the U.S. SEC, companies group resources by liquidity, listing the fastest-converting items first. Total current assets include everything a business expects to convert to cash within a year. However, the quick ratio restricts its focus to three "quick assets":
Cash and cash equivalents: Bank deposits, checking balances, and commercial paper.
Marketable securities: Treasury bills and short-term holdings traded on liquid public markets.
Accounts receivable: Invoices billed to customers that are due within thirty to ninety days.
The formula deliberately excludes inventory and prepaid expenses. Raw materials and finished goods take months to sell, and forcing a rapid warehouse sale usually demands steep price markdowns. Prepaid expenses, such as advance commercial insurance, provide future services but cannot be handed over to pay creditors.
How the Quick Ratio Is Calculated
Investors calculate the quick ratio by dividing quick assets by total current liabilities. You can find all required line items on the company balance sheet in quarterly or annual reports.
The direct formula adds each quick asset together:
Quick Ratio = (Cash and Cash Equivalents + Marketable Securities + Accounts Receivable) / Current Liabilities
The subtraction formula starts from total current assets:
Quick Ratio = (Current Assets − Inventory − Prepaid Expenses) / Current Liabilities
Both formulas produce the exact same total, while seeing the quick ratio explained through both paths clarifies how balance-sheet accounts interact. Current liabilities include all corporate bills, vendor invoices, and loan payments due within one year.
Diagram illustrating the quick ratio formula and asset exclusions
Suppose an industrial supplier reports $400,000 in cash, $100,000 in marketable securities, and $500,000 in accounts receivable. Its balance sheet also lists $800,000 in inventory, $50,000 in prepaid expenses, and $1,000,000 in current liabilities:
A ratio of 1.0 means the firm holds exactly one dollar of liquid assets for every dollar of debt maturing within the year.
Quick Ratio vs. Current Ratio
The fundamental difference between the quick ratio and the standard current ratio comes down to inventory. The current ratio divides total current assets by current liabilities without removing slower-moving warehouse items.
In the example above, the supplier's current ratio is 1.85 ($1,850,000 divided by $1,000,000). A surface-level review suggests plenty of liquidity. Yet $800,000 of those assets sit trapped in warehouse bins. If sales drop or products become obsolete, the company cannot easily turn that stock into cash. The quick ratio reveals that its true liquid cushion is only 1.0.
Typical quick ratios vary by industry. Grocery stores operate with daily customer cash turnover, letting them run safely with ratios below 1.0. Industrial manufacturers require higher ratios to manage long production cycles.
While the quick ratio checks immediate balance-sheet liquidity, equity investors also assess whether a firm can comfortably service its ongoing loans. Checking the interest coverage ratio alongside short-term liquidity confirms whether operating profits can support recurring loan obligations over the full business cycle.
The 10-Year Opportunity Cost of Excess Cash
While a low quick ratio signals immediate danger, investors often assume that a higher ratio is always better. Hoarding excessive cash shields against short-term bankruptcy, but over a multi-year horizon, it acts as a drag on portfolio growth.
Cash and short-term paper yield low returns that struggle to outpace consumer inflation. When management holds massive cash reserves simply to maintain a quick ratio of 3.0 or higher, that money is not funding productive business expansion or share repurchases. Over time, idle cash can pull down return on equity (ROE) and depress shareholder value.
Consider an illustrative company holding $5,000,000 in excess cash over a decade:
Held in short-term bank deposits earning an illustrative 2% annual return, that cash grows to ~$6,100,000 over ten years.
Deployed into productive corporate projects earning an illustrative 9% return, that capital would have compounded to ~$11,800,000.
The silent 10-year opportunity cost of that excessive liquidity buffer is ~$5,700,000 in lost economic value."
These return figures are hypothetical illustrations only; actual investment returns are not guaranteed and may be lower or negative in any given year.
For long-term owners, cash that sits permanently idle fails to compound. A resilient business balances sufficient liquidity for downturns with productive capital deployment.
Where the Quick Ratio Fails
The quick ratio provides a helpful snapshot, but relying on it in isolation creates blind spots. A company can appear safe on paper while heading toward serious financial stress.
The first hazard is the accounts receivable trap. The quick ratio treats all customer invoices as good as cash. Yet in a sharp recession, corporate buyers face their own cash crunches. When clients delay payments or go bankrupt, unpaid invoices turn into bad debt write-offs. A business with a quick ratio of 1.2 can see its liquid cushion vanish if 20% of its receivables default.
A second blind spot is that the balance sheet is a freeze-frame taken on a single calendar day. Corporate managers can temporarily delay paying vendor bills or tap short-term credit lines right before the quarter ends, presenting a polished balance sheet. Once the new quarter begins, rapid cash burns can quickly deplete that liquid buffer.
When learning the foundational principles of investing in stocks, analyzing balance-sheet buffers alongside underlying operating cash flows prevents you from mistaking accounting snapshots for permanent safety.
In practice, experienced equity analysts review the collection history of accounts receivable and the stability of operating cash flow before accepting a quick ratio at face value.
Conclusion
The quick ratio serves as a practical stress test of corporate liquidity by measuring whether near-cash assets can cover debt due within a year. By excluding illiquid inventory and prepaid costs, it strips away accounting optimism and shows the cash cushion available to survive an unexpected economic downturn.
However, a healthy quick ratio does not guarantee business profitability or superior management. Holding excessive cash over long horizons creates a persistent drag on capital efficiency, while vulnerable receivables can make a weak company appear stable.
If you invest through diversified index funds or exchange-traded funds, you do not need to calculate or monitor the quick ratio of individual firms. A broad market portfolio owns hundreds of companies across many industries, letting market-wide productivity compound without requiring you to evaluate individual balance sheets. When you are ready to choose an investing platform for a diversified portfolio, our broker reviews are a practical place to start.
All equity investing involves the risk of losing capital, and past financial stability never guarantees future returns, so use this guide as foundational education rather than tailored financial advice.
FAQ
5 questions
What happens if a company's quick ratio falls below 1.0?
A quick ratio below 1.0 means a business lacks sufficient liquid assets to pay all upcoming annual obligations immediately. While this indicates potential liquidity strain, it does not mean instant failure. Companies with steady daily customer collections or dependable lines of credit often operate smoothly below 1.0 by meeting debts through recurring operating cash flows rather than balance-sheet reserves.
Why are prepaid expenses excluded from the quick ratio?
Prepaid expenses represent future operational services that have already been paid for, such as commercial insurance or annual software subscriptions. While these items provide real business value over the coming months, they cannot be returned to vendors or transferred to creditors to settle maturing debts during a sudden liquidity crunch.
How does the quick ratio differ from the cash ratio?
The quick ratio includes accounts receivable alongside cash and marketable securities because customer invoices are expected to settle within months. The cash ratio is an even stricter liquidity measure that eliminates accounts receivable entirely, comparing only physical cash and short-term securities against current debts to assess absolute worst-case liquidation strength.
Can an excessively high quick ratio hurt shareholder returns?
Yes. While a very high ratio indicates strong balance-sheet protection, holding excessive cash reserves over long periods creates cash drag. Idle cash earns modest yields that frequently fail to outpace inflation, pulling down overall return on equity compared to businesses that reinvest capital into productive business expansion or share repurchases.
Why do capital-intensive businesses require higher quick ratios than retailers?
Capital-intensive businesses experience long production cycles, seasonal deliveries, and extended credit terms from corporate clients, requiring larger cash buffers to bridge payment gaps. In contrast, retail stores and supermarkets collect immediate cash or debit payments directly from retail consumers daily, allowing them to service supplier bills with minimal liquid cash reserves.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.