The Capital Asset Pricing Model (CAPM) estimates the required rate of return for an asset by comparing its sensitivity to market risk against safe government debt. It provides investors with a baseline hurdle rate to determine whether a volatile stock offers enough potential reward for its systematic risk.
The Capital Asset Pricing Model (CAPM) is a formula that calculates an asset's expected return based on its market risk. It helps investors determine the return required to justify holding a volatile stock rather than safer government debt.
When evaluating an individual stock, you take on volatility that broad index funds avoid. How much extra return should you demand for taking on those price swings? Understanding how CAPM balances market swings against expected reward helps you judge whether an investment justifies its price tag.
This guide explains how CAPM works, where its calculations break down, and what it means for your portfolio.
Quick Takeaways
01CAPM calculates a theoretical hurdle rate, showing the return you should demand for taking on market volatility.
02CAPM only rewards systematic risk, market-wide swings that diversification cannot remove.
03Beta measures historical price sensitivity relative to an index, not fundamental business failure.
04Everyday investment costs reduce net compounding well below theoretical formula outputs.
What Is CAPM and What Does It Measure?
CAPM measures the relationship between market risk and the return an investor should demand for holding an asset. If you are researching what CAPM is or exploring the broader CAPM meaning, it functions primarily as a pricing benchmark. Financial analysts use it to set a hurdle rate, the minimum acceptable percentage gain needed to justify an investment.
Economists William Sharpe, John Lintner, and Jan Mossin developed CAPM in the 1960s, building on Modern Portfolio Theory. The core idea is simple: investors dislike volatility, so they require a higher expected payoff to hold an asset that swings with the broader market.
CAPM does not predict tomorrow's stock price or guarantee an outcome. Instead, it offers a theoretical baseline for evaluating risk-adjusted returns under balanced market conditions.
How the Formula Works: Breaking Down the Components
The CAPM formula establishes an asset's required return by adding a risk premium to the baseline yield of government debt.
To understand the calculation, break it down into 4 components:
Risk-Free Rate: The return on an asset with near-zero default risk, typically short-term government debt like US Treasury bills. While sovereign default risk is minimal, no investment is risk-free in real purchasing-power terms once inflation is counted.
Beta: A metric measuring how much a stock's price moves compared to the overall market. A beta of 1.0 means the stock moves with the market. A beta of 1.2 means the stock has historically moved about 20% more than the market, while 0.8 means it has moved about 20% less.
Expected Market Return: The estimated long-term annual return of the equity market, often based on broad index historical averages.
Market Risk Premium: The difference between expected market return and the risk-free rate, reflecting the extra return demanded for holding equities instead of cash equivalents.
For example, assume a risk-free rate of 4%, an expected market return of 9%, and a stock beta of 1.2. The market risk premium is 5% (9% − 4%). Multiplying by beta gives 6% (1.2 × 5%). Adding the 4% baseline results in a 10% required annual return.
The table below applies the same assumptions to 3 different beta levels.
Beta
Calculation
Required return
0.8
4% + 0.8 × 5%
8%
1.0
4% + 1.0 × 5%
9%
1.2
4% + 1.2 × 5%
10%
Systematic vs. Unsystematic Risk: Why Diversification Matters
Put simply, here is CAPM explained: markets only compensate you for risks you cannot eliminate yourself.
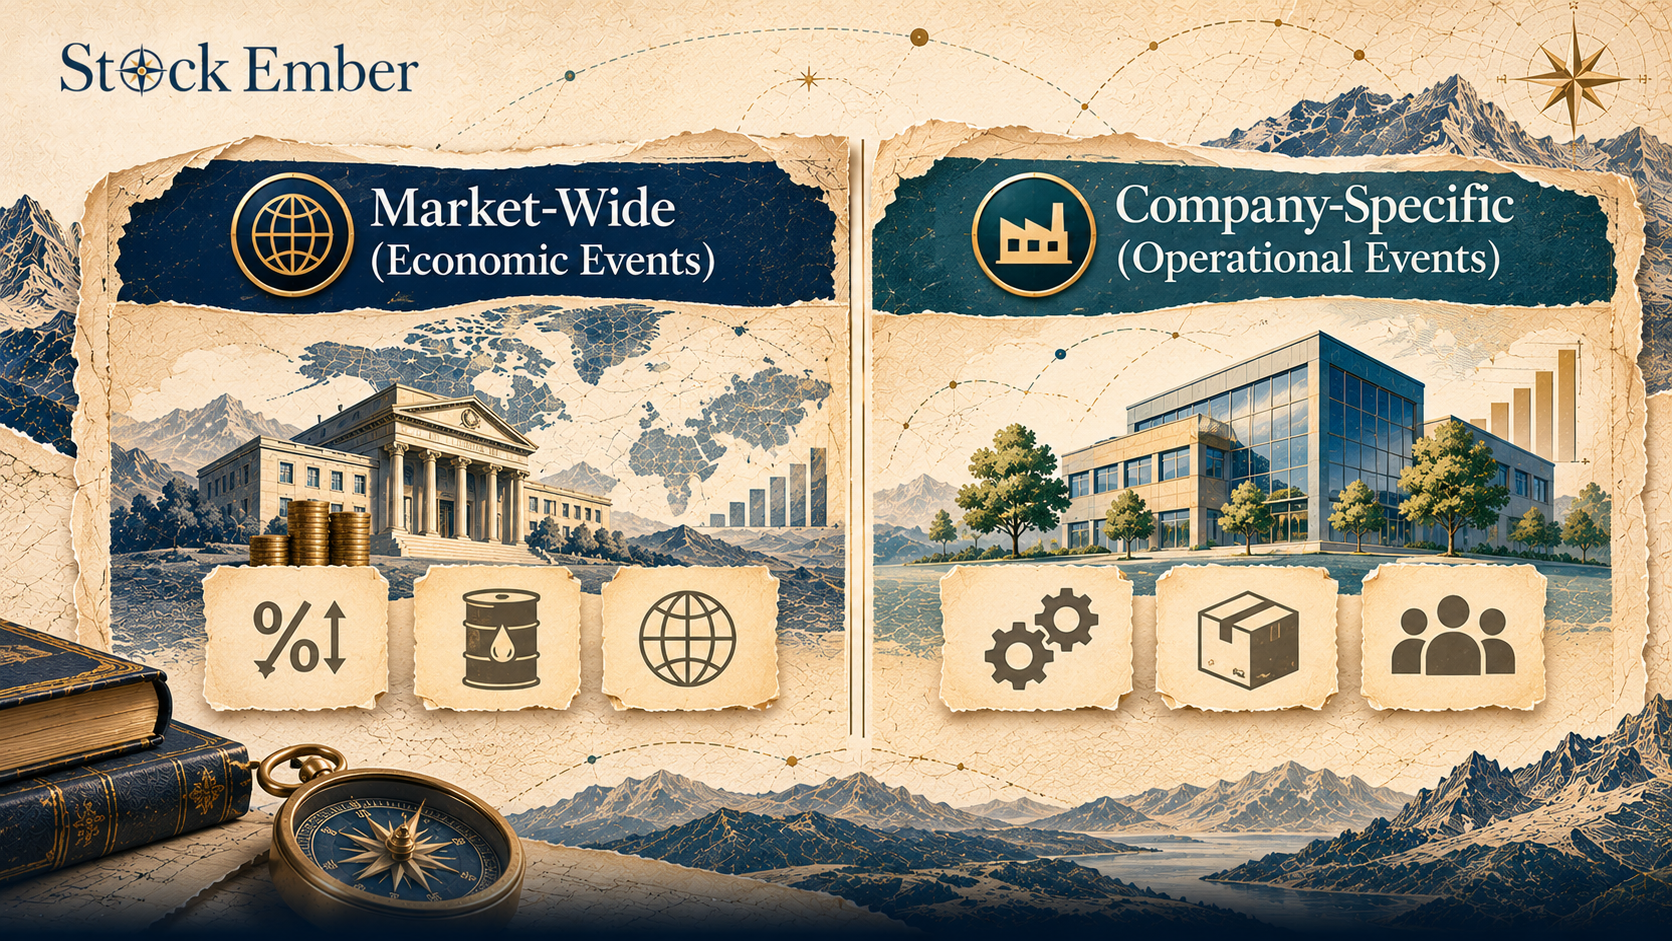
Chart contrasting market-wide systematic risk with company-specific unsystematic risk
Investment risk divides into 2 distinct categories:
Systematic Risk (Market Risk): Macroeconomic forces that affect the entire financial system, such as recessions, interest rate shifts, and geopolitical shocks. Because these forces sweep across all industries, diversification cannot remove them. Beta measures this systematic exposure.
Unsystematic Risk (Company-Specific Risk): Dangers unique to an individual business. These include management turnover, product recalls, or cash shortages caused by mismanaged working capital.
Diversification largely eliminates unsystematic risk. When building a plan for investing in stocks, spreading money across hundreds of companies can help offset bad news at one firm with stronger results at others.
As detailed by the CFA Institute, capital market theory assumes investors only receive expected compensation for holding systematic, non-diversifiable risk. Because you can eliminate company-specific risk simply by owning a broad index fund, the market will not pay you a premium for taking on individual business failures.
Theoretical Return vs. 10-Year Portfolio Reality
While financial models produce tidy figures on paper, real-world portfolio growth is dragged down by fees, transaction costs, and cash drag over time.
Consider the compounding effect over a standard 10-year holding period on an initial $100,000 investment:
At a theoretical 9% annual growth rate, that $100,000 grows to ~$236,736 after 10 years.
With real-world friction, such as an ongoing 0.75% fund fee plus 0.25% in trading costs and cash drag (a total drag of 1% annually), the net return drops to 8%.
At 8%, that same $100,000 grows to ~$215,892.
These figures are hypothetical and shown for illustration only. Actual returns will vary, and no investment outcome is guaranteed.
That 1% annual drag takes nearly $21,000 out of your portfolio over a decade. A theoretical pricing model ignores these everyday frictions, but your actual net wealth cannot.
In practice, many long-term investors find that obsessing over exact decimal points in financial formulas creates a false sense of security; focusing on asset allocation and keeping fees low is likely to matter more to long-term wealth accumulation than fine-tuning expected return equations.
Common Mistakes and Real-World Flaws
A common and costly mistake with CAPM is treating a theoretical formula as a crystal ball.
In practice, 3 primary flaws frequently distort CAPM's output:
Beta is backward-looking: Beta relies on historical price movements, usually over 3–5 years. A company's business model and debt burden change over time, meaning past price sensitivity does not reliably predict future market reactions.
Volatility is not fundamental risk: CAPM assumes that price volatility equals risk. However, a stable business with steady cash flow may experience temporary price swings during a panic. Conflating price fluctuations with permanent capital loss misleads patient long-term owners.
Single-factor oversimplification: CAPM assumes market sensitivity is the sole factor driving returns. Modern research demonstrates that company size, valuation ratios, and corporate profitability also explain long-term performance differences.
Conclusion
CAPM remains a useful framework for understanding the link between market volatility and required return. It clarifies why you should never expect higher returns without accepting greater market exposure, and why diversification is essential for washing out company-specific hazards. For most long-term investors, holding a broad index fund eliminates the need to calculate individual betas altogether.
When you are ready to evaluate platforms for building a diversified portfolio, our Broker reviews provide an objective place to compare costs and features.
Investing in financial markets carries risk of capital loss and past market volatility does not predict future performance, so treat theoretical pricing models as educational concepts rather than personalized advice.
FAQ
5 questions
Can an asset have a negative beta in the CAPM formula?
Yes, an asset has a negative beta if its price moves in the opposite direction of the broader stock market. Gold, certain specialized inverse funds, or cash equivalents during severe downturns sometimes exhibit negative or near-zero betas. In CAPM, an asset with negative beta would theoretically yield an expected return below the risk-free rate because it provides insurance against market crashes.
Do passive index fund investors need to calculate CAPM?
No, long-term index investors do not need to calculate CAPM for individual assets. Because a broad index fund owns the entire market, its beta is naturally 1.0, and it already eliminates company-specific unsystematic risk through deep diversification. Passive investors focus on low-cost asset allocation and patience rather than calculating required returns for single securities.
What asset is typically used as the risk-free rate?
Analysts and investors typically use the current yield on sovereign government debt, such as 3-month US Treasury bills or, for long-term valuations, 10-year US Treasury notes. These instruments carry negligible default risk because they are backed by the government. However, even Treasury securities carry inflation risk over time, meaning they are not truly free of purchasing-power loss.
Why does CAPM assume frictionless markets with no taxes or fees?
CAPM makes simplifying assumptions such as zero taxes, no trading commissions, and equal access to information to isolate the pure mathematical relationship between market risk and return. In the real world, transaction costs, management fees, and tax drag directly reduce compounding returns, which is why actual portfolio results always differ from theoretical formulas.
What is the difference between CAPM and Modern Portfolio Theory?
Modern Portfolio Theory (MPT), introduced by Harry Markowitz, demonstrates how combining assets with low correlations reduces overall portfolio variance. CAPM builds on top of MPT by establishing an exact pricing equation for how individual assets should be valued based on their sensitivity to the overall market portfolio.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.