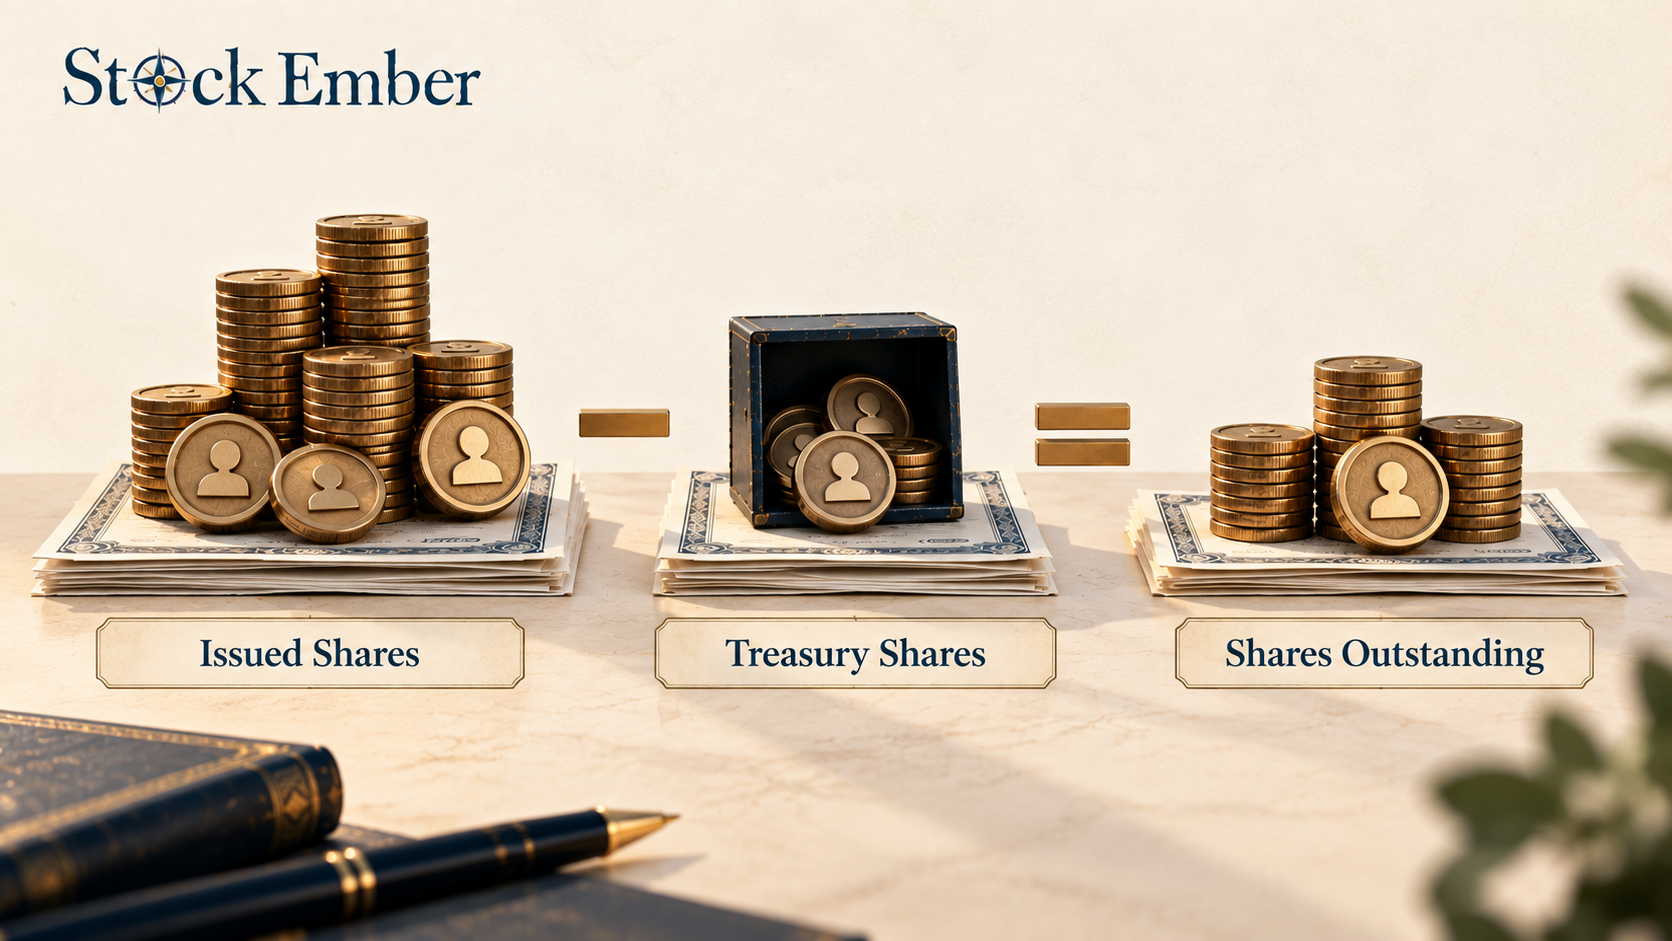
Shares outstanding is calculated by taking total common stock issued by a corporation and subtracting shares held as treasury stock. On a balance sheet under Stockholders' Equity, subtract repurchased shares from total issued shares to determine the net outstanding count.
Shares outstanding represents the total number of common stock shares currently held by all investors, including institutional shareholders, retail investors, and corporate insiders. It is calculated by taking total issued shares and subtracting treasury stock repurchased by the company.
When evaluating a public company, knowing its total earnings or stock price is not enough. A business trading at $10 per share with 1 billion shares is worth $10 billion in total, while a company trading at $100 per share with 5 million shares is worth only $500 million. Learning how share count works helps you determine true business value, calculate profit per share, and track ownership dilution over time.
This guide covers the core formula, balance sheet line items, and basic versus diluted calculations.
Quick Takeaways
01Shares outstanding equals total issued shares minus repurchased treasury stock.
02You can find physical share counts in the Stockholders' Equity section of SEC Form 10-K filings.
03Diluted share counts include potential future shares from options, warrants, and convertible debt.
04Index fund investors do not need to manually compute individual balance sheet share counts.
What Are Shares Outstanding? (Core Definition)
Shares outstanding refers to the net pool of equity shares that a corporation has issued and that remain in the hands of external investors and insiders. These shares grant voting rights, entitlement to potential corporate dividends, and a direct claim on future business profits.
To understand how to calculate outstanding shares, it helps to distinguish outstanding stock from four related accounting terms:
Authorized shares: The maximum number of shares a company is legally permitted to issue under its corporate charter.
Issued shares: The total number of shares the company has created and distributed since its inception.
Treasury shares: Previously issued shares that the corporation has repurchased from the open market and held in its own treasury.
Floating shares (Float): The subset of outstanding shares available for public trading, excluding restricted shares held by officers or major insiders.
The relationship between these categories forms the backbone of corporate equity accounting. Authorized shares set the ceiling, while issued shares minus treasury shares determine the active ownership base.
How the Share Categories Fit Together: A Worked Example
Share Category
Example Count
How It Is Derived
Authorized shares
100,000,000
Legal ceiling set by the corporate charter
Issued shares
50,000,000
Shares the company has actually issued
Treasury shares
10,000,000
Issued shares the company has bought back
Shares outstanding
40,000,000
Issued shares − treasury shares
Restricted insider shares
5,000,000
Outstanding shares that cannot be freely traded
Float
35,000,000
Shares outstanding − restricted shares
These figures are hypothetical and are used only to show how each category relates to the others.
How to Calculate Shares Outstanding From a Balance Sheet
If you want to know how to calculate shares outstanding from balance sheet statements, open the annual report (SEC Form 10-K) or quarterly filing (SEC Form 10-Q) of any public company. Look directly for the balance sheet section labeled "Stockholders' Equity" or "Shareholders' Equity."
The basic mathematical formula is straightforward:
Shares Outstanding = Total Issued Shares − Treasury Shares
To apply this formula accurately, follow these step-by-step instructions:
Locate common stock line items: Read the descriptions under Stockholders' Equity. Companies list the exact number of issued shares right beside the common stock entry.
Identify treasury stock: Look for a line item named "Treasury Stock" or "Shares Repurchased." Note the number of shares held in treasury.
Subtract repurchased shares from issued shares: Subtract the treasury share count from the issued share count to find the net outstanding total.
For example, suppose a balance sheet shows 50 million issued shares of common stock and 10 million shares held as treasury stock.
When learning how to calculate the number of shares outstanding, a frequent point of confusion is mixing up dollar values with physical share counts. Balance sheets often display common stock value as par value (such as $0.01 per share multiplied by total shares) rather than market price. Always read the text description next to the number, which explicitly states the physical share count.
This step-by-step method also answers how to calculate common shares outstanding when reviewing older annual filings. If a company does not hold any treasury stock, total issued shares and outstanding shares are identical. Therefore, understanding how to calculate outstanding shares of common stock simply requires checking whether a repurchased treasury pool exists.
Chart displaying the formula to calculate shares outstanding from a balance sheet.
Basic vs. Diluted Shares Outstanding: What’s the Difference?
When analyzing corporate performance, looking only at basic shares outstanding can give an incomplete picture. Financial statement analysis separates share count into basic and diluted figures.
Basic shares outstanding counts only the stock currently held by shareholders. However, many corporations grant stock options to executives, sell warrants to lenders, or issue convertible bonds that can turn into new stock at a later date.
Diluted shares outstanding calculates how many shares would exist if all of these potential instruments were exercised today:
Stock options & restricted stock units (RSUs): Employee incentive awards that convert into stock when options are exercised or when RSUs vest.
Convertible debt: Bonds that holders can exchange for a set number of common shares.
Warrants: Contracts giving holders the right to purchase new shares at a fixed price.
Converting these instruments creates new shares, which dilutes existing ownership by spreading the same net income over a larger denominator. Diluted share counts are always equal to or higher than basic share counts. When evaluating earnings per share, using diluted share counts provides a more conservative and realistic view of your true profit claim.
According to reporting standards overseen by the U.S. SEC, public companies must state both basic and diluted share counts in their regular financial disclosures.
How Corporate Actions Change Share Counts
A company's share count is not static; management actions cause it to expand or shrink over time:
Share buybacks: When a company uses excess cash to buy back its stock, those shares move into treasury stock. This reduces total shares outstanding and increases each remaining share's percentage ownership of future profits.
Stock splits: In a 2-for-1 stock split, the share count doubles while the price per share splits in half. Total business value and individual ownership percentages remain unchanged.
Secondary offerings: Issuing new shares to raise capital increases total shares outstanding, which dilutes existing shareholders unless earnings grow fast enough to offset the expansion.
Common Share Count Pitfalls: What to Watch Out For
When reviewing share count figures on financial statements, watch out for these analytical traps:
Confusing par value with share count: Par value is an accounting baseline (e.g., $0.001 per share) used for capital recording. Do not mistake par value dollar totals for the number of physical shares.
Ignoring weighted average share count: Income statements calculate EPS using a weighted average share count across the year, accounting for mid-year buybacks or stock issuances.
Overlooking debt-funded buybacks: A declining share count boosts earnings per share, but if management takes on expensive debt to fund those buybacks, long-term balance sheet health suffers.
In practice, many long-term investors find that checking the trend in diluted share count over a 5-to-10-year window reveals whether management is creating value through buybacks or quietly diluting shareholders through excessive option grants.
Conclusion
Calculating shares outstanding is a fundamental accounting skill that helps you measure true business valuation, calculate earnings per share, and identify ownership dilution. By checking the Stockholders' Equity section of a balance sheet and comparing basic versus diluted share counts, you can clearly evaluate how corporate actions affect your underlying stake.
However, performing manual balance sheet calculations across hundreds of individual companies requires significant time and accounting familiarity. If your strategy focuses on investing in stocks through broad index funds, you do not need to manually compute corporate share counts. Index funds automatically adjust for share splits, buybacks, and secondary issuances, which may let you track the broad market's performance without managing individual balance sheets.
Investing involves risk, including the potential loss of principal, and historical balance sheet trends do not guarantee future corporate growth. Treat financial metrics as educational tools within a balanced research framework. When you are ready to evaluate trading platforms and account types for your portfolio, our broker reviews provide a practical place to start.
FAQ
5 questions
How do you calculate common shares outstanding from a balance sheet?
Locate the Stockholders' Equity section on a balance sheet (SEC Form 10-K). Find the total number of issued common shares and subtract any shares listed as treasury stock or repurchased shares.
What is the basic formula for shares outstanding?
The fundamental formula is: Shares Outstanding = Total Issued Shares − Treasury Shares. If a company has not repurchased any shares, total issued shares and shares outstanding are identical.
What is the difference between basic and diluted shares outstanding?
Basic shares outstanding includes only common stock currently held by shareholders. Diluted shares outstanding includes all basic shares plus potential shares that would exist if stock options, warrants, and convertible debt were exercised.
How do share buybacks affect the number of shares outstanding?
When a company buys back its own stock, those shares enter treasury stock. Because treasury shares are subtracted from total issued shares, corporate buybacks reduce the total number of shares outstanding.
What is the difference between issued shares and outstanding shares?
Issued shares represent the cumulative total of shares created and distributed by a company since its inception. Outstanding shares represent the net remaining shares after subtracting treasury stock held by the firm.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.