A front-end load is an upfront sales commission charged when purchasing mutual fund shares, most commonly Class A shares. The fee is subtracted directly from your initial capital before your money is invested, reducing your starting principal on day one. Long-term investors often opt for no-load funds or low-cost index ETFs to avoid upfront sales charges entirely.
This upfront commission is deducted from your initial mutual fund investment before the money enters the market. If you deposit $10,000 but the fund charges a 5% load, only $9,500 actually goes to work for you on day one. For a long-term investor, taking a bite out of your starting principal creates a permanent drag on portfolio growth. This guide covers how these upfront charges are calculated, how they differ from exit fees, and the long-term cost to your compounding returns.
Quick Takeaways
01This upfront sales charge immediately reduces your starting principal.
02The fee compensates the broker who sold the fund, not the fund manager.
03These charges are commonly found in Class A mutual fund shares.
04You can avoid upfront commissions entirely by choosing no-load mutual funds or low-cost index ETFs.
What Is a Front-End Load?
This charge is a sales commission collected at the moment you purchase a fund. In a traditional front end load mutual fund, this cost is expressed as a percentage of your total investment amount.
Historically, these commissions were standard across the wealth management industry. Mutual funds that carry sales charges are grouped into share classes, with Class A shares traditionally imposing this type of fee. When you buy a Class A share, the fund company subtracts the commission payment immediately and distributes the remaining balance to purchase fund shares at the net asset value (NAV)—the per-share price of the fund. Understanding how these charges sit alongside annual mutual fund fees is a key step in evaluating your overall cost of investing.
How a Front-End Load Works
When you invest in a fund with an upfront sales charge, your starting principal drops before your money ever hits the market. The fund company calculates the fee as a percentage of your gross purchase price, reducing your net invested capital.
You can calculate your working starting capital using this plain-text formula:
For example, if you place $10,000 into a fund with a 5% front-end load:
Initial Investment: $10,000
Sales Load (5%): $500
Actual Capital Invested: $9,500
In practice, many long-term investors find that starting $500 behind requires their fund to gain over 5.26% just to break even on principal, before generating a single dollar of real profit.
Front-End Load vs. Back-End Load (Exit Fee)
The main difference between this charge and a back-end load lies in when the fund company collects its commission. While a front-end charge takes money out on day one, a back-end load—often structured as a contingent deferred sales charge or exit fee—deducts a commission when you sell your shares.
Feature
Front-End Load
Back-End Load (Exit Fee)
Timing of Fee
Deducted immediately upon purchase
Deducted when you sell or redeem shares
Share Class
Typically Class A shares
Typically Class B or C shares
Impact on Principal
Reduces initial working capital on day one
Preserves starting principal; reduces final payout
While an exit charge allows your full principal to work initially, it can still reduce your final returns if you redeem shares early.
The 10-Year Cost: How Upfront Fees Drag Down Compounding
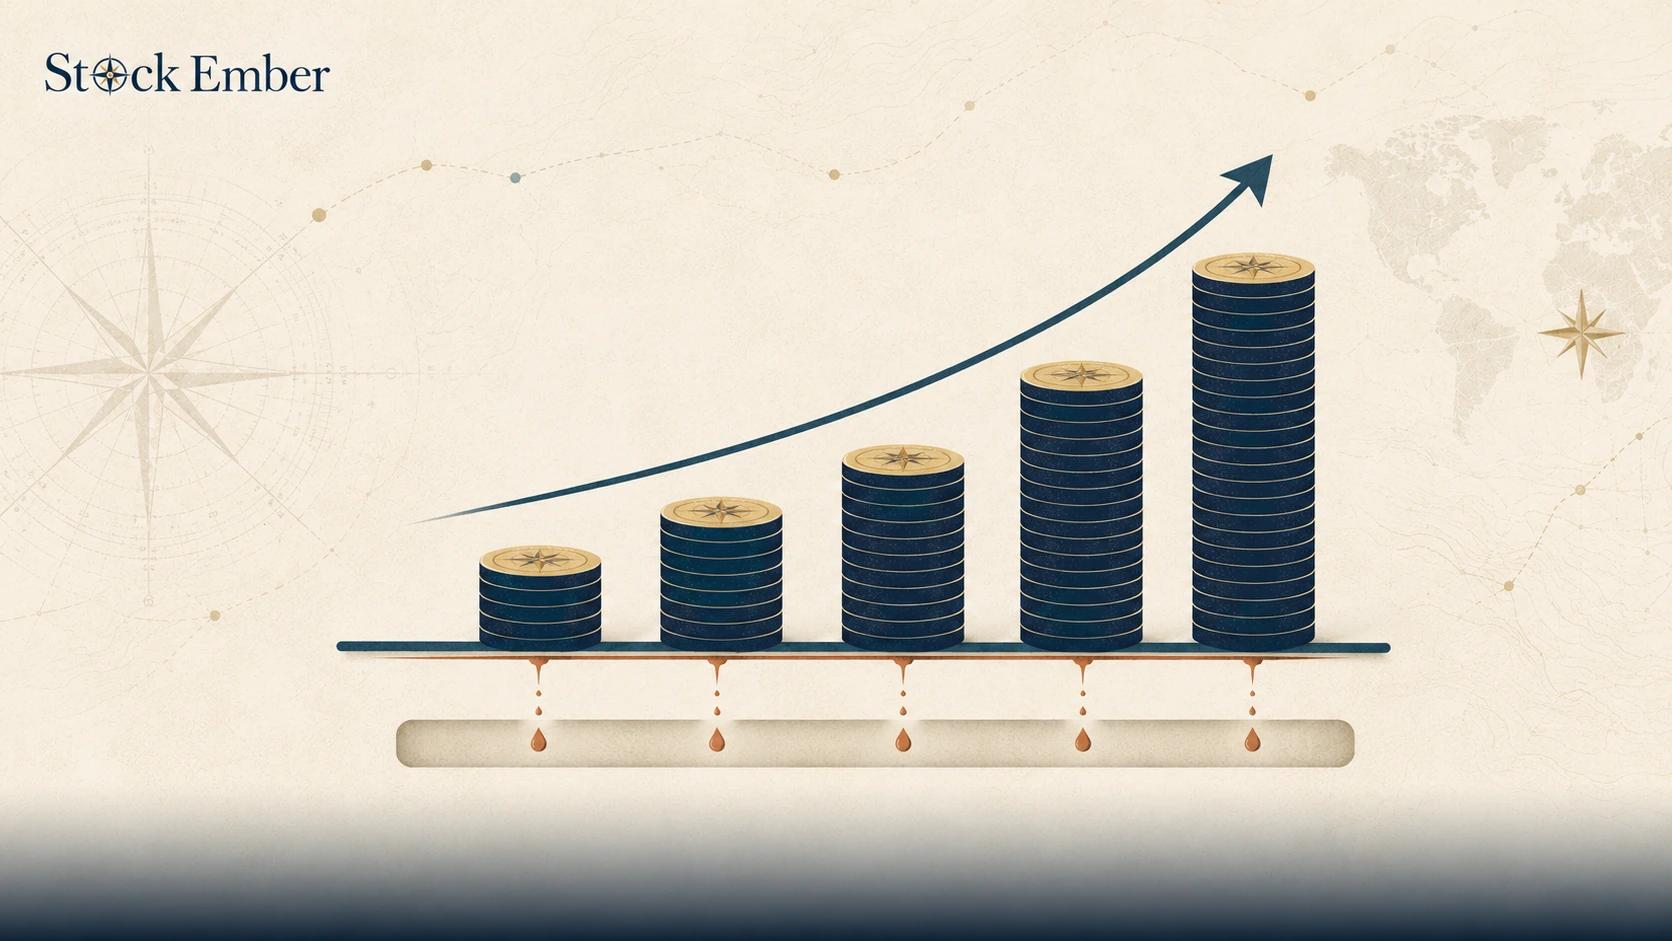
Losing a portion of your principal on day zero does far more damage than simply losing the upfront dollar amount. Over a ten-year holding period, that missing capital cannot compound, creating a permanent drag on your overall portfolio growth.
Consider two hypothetical portfolios starting with a $10,000 allocation, both earning a 7% annualized return over ten years:
Portfolio A (No-Load Fund): Starts with $10,000 working on day one. At 7% annual growth, it grows to $19,672 after ten years.
Portfolio B (With a 5% Sales Charge): Starts with $9,500 after paying a $500 fee. At 7% annual growth, it grows to $18,688 after ten years.
The initial fee was $500, but the actual ten-year cost is $984 ($19,672 minus $18,688). That extra $484 represents lost compounding returns on the money subtracted at the start.
Breakpoint Discounts and No-Load Alternatives
Fund families often offer reduced sales charges, known as breakpoint discounts, for investors who make larger dollar commitments. Under standard regulatory guidelines set by the Financial Industry Regulatory Authority (FINRA), maximum mutual fund sales charges are capped at 8.5%, and funds must clearly disclose breakpoint schedules.
For example, a fund might charge a 5.75% load for purchases under $25,000, but lower the charge to 4.50% for investments between $25,000 and $50,000. However, for most self-directed investors, the easiest alternative is choosing no-load mutual funds or exchange-traded funds (ETFs), which charge zero sales commissions.
Common Pitfalls to Avoid
When evaluating funds with front-end sales charges, watch out for two frequent mistakes:
Assuming High Fees Equal Better Performance: This fee compensates the selling broker, not the fund manager. High sales charges do not indicate superior stock-picking ability or lower portfolio risk.
Confusing Sales Charges with Expense Ratios: This charge is a one-time sales commission. You will still pay an ongoing annual expense ratio for management and administrative costs every year you hold the fund.
Conclusion
Minimizing upfront friction is one of the most direct ways to protect your long-term wealth building. By avoiding upfront sales charges and starting with 100% of your capital deployed, you preserve the full power of compound growth over time.
When planning your asset allocation, running the math on potential charges helps you keep more of your returns. To test how different fee structures impact your actual portfolio growth over time, explore our investment calculators. Investing always puts your money at risk and past returns never promise the future, so treat this as a starting point for your own research, not a recommendation.
FAQ
5 questions
Is a front-end load a one-time fee?
Yes, this fee is a one-time sales commission charged at the moment you purchase shares in a mutual fund. However, paying an upfront load does not exempt you from ongoing costs. You will still pay the fund's annual expense ratio for management and administrative expenses every year you hold the investment.
What is the difference between a front-end load and an expense ratio?
This charge is a single sales charge deducted from your initial deposit before your capital is invested. An expense ratio is an ongoing annual fee expressed as a percentage of your total asset value, deducted automatically to cover fund management, administration, and operating expenses.
What are breakpoint discounts in mutual funds?
Breakpoints are volume discounts offered by mutual fund companies that lower this sales charge percentage when an investor commits a larger sum of money. For example, a fund might charge a 5.75% load for purchases under $25,000, but reduce the sales charge to 4.50% for investments that cross the $25,000 threshold.
Do no-load mutual funds still charge fees?
Yes, no-load mutual funds do not charge upfront or back-end sales commissions, but they still charge annual operating fees known as expense ratios. While avoiding sales loads keeps 100% of your principal working from day one, you must still review the fund's annual expense ratio to understand its total cost over time.
Can I avoid front-end loads by buying index funds or ETFs?
Yes, most modern index mutual funds and exchange-traded funds (ETFs) are structured as no-load investments. By purchasing commission-free index funds or ETFs through a discount brokerage, investors can avoid upfront sales commissions completely and ensure that 100% of their initial deposit goes directly into active market assets.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.