An ADR fee is a custodial pass-through charge levied by US depositary banks to cover the administration, foreign share custody, and dividend processing of American Depositary Receipts. Ranging typically from $0.01 to $0.05 per share annually, brokers collect these charges directly from cash dividends or uninvested account cash balances.
An ADR fee is a service charge levied by US depositary banks for managing American Depositary Receipts, which allow domestic investors to hold shares of foreign companies locally.
When buying foreign stock through a US exchange, investors often notice small periodic deductions listed on their brokerage statements. While individual charges appear nominal, unmonitored custody costs add up over long holding periods. This guide breaks down what an adr fee is, how depositary banks collect pass-through charges, and how these ongoing costs impact your long-term investment returns.
Quick Takeaways
01An ADR fee is a custodial pass-through charge collected by US depositary banks for issuing and administering foreign company receipts.
02Typical fees range from $0.01 to $0.05 per share annually, deducted either from cash dividends or directly from account cash balances.
03Even non-dividend-paying foreign shares incur ADR fees, which can create unexpected negative cash balance alerts if unmonitored.
04Evaluating total holding costs helps long-term investors prevent subtle fee drag across international stock allocations.
What Is an ADR Fee?
An ADR fee—also known as an adr custody fee—is a custodial service fee charged by US depositary banks to cover the administration, recordkeeping, and cross-border settlement of American Depositary Receipts (ADRs).
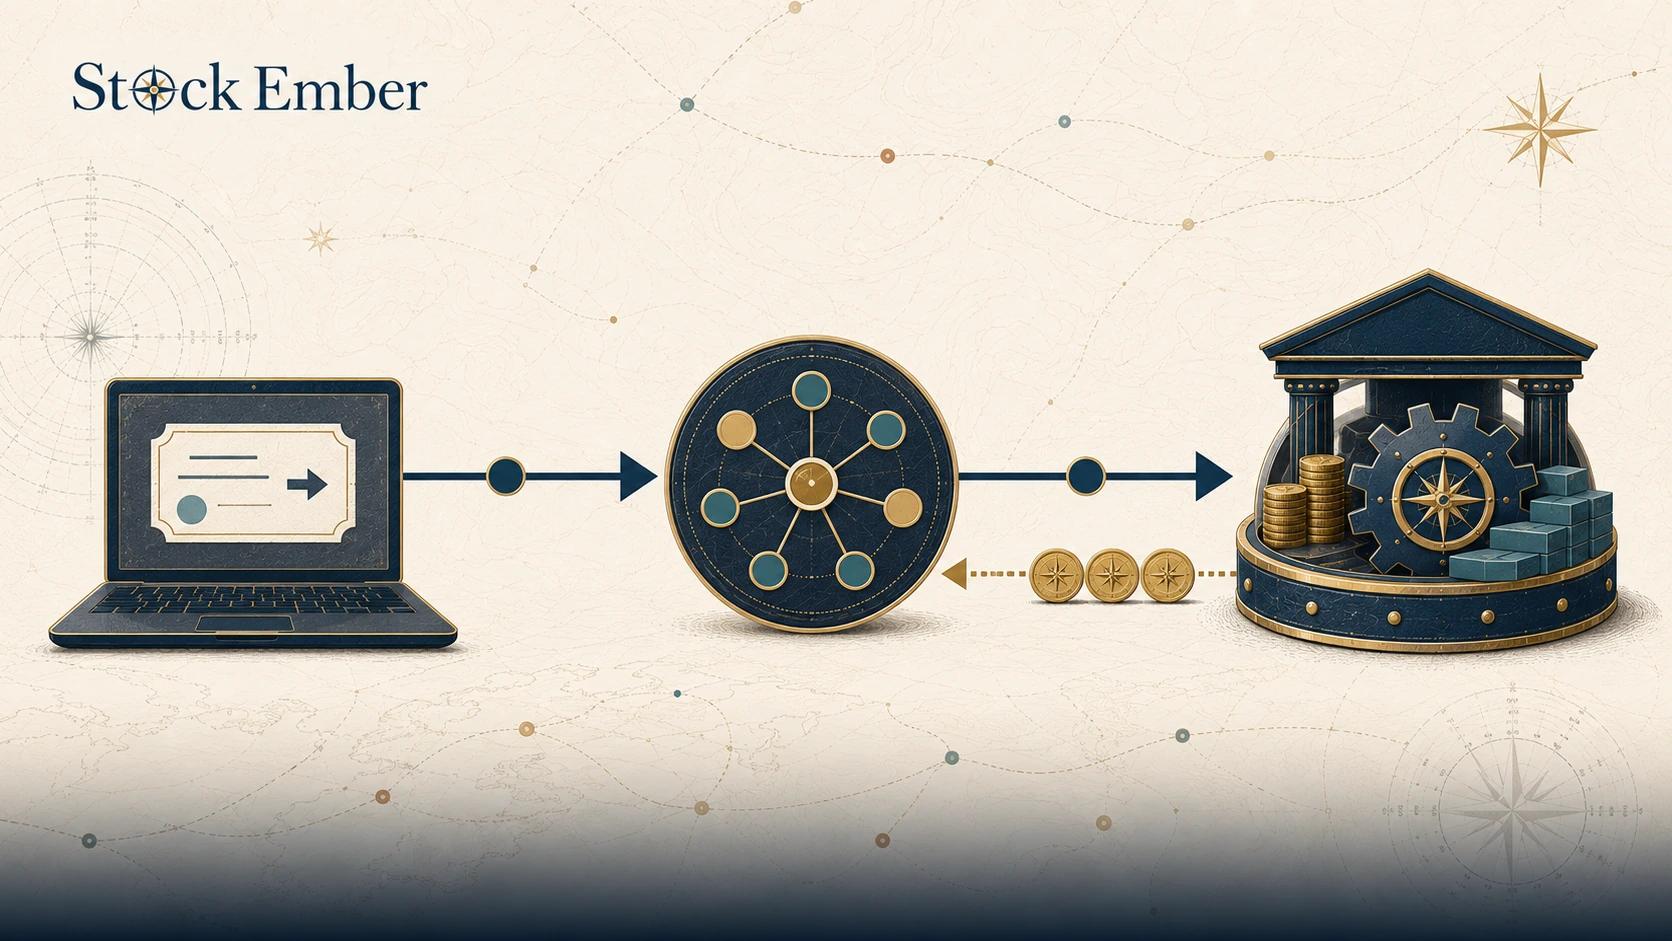
To understand adr fee meaning, it helps to review how foreign shares reach domestic exchanges. American Depositary Receipts allow investors to buy foreign equity in US dollars without managing international brokerage accounts. To enable this, a major depositary bank—such as BNY Mellon, Citibank, or JPMorgan Chase—holds the actual foreign shares in custody abroad and issues domestic depositary receipts.
Because managing these cross-border assets incurs operating costs, depositary banks charge ongoing maintenance fees. It is important to separate these depositary charges from standard brokerage trading commissions or local country financial transaction tax levies. When evaluating the cost of investing, ADR custody fees represent a distinct layer of ongoing ownership expense alongside standard fund expense ratios.
How ADR Fees Work: Collection & Pass-Through
ADR custody fees are established by depositary banks and passed down to retail investor accounts through a standardized settlement network.
The collection process relies on a multi-tier pass-through system. The depositary bank reports its custody and administration schedule to the Depository Trust Company (DTC). The DTC collects the required amounts from retail brokerage firms holding the receipts, and brokerages then debit those exact charges from individual account holders.
Depositary banks collect these pass-through fees through two main channels:
Dividend Deductions: If the foreign company pays a cash dividend, the depositary bank subtracts its fee directly from the gross dividend payment before converting and disbursing the net cash to your account.
Direct Cash Balance Debits: If the foreign issuer pays no dividend, or if the fee schedule operates on a fixed calendar date, your broker debits the charge directly from your uninvested account cash balance.
In practice, long-term investors often discover these deductions when reviewing annual account statements, where small penny-per-share entries appear under labels like "ADR Pass-Through Fee" or "Depositary Service Fee."
Fee schedules for each sponsored ADR program are disclosed in the depositary bank's SEC Form F-6 registration statement, which is publicly available through the SEC's EDGAR database.
Typical ADR Fee Ranges & Share Ratios
According to fee schedules published by major depositary banks such as BNY Mellon and Citibank, ADR custody fees typically range from $0.01 to $0.05 per share annually. Depending on the issuer, geographic region, and depositary agreement.
These costs are assessed annually or semi-annually. In addition to basic custody fees, depositary banks may assess fees for corporate actions, dividend distribution processing, or foreign currency conversion.
Fee Type
Typical Charge Range
Frequency / Trigger
Custody / Maintenance Fee
$0.01 – $0.05 per share
Annual or semi-annual assessment
Dividend Payment Fee
$0.01 – $0.02 per share
Deducted at dividend payout date
Corporate Action Fee
$0.02 – $0.05 per share
Triggered by stock splits, spin-offs, or mergers
Total fee calculations also depend on the ADR share ratio. Depositary agreements set a specific ratio between one American Depositary Receipt and the underlying ordinary shares abroad. For example, if 1 ADR represents 5 ordinary foreign shares, the custody fee applies to the single domestic receipt you hold, not the five foreign shares held in the overseas vault.
The 10-Year Cost of Ownership: Long-Term Portfolio Drag
While a fee of three cents per share sounds nominal, evaluating fee impact across a ten-year horizon reveals how small recurring charges erode total compound growth.
Consider an investor who purchases 1,000 shares of a non-dividend-paying international company structured as an ADR. Assuming an annual custody fee of $0.03 per share, the investor pays $30 per year in depositary charges. Over a ten-year holding period, direct custody fees total $300.
While $300 appears modest on a large holding, the true expense lies in missed compound returns. If that $30 annual charge were instead retained and compounded at an illustrative 7% average annual rate of return, the total cumulative cost drag reaches approximately $414 over ten years. Across a diversified portfolio holding multiple foreign receipts, unmonitored custody charges gradually reduce net portfolio performance over long investment horizons.
Common Mistakes & What to Watch
Managing international equity costs requires avoiding three frequent investor oversights regarding depositary charges.
Unintended Negative Cash Balances: Holding non-dividend foreign receipts in accounts without cash reserves can trigger negative balance alerts or margin interest charges when periodic fees are assessed.
Confusing Taxes with Depositary Fees: Investors frequently mistake ADR fees for foreign dividend withholding taxes. Foreign taxes are levied by overseas tax authorities, whereas ADR fees are service payments kept by US depositary banks.
Ignoring SEC Form F-6 Disclosures: Fee schedules are fully public before purchase. Reviewing SEC filings or your brokerage firm's fee disclosure document prevents surprises regarding corporate action fees or dividend processing deductions.
Conclusion: Managing ADR Fee Impact in Your Portfolio
An adr fee is an administrative cost associated with holding foreign equity locally on domestic US exchanges. Collected by depositary banks and passed through retail brokers, these per-share charges cover cross-border custody, recordkeeping, and currency conversion. While individual charges remain small, tracking recurring custody costs ensures long-term buy-and-hold investors protect their portfolio growth from unnecessary drag.
When planning long-term asset allocation and evaluating overall holding costs, using interactive investment tools can help you model the true impact of recurring expenses on your portfolio over time. Investing always puts your money at risk and past returns never promise the future, so treat this as a starting point for your own research, not a recommendation.
FAQ
4 questions
What is an American Depositary Receipt (ADR) fee?
An ADR fee is a periodic custody charge passed on by depositary banks to cover the administration, holding, and dividend processing costs of foreign stocks listed on U.S. exchanges.
How and when are ADR fees deducted from my account?
Brokers typically deduct ADR fees directly from your available cash balance or subtract them automatically from your dividend payouts, usually ranging from $0.01 to $0.05 per share annually.
Do foreign stocks that pay no dividends still charge ADR fees?
Yes. Even if a foreign company does not distribute dividends, the depositary bank can still collect annual custodial fees directly through your brokerage account.
How can long-term investors minimize the impact of ADR fees?
Investors can review a foreign stock's prospectus before investing to check fee structures, or opt for international index ETFs where custody expenses are already bundled into the overall fund expense ratio.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.