A pension is a defined benefit retirement plan funded primarily by an employer to provide a retired worker with predictable monthly income for life. Payout amounts are determined by a contractual formula based on years of service and salary history rather than individual investment returns. While the employer shoulders the market risk, fixed pension checks face purchasing power erosion over time if they lack cost-of-living adjustments.
A pension is an employer-sponsored retirement plan that pays you a set monthly income for the rest of your life after you retire.
Traditional pensions once formed the backbone of retirement security for workers. While workplace savings plans like a 401(k) have largely replaced them in private companies, millions of employees still rely on pension checks to fund their later years. This guide explains how pensions work, how payouts are calculated, the risks of inflation and plan solvency, and how to weigh monthly checks against a lump-sum buyout.
Quick Takeaways
01A pension is a defined benefit plan that pays regular monthly income in retirement.
02The employer shoulders the investment risk, unlike a 401(k) where the worker bears market swings.
03Payouts follow a formula based on your service years and salary history.
04Vesting rules require minimum service before accrued benefits permanently belong to you.
05Flat monthly checks without inflation adjustments lose real purchasing power over ten years.
What Is a Pension?
A pension is a retirement plan where an employer commits to paying a worker regular income for life after they retire.
Understanding the broader pension meaning centers on its legal role as a defined benefit plan. In this structure, your retirement income is set by a formula rather than by how well an investment account performs. According to the Pension Benefit Guaranty Corporation (PBGC), a defined benefit pension promises a specified monthly benefit at retirement based on factors such as salary and years of service.
The defining feature of a pension is that your employer takes on the financial risk. In a personal retirement account, you choose investments and absorb any market drop. In a pension, the employer funds a pooled trust and carries all market risk, covering any shortfall to pay promised checks.
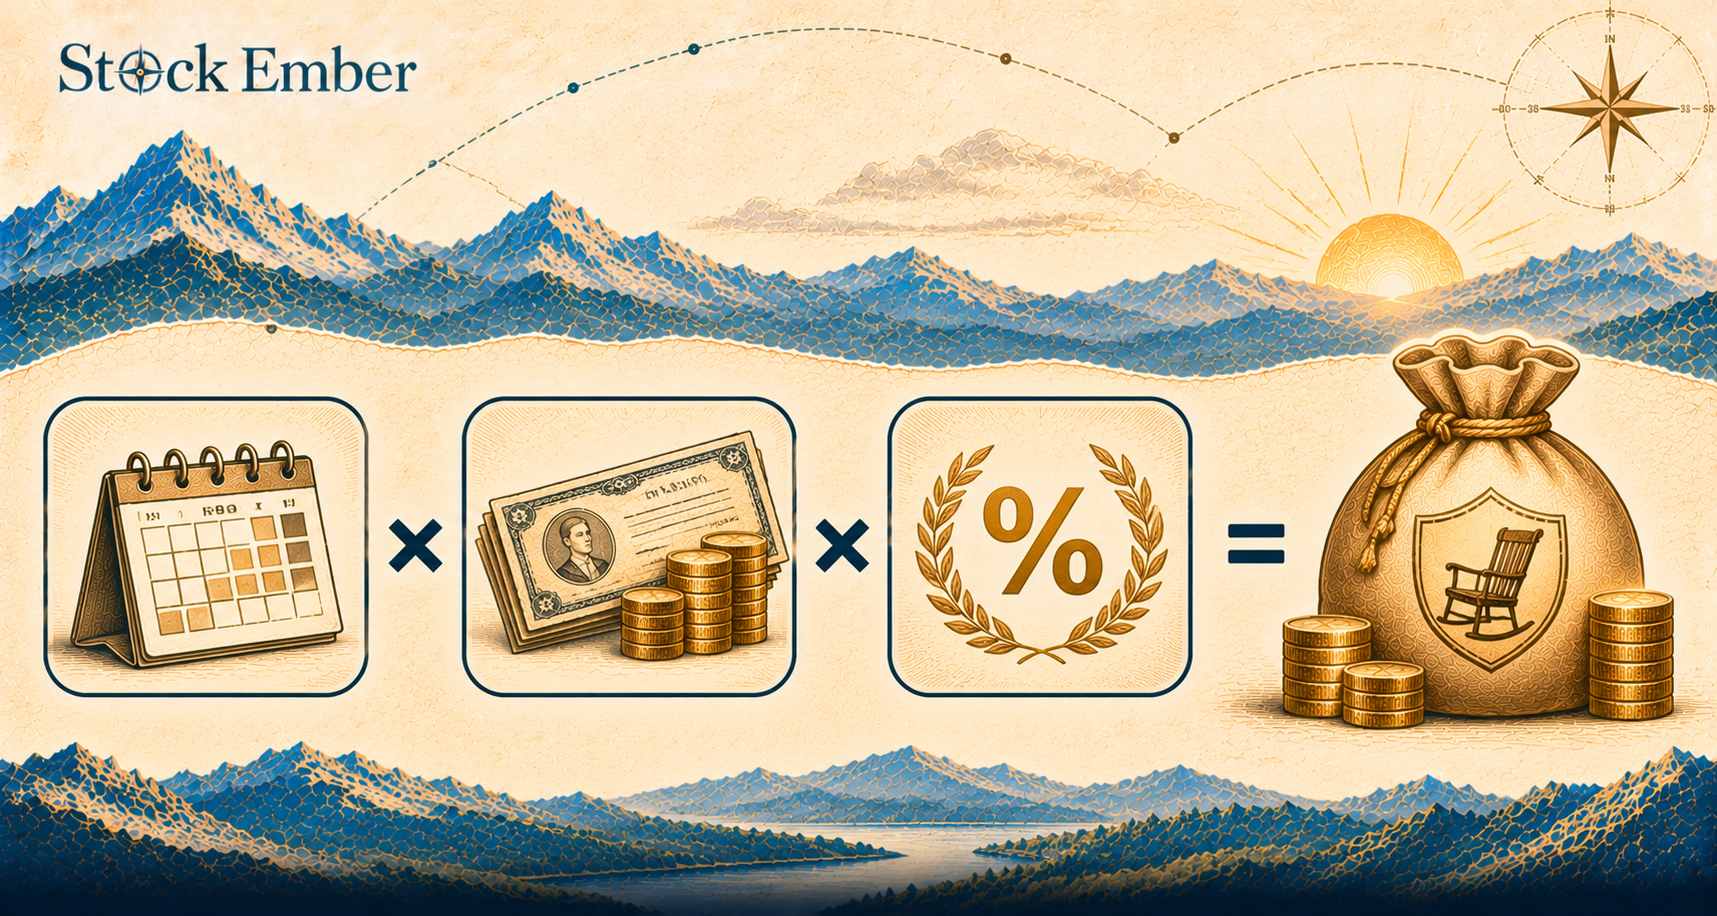
Diagram showing how a pension benefit formula calculates retirement income
How a Pension Works
A pension works by tracking your service years and converting your salary history into lifetime monthly checks upon retirement.
Having a pension explained step-by-step comes down to two mechanisms: the benefit formula and the vesting schedule.
Most plans calculate your annual benefit using this formula:
Annual Pension Payout = Years of Service × Final Average Salary × Benefit Multiplier
Years of service reflects how long you worked for the employer. Final average salary is the average of your highest consecutive earning years. The benefit multiplier is a percentage set by the employer, commonly between 1% and 2.5% per year of service depending on the plan. For example, an employee with 25 years of service, an $80,000 final average salary, and a 1.5% multiplier receives an annual pension of $30,000 ($2,500 per month).
Before qualifying for payouts, you must satisfy the plan's vesting schedule, the minimum time you must work before benefits permanently belong to you.
Vesting Type
How It Works
Time to Full Ownership
Cliff Vesting
Zero ownership until a set date, then 100% all at once
Up to 5 years under federal law (3 years for some hybrid plans)
Graded Vesting
Partial ownership that grows each year until reaching 100%
Up to 7 years: 20% after year three, then 20% more each year until 100%
In practice, many long-term workers misjudge how vesting rules interact with career moves. Leaving a job just months before hitting a cliff milestone can mean forfeiting the pension benefits you earned under that plan.
Defined Benefit vs Defined Contribution Plans
The difference between retirement plans comes down to whether the employer or the employee bears the investment risk.
Traditional pensions are defined benefit plans, whereas modern workplace accounts like a 401(k) are defined contribution plans.
Feature
Traditional Pension (Defined Benefit)
401(k) / IRA (Defined Contribution)
Investment Risk
Borne by the employer
Borne by the employee
Primary Funding
Paid by the employer into a pooled trust
Paid by the employee through pay deductions
Benefit Amount
Set by formula for life
Based on market returns and total savings
Portability
Tied to the employer
Easily rolled over to another provider
In a defined contribution plan, your balance depends on your savings rate and market returns. A pension removes market worry, transferring funding shortfalls entirely to your employer.
The 10-Year Inflation Threat and Solvency Risks
Pensions offer steady income, but they face two quiet threats over time: inflation erosion and employer insolvency.
Inflation poses the biggest danger to retirees. While some public pensions offer a Cost-of-Living Adjustment (COLA), most private pensions pay a flat dollar amount for life. Consider the 10-year purchasing power impact on a fixed $2,500 monthly payment. Under a modest 3.0% annual inflation rate, the purchasing power of that check drops by roughly 26% over ten years. After a decade, your $2,500 check buys only about $1,860 worth of goods.
The second threat is sponsor insolvency. If an employer goes bankrupt and underfunds its pension, the plan may terminate. In the United States, the federal PBGC insures most private-sector traditional pensions and pays covered benefits up to legal maximums that are adjusted every year. For plans that terminate in 2026, for example, the maximum for a 65-year-old receiving a straight-life annuity is $7,789.77 per month, and it is lower for people who start benefits earlier. As a result, high earners or early retirees can face real cuts to their payouts.
Monthly Annuity vs Lump-Sum Buyout
When retiring, employers often let you pick between a lifetime monthly annuity and a one-time lump-sum payout.
A lifetime monthly annuity gives you a dependable income floor for life. But a single-life annuity ends the moment you die, leaving nothing for your heirs. A joint-and-survivor option protects a spouse, but reduces your monthly check.
A lump sum gives you complete control over your money, but puts investment risk back on you. Rolling a lump sum into self-directed accounts lets you invest in low-cost index funds. When shaping your tax plan, funding a Roth IRA provides tax-free growth and flexible withdrawal rules for passing wealth to heirs. For high-earning workers who lack pensions, retirement strategies like a mega backdoor Roth allow employees to save after-tax dollars inside tax-free accounts.
Conclusion
A traditional pension provides valuable income stability by shifting market risk onto your employer. Yet fixed payouts carry real trade-offs, including purchasing power erosion over ten years, plan solvency limits, and the loss of estate inheritance. Deciding whether to keep an income stream or take a lump sum depends on your health, your existing savings, and your goals for leaving a legacy.
When you are ready to evaluate platforms for managing your retirement savings, our Broker reviews can help you compare available account features.
Every retirement vehicle carries trade-offs, and company-backed pensions depend on the long-term solvency of the plan sponsor. Treat this overview as an educational foundation for your retirement planning, not as personalized financial advice.
FAQ
5 questions
Is pension income taxable when you withdraw it?
Yes, pension payouts are generally treated as taxable income in the year you receive them. Because most traditional pensions are funded with pre-tax dollars by employers, your monthly distributions are taxed at ordinary income tax rates at both the federal and state levels. If you contributed after-tax dollars during your working years, only the portion of the payout representing employer contributions and earnings is taxed.
What happens to your pension if you leave your job early?
If you leave your job after meeting the plan's vesting requirements, your accrued benefits remain intact. You will qualify for a deferred pension payout once you reach the plan's standard retirement age. However, if you leave before completing the required vesting period, you forfeit any employer-funded retirement credits, though you retain full ownership of any personal contributions you made.
Can an employer freeze or terminate a pension plan?
Yes, employers can freeze or terminate a defined benefit pension plan. In a soft freeze, current workers keep accruing benefits, but new hires cannot join. In a hard freeze, all future benefit accruals cease for everyone. Under federal law, an employer cannot reduce benefits that employees have already earned and vested prior to the freeze or termination date.
Do employees contribute their own money to a pension?
In the private sector, employers typically fund traditional defined benefit pensions entirely without requiring employee pay deductions. In contrast, state and local government pensions frequently require public employees—such as teachers, firefighters, and municipal workers—to contribute a fixed percentage of each paycheck alongside mandatory agency contributions to fund future retirement checks.
What is the difference between a single-life and joint-and-survivor pension?
A single-life pension provides the highest monthly payout, but checks stop completely when the retiree dies, leaving nothing for a surviving partner. A joint-and-survivor pension pays a smaller monthly check during your lifetime, but promises that a set percentage (typically 50% to 100%) will continue flowing to your surviving spouse for the remainder of their life.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.