A mega backdoor Roth is a retirement funding method that allows eligible 401(k) participants to save beyond standard annual contribution caps by making after-tax payroll deposits and converting them into a Roth wrapper. Once inside the Roth IRA or Roth 401(k), the money grows completely tax-free and can be withdrawn without future federal taxes on qualified distributions. Executing the strategy requires a workplace plan that specifically allows voluntary after-tax contributions and in-service distributions or in-plan conversions.
A mega backdoor Roth is an advanced retirement savings strategy that lets you move after-tax contributions from an employer 401(k) into a tax-free Roth account, shielding extra savings from future income taxes.
Once savers max out standard workplace retirement limits, finding tax-efficient homes for extra cash becomes tough. Choosing this strategy changes your tax path by turning after-tax payroll dollars into assets that can grow tax-free, subject to Roth distribution rules and future tax law. This guide covers how plan rules work, the math behind annual limits, and the trade-offs of locking up capital.
Quick Takeaways
01The strategy allows savers to direct large amounts of extra savings into tax-free Roth status each year.
02Your employer plan must specifically allow after-tax non-Roth contributions and either in-plan conversions or in-service withdrawals.
03Converting funds immediately prevents taxable investment gains from building up in the after-tax account.
04Locking large sums away until retirement requires balancing tax sheltering against short-term liquidity needs.
What Is a Mega Backdoor Roth?
A mega backdoor Roth is a multi-step savings process that moves voluntary after-tax contributions from an employer retirement plan into a Roth wrapper.
When investors ask what mega backdoor Roth planning is, the core mega backdoor Roth meaning comes down to bypassing standard retirement contribution limits. In a workplace 401(k), the IRS recognizes 3 distinct contribution buckets: pre-tax traditional, designated Roth, and after-tax non-Roth. Put simply, the mega backdoor Roth explained here means using that third bucket.
You contribute money that has already been taxed, and then promptly convert those funds into a Roth account. This is not an official account name, but an administrative rollover path allowed under federal tax rules.
How It Works: The 415(c) Limit and Plan Rules
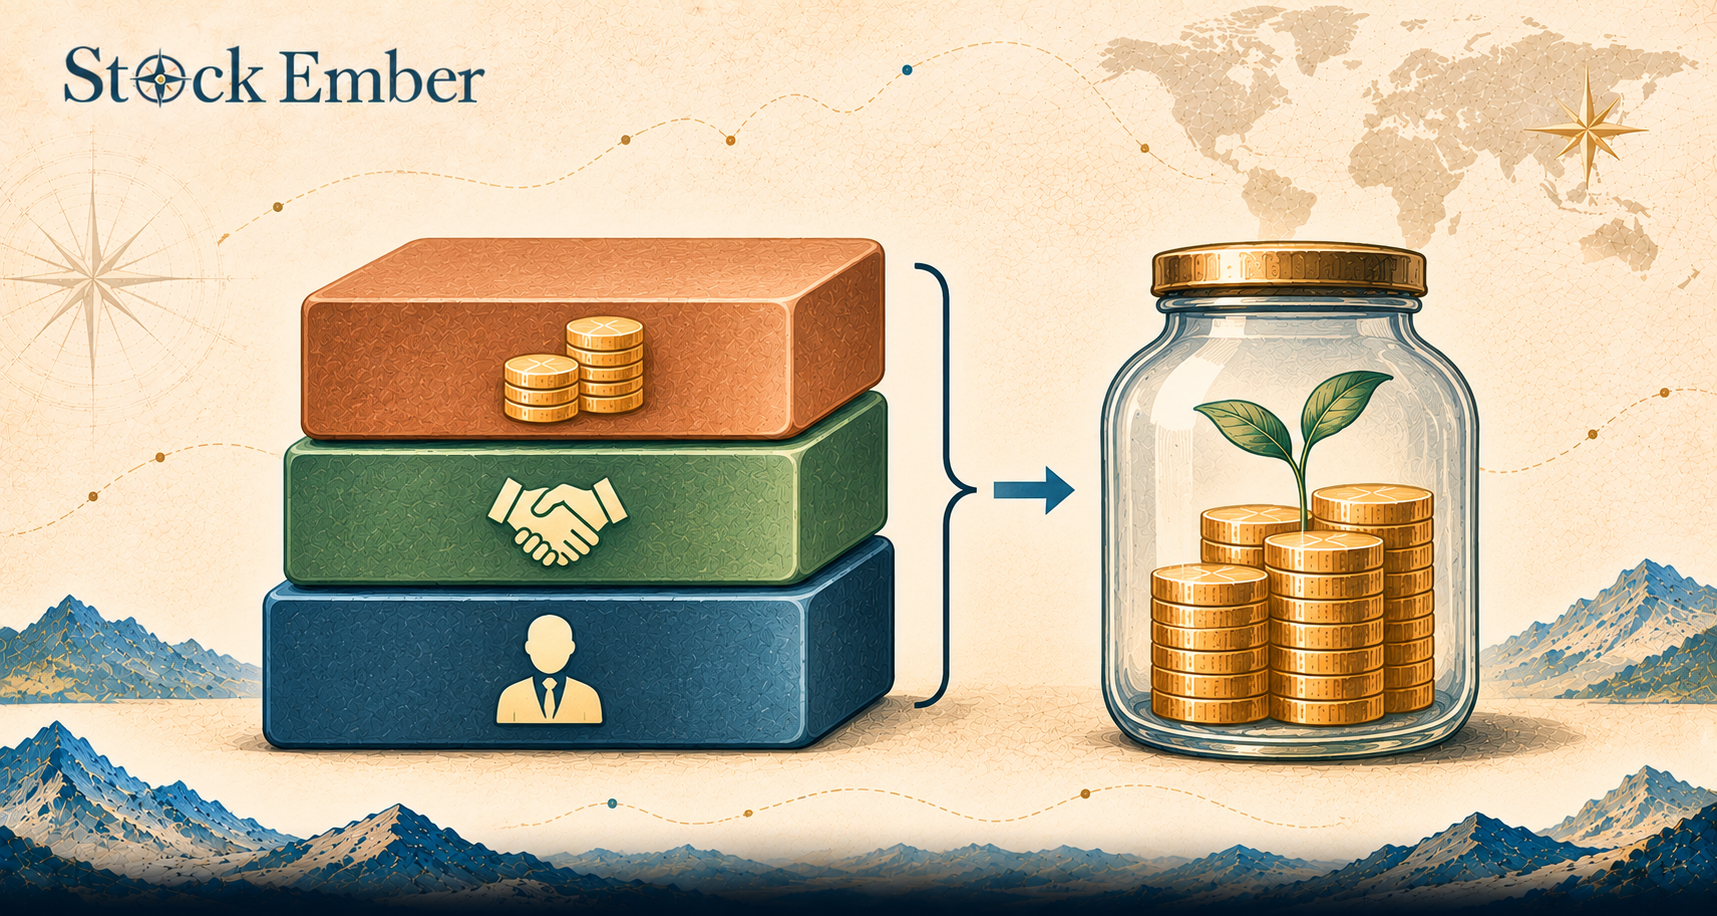
This strategy works by filling the gap between your standard employee contribution limit and the total annual additions cap set by the IRS.
Diagram breaking down the 3 parts of the annual 401(k) contribution ceiling
Under Internal Revenue Code Section 415(c), the IRS sets an overall annual additions limit for defined contribution plans. For 2026, this total ceiling is $72,000. You calculate your available after-tax space with a simple formula:
Available After-Tax Space = Section 415(c) Limit − Employee Elective Deferrals − All Employer Contributions (match and any profit sharing)
In 2026, the IRS caps employee elective deferrals at $24,500 under Internal Revenue Code Section 402(g). If you contribute $24,500 and your employer adds a $7,500 match, you use $32,000 of your space. That leaves up to $40,000 of headroom you can contribute as after-tax non-Roth dollars.
Executing this strategy requires 2 specific plan features. The plan must allow voluntary after-tax contributions beyond standard deferrals, and it must support in-service distributions to an outside account or automated in-plan Roth rollovers. As outlined by the IRS, savers can split distributions so after-tax principal moves to a Roth wrapper while any pre-conversion growth moves to a traditional account.
The 10-Year Compounding vs. Liquidity Trade-Off
Using this strategy matters because shielding large sums from yearly dividend and capital gains taxes saves real money, but it locks up cash you might need sooner.
Consider an illustrative 10-year scenario. Suppose you invest $30,000 of extra savings annually. In a standard taxable account, dividends and realized gains face taxation every year.
Over 10 years at an assumed 7% annual return, that steady tax drag may reduce your final balance. This 7% figure is a hypothetical assumption, not a forecast or guarantee, and actual returns can be lower or negative. Inside a Roth wrapper, that same $30,000 investment compounds without yearly taxes on dividends and gains, and qualified withdrawals are generally tax-free.
However, tax sheltering comes with a liquidity cost. Dollars placed into a retirement plan are intended for the long run. If you need money for a home purchase or business in the next decade, committing tens of thousands of dollars to a retirement account creates friction.
In practice, many long-term investors find that funding emergency reserves and near-term savings goals first provides the peace of mind needed before locking large sums of cash into after-tax retirement buckets.
Execution Paths: Roth IRA, In-Plan Conversion, or Taxable Brokerage
You can execute this approach by moving after-tax funds either into an outside Roth IRA or directly into your workplace Roth 401(k).
The first route is an in-service distribution to an external Roth IRA. Moving funds to your own IRA gives you full investment choice and broad access to low-cost index funds. The second route is an in-plan Roth conversion, where money stays inside your workplace plan but transfers into the designated Roth bucket. Many corporate plans offer automated daily in-plan conversions, which move after-tax deposits into the Roth bucket immediately.
When weighing a brokerage account vs. Roth IRA, a standard taxable account gives you access to your money at any time without early withdrawal penalties. This strategy provides superior tax sheltering, but an ordinary taxable account offers total liquidity for goals before retirement.
Common Mistakes and Plan Obstacles
The most common mistakes with this strategy involve conversion delays, employer plan nondiscrimination testing failures, and overcommitting personal cash flow.
A major risk is delaying the conversion. When after-tax money sits in an account before converting, it produces earnings. While your original contributions convert tax-free, any growth before conversion is taxed as ordinary income in the year you convert. Setting up automated conversions stops this tax drag before it starts.
Another hurdle is plan testing. Workplace plans must pass IRS Actual Contribution Percentage (ACP) nondiscrimination tests to ensure higher earners do not benefit disproportionately. If lower-paid employees contribute little after-tax money, the plan can fail. Plan administrators then refund the excess after-tax contributions to high earners, and the earnings on those refunds are generally taxable, disrupting your savings strategy.
Finally, do not overcommit your budget. Tying up large sums in retirement accounts can leave you short on everyday cash.
Conclusion
This after-tax 401(k) conversion strategy provides a rare way for high earners to move large amounts of cash into tax-free accounts, well beyond standard contribution caps. Success depends on verifying plan rules, calculating headroom under Section 415(c), and completing conversions immediately to avoid tax on earnings. For investors with full emergency reserves and maxed-out primary accounts, this strategy may offer decades of tax-sheltered compounding, though investment returns are not guaranteed.
When you are ready to evaluate platforms for your personal retirement accounts, our Broker reviews are the place to start. Market investments carry risk of loss, and tax laws can change over time, so treat this education as a guide for your own research rather than personal tax advice.
FAQ
5 questions
What is the difference between a backdoor Roth and a mega backdoor Roth?
A standard backdoor Roth uses an individual retirement account, where you make non-deductible contributions to a Traditional IRA and convert them to a Roth IRA, capped at annual IRA limits. A mega backdoor Roth takes place inside an employer 401(k) plan using after-tax non-Roth payroll contributions, allowing you to convert tens of thousands of dollars more each year up to the broader Section 415(c) additions cap.
Does having a Traditional IRA trigger the pro-rata rule on a mega backdoor Roth?
No. The standard IRA pro-rata rule applies when converting balances from an IRA, aggregating all your pre-tax IRA accounts. Because this strategy originates entirely inside your employer 401(k) plan, any pre-tax money sitting in a Traditional IRA has zero impact on your ability to convert after-tax 401(k) dollars cleanly into a Roth IRA or Roth 401(k).
Can you withdraw your converted mega backdoor Roth contributions right away?
Yes, if the funds were rolled over into a Roth IRA. Converted after-tax principal can generally be withdrawn penalty-free at any time because income taxes were already paid on those dollars prior to conversion. However, any investment growth included in the conversion is taxed as ordinary income in the year you convert, and withdrawing that converted amount within 5 years may trigger a 10% additional tax if you are under age 59½. Earnings that build up inside the Roth IRA after conversion are generally tax-free only on qualified distributions, which require a 5-year holding period and age 59½ or another qualifying event.
Do you need to file Form 8606 for a mega backdoor Roth?
Generally no, because Form 8606 tracks non-deductible contributions to a Traditional IRA, but you may need it if you hold after-tax basis in a Traditional IRA. A standard backdoor Roth requires IRS Form 8606 to track non-deductible IRA basis. In contrast, transactions for a mega backdoor Roth originate from your 401(k), and your plan administrator reports the after-tax rollover and any taxable earnings on IRS Form 1099-R.
What happens if your employer 401(k) plan fails ACP testing?
If a plan fails Actual Contribution Percentage testing, administrators must return excess after-tax contributions to highly compensated employees. When this happens, the plan issues a corrective distribution check for the refunded amount plus any associated investment growth. The refunded after-tax contributions are generally not taxed again, but you must report the investment growth included in the check as taxable income, which reduces the tax-sheltered savings you intended.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.