A 403(b) plan is a tax-advantaged US workplace retirement account offered to employees of public schools, universities, tax-exempt 501(c)(3) nonprofits, and certain ministries. Workers contribute directly from their paychecks into mutual funds or annuity contracts on either a pre-tax Traditional basis or an after-tax Roth basis. Some employers also match a portion of employee contributions, helping retirement savings compound over time.
A 403(b), also written 403b, is a United States employer-sponsored retirement account that gives public-school and qualifying nonprofit employees tax-advantaged ways to invest for retirement.
If you work at a public school, university, or nonprofit hospital, your benefits packet probably handed you a confusing list of insurance contracts and mutual funds with little guidance. Choosing poorly inside that menu can cost thousands of dollars in avoidable fees over a decade.
This guide has a 403b explained in plain terms: how it works, what its rules mean for your taxes, and how it compares to a 401(k) and a Roth IRA.
Quick Takeaways
01A 403(b) is an account wrapper, not an investment itself; your returns and risk depend on the mutual funds or annuity contracts you pick inside it.
02You can choose between Traditional pre-tax contributions for an upfront tax break or Roth after-tax contributions for tax-free withdrawals in retirement.
03Many public-school 403(b) menus include high-fee insurance annuities that can quietly strip thousands of dollars from your balance over 10 years.
04Pairing a workplace 403(b) with an individual retirement account gives you more flexibility if your employer's investment menu is expensive or narrow.
What Is the Meaning of a 403b Plan?
The 403b meaning comes straight from Section 403(b) of the US Internal Revenue Code, which created a tax-sheltered retirement account wrapper for public-sector and nonprofit workers. Historically known as a tax-sheltered annuity plan, a 403(b) is not an investment on its own; it is a tax-protected container that holds the mutual funds or insurance contracts you select inside it.
Under rules set by the IRS, eligibility is limited to employees of public schools and state universities, staff at tax-exempt 501(c)(3) nonprofits (organizations the IRS recognizes as charitable or educational, such as hospitals and charities), and certain ministers. Private for-profit businesses cannot offer a 403(b); they offer 401(k) plans instead.
How a 403b Works: Contributions, Taxes, and Employer Match
A 403b works through automatic payroll deductions that move part of each paycheck into your retirement account before you can spend it. Most plans let you choose between 2 tax treatments:
Traditional 403(b): Your contributions come out of your pay before federal income taxes, lowering your taxable income today. Your investments grow tax-deferred, and you pay ordinary income tax when you withdraw the money in retirement.
Roth 403(b): You contribute after-tax dollars today, so there is no upfront tax deduction, but qualified withdrawals in retirement come out tax-free.
Some nonprofit hospitals and universities also offer an employer match, adding extra money when you contribute from your paycheck. Your right to keep those employer dollars may depend on vesting, the schedule that determines when you own employer contributions outright.
For 2026, the IRS caps employee salary deferrals at $24,500, with an extra $8,000 catch-up contribution at age 50 or older, or $11,250 for workers ages 60 through 63. Unlike a 401(k), a 403(b) may also allow a special catch-up of up to $3,000 a year, with a $15,000 lifetime cap. This extra catch-up applies if you have worked for the same eligible employer for at least 15 years and your past yearly contributions averaged under $5,000.
403b vs. 401(k) and Roth IRA: How They Compare
A 403b follows almost identical tax and contribution rules to a 401(k), but it serves different employers and often comes with different oversight and investment menus.
Feature
403(b) Plan
401(k) Plan
Eligible employers
Public schools, universities, 501(c)(3) nonprofits, ministers
Private for-profit companies
Fiduciary oversight
Public-school plans are often exempt from federal fiduciary rules
Covered by federal fiduciary standards
Typical investments
Annuity contracts and mutual funds
Mutual funds, index funds, and target-date funds
Tenure catch-up
Up to $3,000/year after 15 years of service, if your plan allows it
None
Many public-school plans are exempt from the Employee Retirement Income Security Act (ERISA), the federal law that sets fiduciary standards for most private-sector workplace plans. Without that legal duty to curate low-cost options, school districts sometimes hand employees a long list of unvetted vendors. Because you cannot control your employer's menu, many workers contribute enough to capture any workplace match first and then open an individual Roth IRA if they want broader, lower-cost fund choices.
The 10-Year Cost Trap Inside Many 403b Plans
The biggest hidden drawback of a 403b is that many plans still center on high-fee insurance contracts rather than low-cost index funds. Under federal tax rules, 403(b) accounts generally hold either annuity contracts (insurance products that hold and pay out retirement money) or mutual fund custodial accounts.
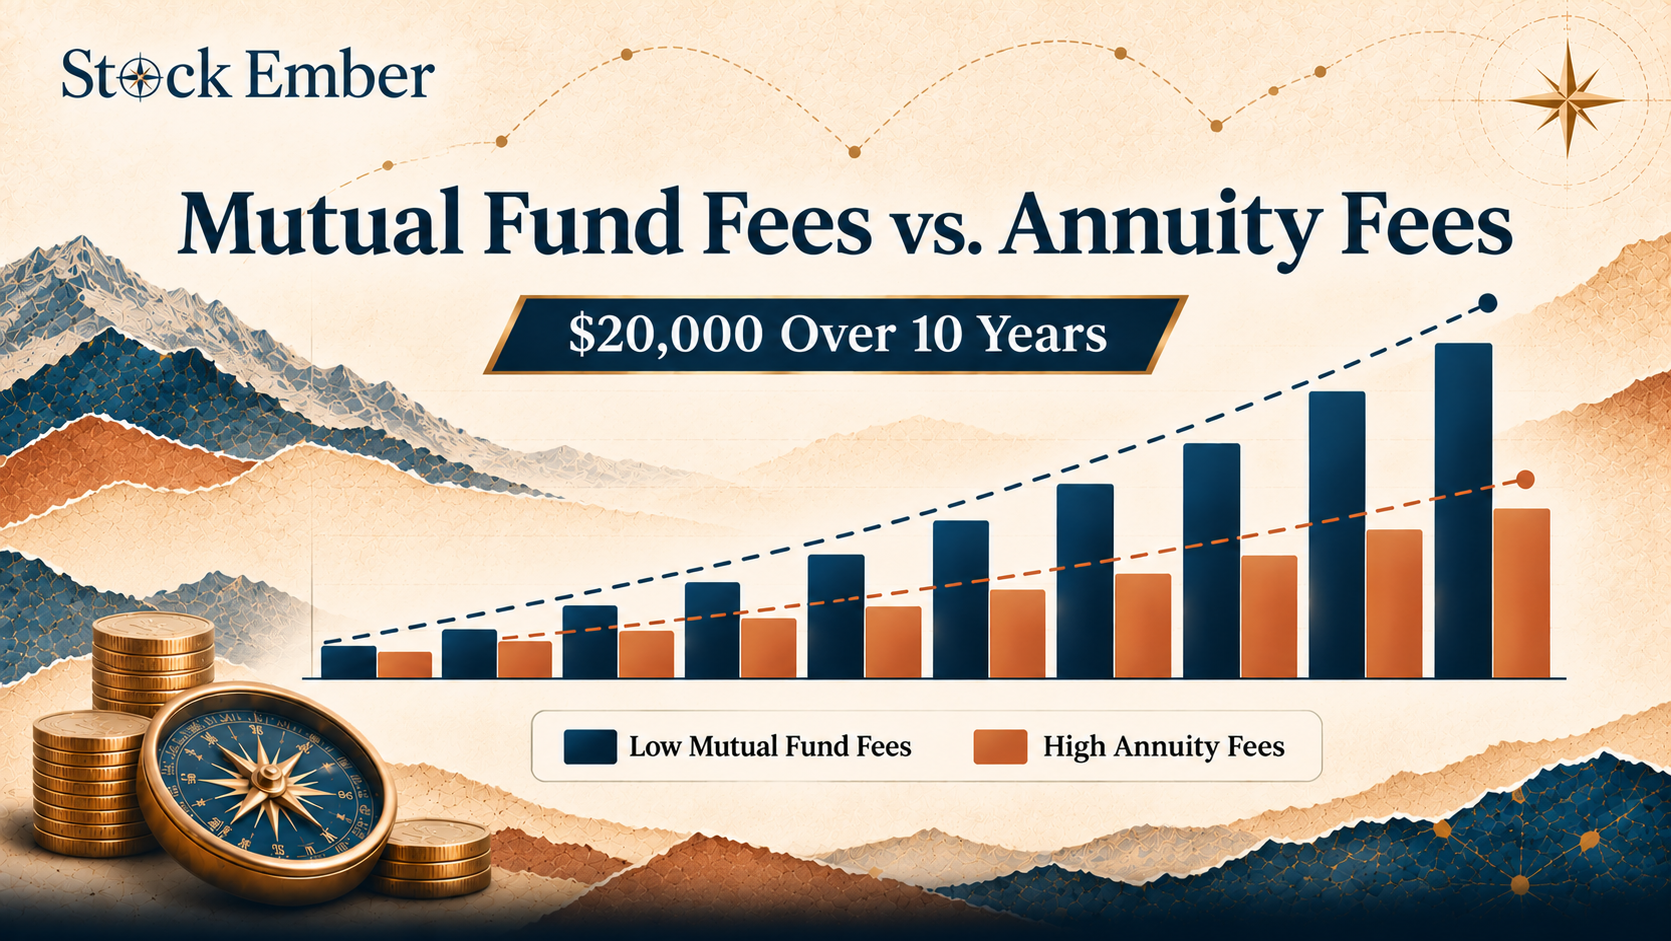
Bar chart showing how higher annual annuity fees reduce a 403b balance over 10 years
Those annual fee gaps look small on paper, yet they compound against you over 10 years. Suppose you contribute $10,000 a year for a decade and your underlying investments earn a hypothetical 7% a year before fees. In a low-cost index mutual fund with a 0.10% expense ratio (the yearly fee a fund charges as a percentage of your balance), your account could grow to roughly $147,000, though this is a hypothetical example only — actual market returns are never guaranteed.
Inside a variable annuity charging 1.60% in combined insurance and fund fees, that same $100,000 of contributions could grow to roughly $135,000, leaving about $12,000 less in your pocket over 10 years, before accounting for surrender charges (penalties for moving money out of an insurance contract within a set number of years) — again, a hypothetical illustration, not a promised outcome.
In practice, many long-term investors find that checking a plan's approved vendor list for a mutual-fund-only custodial option, rather than signing up with the first salesperson in the staff lounge, makes the single biggest difference to what they keep over a decade.
Common Mistakes to Watch With a 403b
Opening a 403b is only half the job; leaving your money uninvested or pulling it out early can quietly undo years of tax-advantaged saving.
Leaving contributions in cash: First-time enrollees sometimes set up payroll deductions without picking investments, leaving their money in a low-yield default cash account where inflation erodes buying power. At the same time, stock and bond funds inside a 403(b) fluctuate with the market and can lose value over short stretches, so your mix should match a multi-year horizon. Spreading contributions across more than one fund inside your plan, rather than concentrating everything in a single option, can also help limit how much any one market move affects your balance.
Withdrawing money too early or too late: Pulling funds out before age 59½ generally triggers ordinary income tax plus a 10% IRS early withdrawal penalty unless a specific exception applies. Later in retirement, Traditional 403(b) balances are also subject to Required Minimum Distributions (RMDs), mandatory annual withdrawals the IRS requires once you reach age 73 (age 75 if you were born in 1960 or later).
Many savers who change schools or hospitals also forget that they can roll an old 403(b) into a new employer plan or an individual retirement account, leaving behind high-fee legacy contracts that quietly drain returns for years.
Conclusion
A 403b gives teachers, hospital staff, and other nonprofit workers a tax-advantaged way to build long-term retirement savings through automatic payroll deductions. Getting the most out of the account comes down to choosing between Traditional and Roth tax treatment, capturing any employer match, and avoiding high-fee insurance contracts that eat into your balance over 10 years.
When you are ready to compare accounts for investing outside your workplace plan, our broker reviews are a practical place to start. Investing always puts your money at risk and past returns never promise the future, so treat this guide as educational information rather than personal tax or financial advice.
FAQ
5 questions
Can you lose money in a 403(b)?
Yes, you can lose money in a 403(b) because it is a tax-advantaged account wrapper rather than a protected savings account. Your balance rises or falls with the stock and bond funds or variable annuities you choose inside the plan. Even fixed annuity options carry inflation risk if yields lag rising prices, and high annual fees can reduce net returns over time.
Can I contribute to both a 403(b) and a Roth IRA?
Yes, US tax rules allow you to contribute to both a workplace 403(b) and an individual Roth IRA in the same year, because each account has its own separate annual contribution limit. However, your ability to contribute directly to a Roth IRA still depends on your modified adjusted gross income (MAGI, your gross income adjusted for certain deductions) and tax filing status under IRS rules.
What happens to a 403(b) when you leave your job?
When you leave an eligible employer, the money you contributed and any vested employer contributions remain yours. You typically have 4 options: leave the balance in your former employer's plan if allowed, roll it into a new employer's retirement plan, roll it into an individual retirement account, or cash it out, which usually triggers income taxes and potential early withdrawal penalties.
Are 403(b) contributions tax-deductible?
Traditional 403(b) contributions are not claimed as an itemized deduction on your tax return; instead, your employer deducts them from your paycheck before federal income taxes are calculated, lowering your reported taxable wages for the year. Roth 403(b) contributions are made with after-tax dollars, so they do not reduce your taxable income today.
Can a private-company employee open a 403(b)?
No, individuals cannot open a 403(b) on their own, and private for-profit businesses cannot sponsor one. Only public schools, colleges, and universities, tax-exempt 501(c)(3) nonprofits, and qualifying religious organizations can offer a 403(b) plan. If you work for a private company, your workplace equivalent is typically a 401(k), or you can open an individual IRA independently.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.