Under IRS early distribution rules, leaving your job during or after the calendar year you turn 55 lets you take penalty-free withdrawals from that employer's 401(k) or 403(b) before age 59½. The exception waives only the 10% early withdrawal penalty—ordinary income taxes still apply to pre-tax distributions, and individual retirement accounts (IRAs) are excluded.
The rule of 55 is a US tax rule that waives the 10% early withdrawal penalty on your current employer's 401(k) or 403(b). It applies if you leave your job in or after the calendar year you turn 55.
Leaving work in your mid-fifties, by choice or after a layoff, often creates an income gap before retirement accounts open at age 59½. Tapping a workplace plan early can bridge that gap, yet every dollar withdrawn loses years of tax-deferred growth.
This guide covers how the rule works, which accounts qualify, the taxes that still apply, and the 10-year cost of withdrawing early.
Quick Takeaways
01Waiving the 10% early withdrawal penalty does not erase regular income taxes on pre-tax withdrawals.
02Only the workplace plan at the employer you leave in or after the calendar year you turn 55 qualifies; traditional and Roth IRAs are excluded.
03Rolling a qualifying 401(k) into an IRA after leaving work permanently cancels the exception on those funds.
04Withdrawing money at 55 sacrifices at least 10 years of tax-deferred compounding and raises early-retirement market risk.
What Is the Rule of 55?
Under IRS early distribution rules, taking money from a qualified workplace retirement plan before age 59½ normally triggers a 10% additional tax on top of regular income taxes. Put simply, here is the rule of 55 explained: it is an IRS exception that waives that 10% penalty when you leave your job in or after the calendar year you turn 55. In practice, the rule of 55 meaning for savers is simple: earlier, penalty-free access to one specific workplace plan.
Two timing rules apply. First, eligibility follows the calendar year rather than your birthday: if you turn 55 in November, leaving your job in March of that year still qualifies. Second, qualified public safety workers, including police officers, firefighters, and air traffic controllers, qualify in the calendar year they turn 50 or after 25 years of service under the plan.
How the Rule of 55 Works (and Which Accounts Qualify)
The rule applies strictly to qualified workplace plans, such as a 401(k) or 403(b) held at the employer you leave in or after the year you turn 55. You must complete a separation from service (leaving your job through retirement, resignation, or layoff), so you cannot use this rule while still employed there. Taking another job later, however, does not cancel your eligibility.
Account-wrapper boundaries (the legal account type that holds your investments) are strict, and several accounts do not qualify:
Individual retirement accounts (IRAs): Neither a traditional IRA nor a Roth IRA qualifies, because IRAs are personal accounts rather than workplace plans.
Old 401(k) plans from past jobs: Balances at prior employers do not qualify unless your current plan accepts rollovers and you consolidated them before leaving.
Post-separation IRA rollovers: Completing a rollover (transferring retirement funds from one tax-advantaged account to another) from your qualifying 401(k) into an IRA removes the age-55 penalty exception.
Why Taxes and Plan Rules Still Bite
Penalty-free does not mean tax-free, because pre-tax withdrawals under the rule of 55 count as ordinary income (money taxed at your regular federal income tax bracket, rather than lower capital gains rates). When your plan pays a distribution directly to you, federal rules generally require 20% mandatory tax withholding up front, and state taxes may apply. On Roth 401(k) balances, a withdrawal that is not yet qualified (before age 59½ or before the 5-year holding period is met) is split proportionally between tax-free contributions and taxable earnings.
Employer plan rules can also limit payouts. While the IRS allows penalty-free withdrawals at 55, companies do not have to offer partial distributions. Check your Summary Plan Description (the official document that spells out your employer plan's rules) before resigning to see if your plan allows periodic payouts or forces a lump-sum distribution (taking your entire plan balance in a single payout), which can push you into a higher tax bracket.
In practice, many investors confirm partial-withdrawal rules with their plan administrator before setting a retirement date.
The 10-Year Compounding Cost of Tapping Your 401(k) at 55
Withdrawing money from a 401(k) at 55 carries a steep long-term cost because those dollars lose 10 or more years of tax-deferred compounding (growth without yearly taxes until withdrawal).
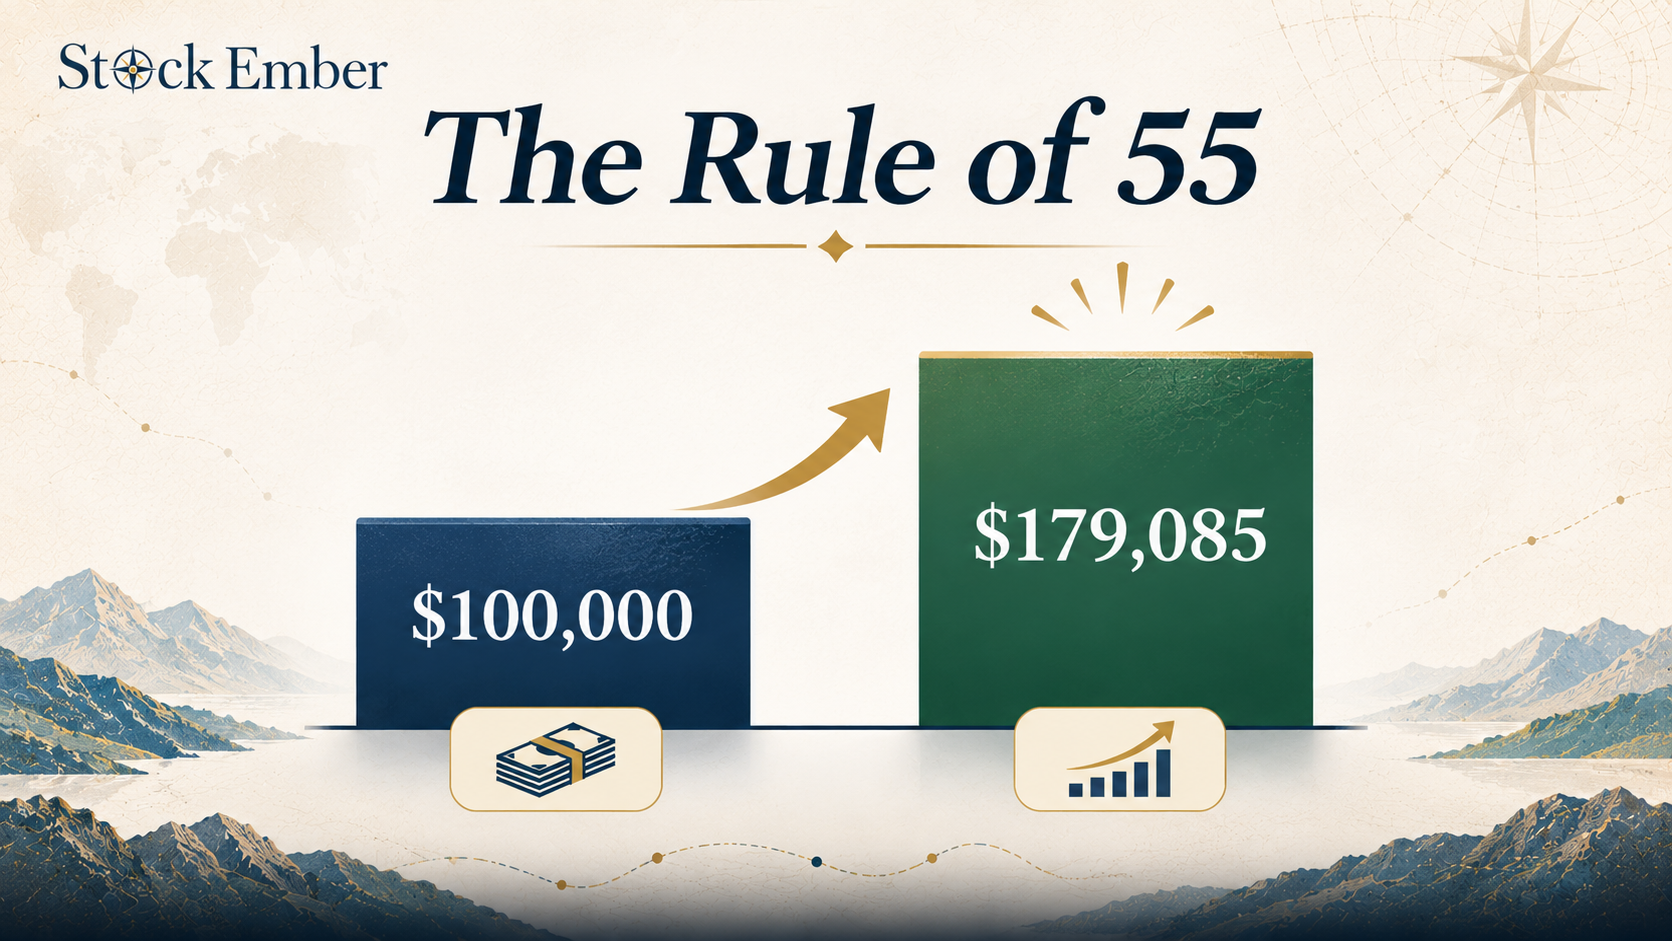
Bar chart comparing after-tax value of $100,000 withdrawn at 55 versus left invested for 10 years
Suppose you leave work at 55 and compare taking $100,000 from a pre-tax 401(k) now against leaving it invested at a hypothetical 6% annual return before taxes and inflation, assuming a 22% effective income tax rate:
Choice at Age 55
Value at Age 55
After-Tax Value at Age 65
Withdraw $100,000 now
$78,000 cash after 22% tax
$78,000 (assuming spent, $0 invested)
Leave $100,000 invested for 10 years
$100,000 invested
~$139,686 (~$179,085 before 22% tax)
In this hypothetical example, tapping the account at 55 leaves roughly $61,686 less in after-tax spending power 10 years later. Real market returns vary, meaning investment values can fall. Early withdrawals also heighten sequence-of-returns risk (the danger that poor market returns early in retirement permanently shrink a portfolio while you withdraw cash). Post-separation withdrawals also differ from a 401(k) loan, which lets you borrow while employed but typically demands fast repayment when you leave.
Common Mistakes to Watch With the Rule of 55
Most rule of 55 errors happen when investors move accounts or resign without checking plan rules:
Rolling the 401(k) into an IRA too soon: Moving funds into an IRA expands investment choices, yet it forfeits penalty-free access before age 59½.
Leaving a job in the calendar year you turn 54: Quitting even weeks before January 1 of the year you turn 55 locks you out of the exception for that plan, and turning 55 later does not fix it.
Withdrawing without a cash buffer: Selling stock funds during a drop locks in losses. Many buy-and-hold investors keep 1–2 years of living expenses in cash outside equities so they are not forced to sell in a downturn.
Conclusion
The rule of 55 lets you bridge an early-retirement income gap from your current workplace 401(k) or 403(b) without paying the 10% early withdrawal penalty. Even so, regular income taxes, employer payout limits, and 10 years of lost compounding make it a costly option unless you weigh your wider savings first.
When comparing where to hold your long-term retirement and taxable accounts alongside a workplace plan, our broker reviews are a practical place to start. Investing always puts your capital at risk and future market returns are never guaranteed, so treat this guide as educational background for your own research rather than personal financial or tax advice.
FAQ
5 questions
Does the rule of 55 apply to a traditional IRA or Roth IRA?
No. The rule of 55 applies only to qualified employer-sponsored workplace plans, such as a 401(k) or 403(b), held at the company you leave in or after the calendar year you turn 55. Traditional IRAs and Roth IRAs are individual accounts rather than workplace plans, so withdrawals of taxable earnings from an IRA before age 59½ generally remain subject to the 10% early distribution penalty unless a separate IRS exception applies.
Can you still work another job after using the rule of 55?
Yes. Eligibility depends on separating from service with the specific employer sponsoring your qualifying 401(k) or 403(b) in or after the calendar year you turn 55. Once you leave that job through retirement, resignation, or layoff, taking a part-time role, consulting work, or a full-time position with a different company later does not cancel your ability to take penalty-free withdrawals from that former employer's plan.
Do you have to take a lump sum under the rule of 55, or can you make partial withdrawals?
That depends on your employer's plan rules rather than the IRS. While federal tax law waives the 10% penalty on qualifying withdrawals, companies are not required to allow periodic or partial distributions after you leave. Some workplace plans require former employees to take their entire balance as a single lump-sum payout, which can push your taxable income into a much higher federal bracket for that year.
What happens if you roll your 401(k) into an IRA after leaving your job at 55?
Rolling a qualifying 401(k) or 403(b) into an IRA permanently forfeits rule of 55 penalty-free access for the rolled-over money. Because IRAs are ineligible for the age-55 separation-from-service exception, any taxable withdrawals taken from that new IRA before you reach age 59½ will generally face the standard 10% early withdrawal penalty unless another IRS exception covers the distribution.
How does the rule of 55 apply to police officers, firefighters, and public safety workers?
Qualified public safety employees, including state and local police officers, firefighters, emergency medical technicians, and federal air traffic controllers, qualify for penalty-free workplace plan distributions earlier than age 55. Under IRS rules expanded by the SECURE 2.0 Act, eligible public safety workers (and qualifying private-sector firefighters) can take penalty-free withdrawals starting in the calendar year they turn 50 or after completing 25 years of service under the plan.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.