Risk tolerance is an investor's psychological willingness and emotional capacity to handle market volatility and portfolio drawdowns without panic selling. By aligning asset allocation with emotional boundaries, investors may be less likely to sell at market bottoms and can better preserve the potential for multi-decade compound growth.
Risk tolerance is an investor's psychological willingness and emotional capacity to endure market volatility and portfolio drawdowns without panic selling.
When market downturns hit, misjudging your emotional comfort level often triggers panic-driven exits at market bottoms, turning temporary paper losses into permanent capital destruction. Aligning your asset allocation with your true emotional boundaries is essential for sustaining long-term compound growth.
What is risk tolerance, and why does it matter so much for long-term investors? This guide explains how it works, how it differs from risk capacity, and how to maintain emotional discipline.
Quick Takeaways
01What is risk tolerance? It measures your psychological comfort with market declines and determines your ability to stay invested during downturns.
02Distinguishing between risk appetite, risk tolerance, and risk capacity prevents severe structural misalignments in your portfolio.
03Conservative, moderate, and aggressive profiles dictate how capital is divided between equities for growth and fixed income for stability.
04Aligning allocation with emotional boundaries can help protect multi-decade compounding from panic selling during cyclical market bottoms.
What Is Risk Tolerance?
So, what is risk tolerance in practical terms? It is the psychological boundary that determines how much market volatility and portfolio decline you can comfortably handle before feeling compelled to sell.
Unlike financial metrics that evaluate account balances or income, risk tolerance is an entirely emotional and behavioral construct. It reflects how you react when asset prices fall sharply. Every portfolio experiences temporary paper losses during market corrections, but an investor with high risk tolerance views those drops as normal market noise, whereas an investor with low risk tolerance experiences acute financial anxiety.
Understanding your personal threshold is not about proving bravery; it is about establishing a sustainable investment strategy. If an asset mix causes sleepless nights or constant account monitoring during market dips, the portfolio is improperly constructed for your psychological profile.
Risk Appetite vs. Risk Tolerance vs. Risk Capacity
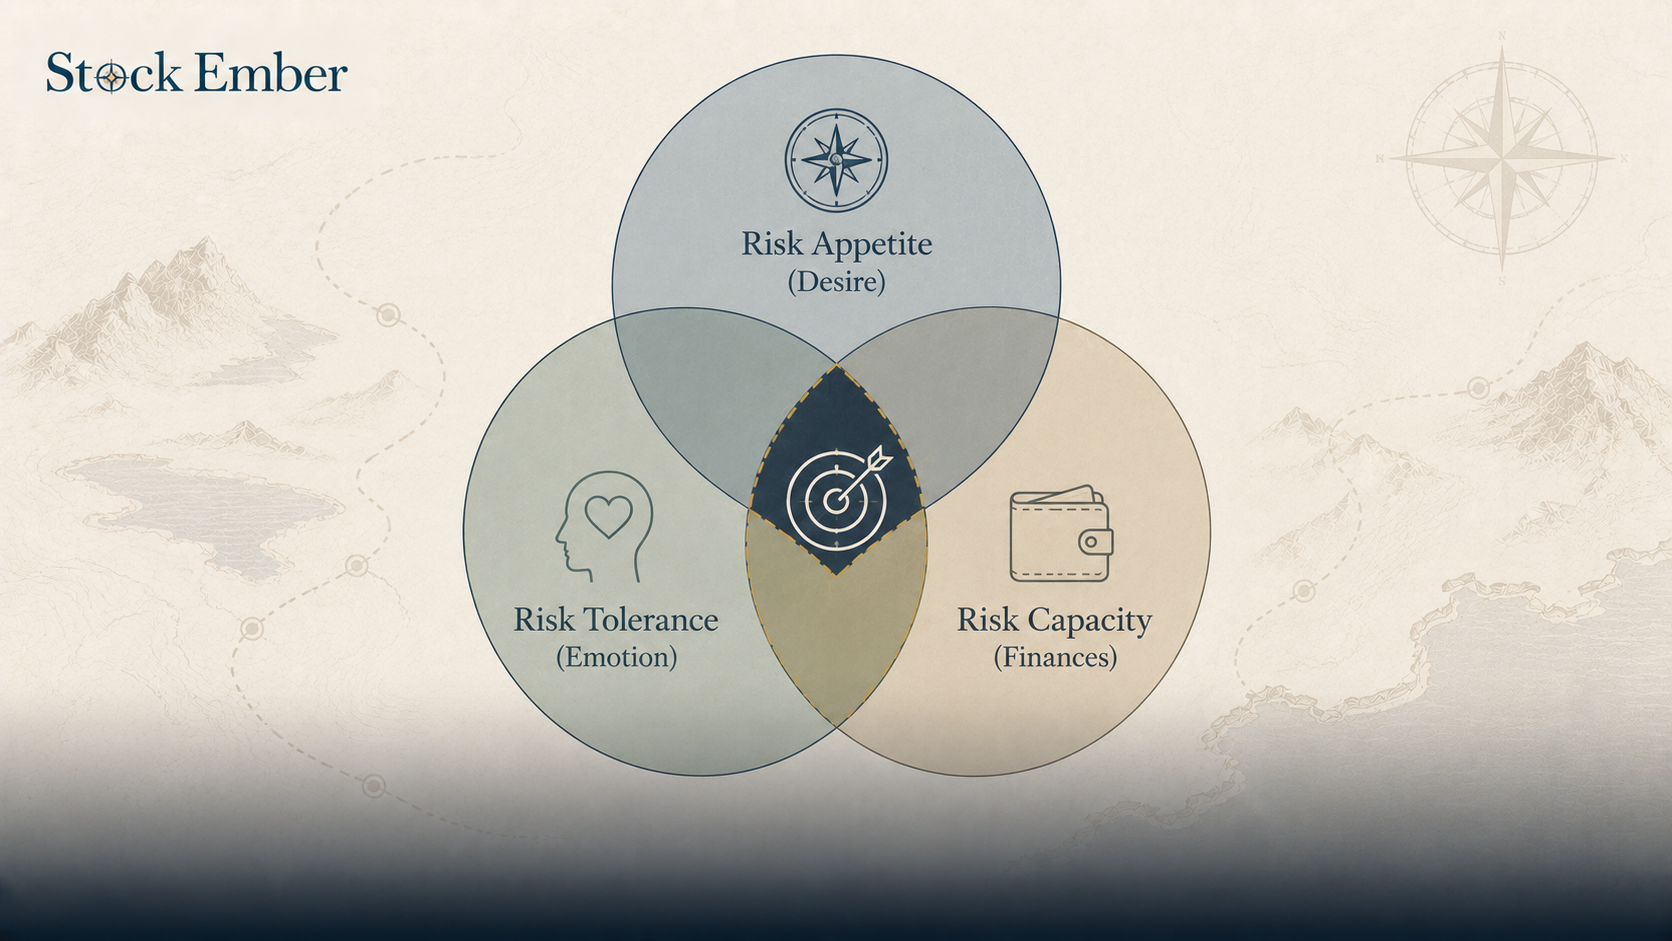
Understanding the distinction between risk appetite vs risk tolerance and risk capacity is critical because mistaking financial capability for emotional comfort is a common source of costly investment mistakes.
Although these three concepts sound similar, they govern completely different aspects of portfolio construction:
Risk Appetite: The level of investment risk you are willing to take in pursuit of higher anticipated returns. This represents your financial ambition.
Risk Tolerance: The level of market volatility you can emotionally stomach without panicking. This represents your psychological comfort zone.
Risk Capacity: The amount of financial loss your balance sheet can actually absorb without altering your lifestyle or financial goals. This is determined by your time horizon, cash reserves, and income stability.
Venn diagram showing the relationship between risk appetite, risk tolerance, and risk capacity.
Concept
Definition
Core Focus
Primary Constraint
Risk Appetite
Desire for wealth growth
Return expectations
Financial ambition
Risk Tolerance
Psychological comfort with drawdowns
Emotional endurance
Panic threshold
Risk Capacity
Financial ability to sustain losses
Balance sheet strength
Time horizon & cash flow
A major risk mismatch occurs when an investor has high risk appetite and high risk capacity, but low risk tolerance. For example, a young professional with a 30-year horizon (high capacity) might build a 100% stock portfolio to pursue aggressive growth (high appetite). However, if their true emotional risk tolerance is low, a 30% market contraction will likely trigger panic selling, completely overriding their financial capacity.
The Three Primary Risk Tolerance Profiles
The three primary risk tolerance profiles, conservative, moderate, and aggressive, define how an investor balances asset growth against downside volatility.
Your profile determines your foundational asset allocation split between equities (which drive long-term capital growth) and fixed income (which provides capital preservation and income):
Conservative Profile: Prioritizes capital preservation over high returns. Conservative investors typically hold a higher allocation in bonds and cash reserves (e.g., 30% stocks / 70% bonds) to minimize short-term paper losses, accepting lower long-term growth in exchange for portfolio stability.
Moderate Profile: Seeks a balance between growth and downside protection. Moderate investors often adopt a traditional balanced allocation (e.g., 60% stocks / 40% bonds), absorbing moderate drawdowns during market corrections while participating in long-term equity growth.
Aggressive Profile: Focuses on long-term wealth accumulation and is willing to endure severe market swings. Aggressive investors maintain equity-heavy allocations (e.g., 80% to 100% stocks) and must be prepared for peak-to-trough drawdowns that can reach 30% to 50%, or more, during major economic downturns.
Alignment with Long-Term Passive Strategy
Aligning your portfolio with your true risk tolerance is what makes a long-term passive strategy sustainable across full market cycles.
However, if your asset mix exceeds your emotional tolerance, you may be far more likely to abandon your index funds during a market crash, which can turn temporary paper losses into permanent ones.
Consider the impact of panic selling over a 10-year period:
Disciplined Investor (Matched Allocation): Holds a 70/30 portfolio through a major downturn. A $10,000 investment experiencing a temporary 20% drawdown recovers and continues compounding at an illustrative 7.0% annual rate, reaching approximately $19,671 after 10 years.
Panic-Driven Investor (Misaligned Allocation): Holds a 100% equity mix, panics during a 35% crash, sells to cash, and waits two years to re-enter. By missing the initial recovery rally, their $10,000 investment yields under $13,500 over the same 10-year period.
Both scenarios are hypothetical illustrations based on simplified assumptions, not predictions or guaranteed results. Actual returns vary, and all investments carry the risk of losing principal.
Constructing a portfolio that respects your true risk tolerance can make it easier to stay invested during severe market downturns, giving compound growth a better chance to work over decades.
Common Pitfalls in Assessing Your Risk Tolerance
Common pitfalls when assessing risk tolerance include overestimating emotional fortitude during bull markets, confusing paper volatility with permanent loss, and neglecting allocation adjustments as financial timelines shorten.
Avoiding these three traps helps maintain long-term investment discipline:
Relying Solely on Bull-Market Questionnaires
Most risk assessment surveys ask hypothetical questions like, "How would you react if your portfolio fell 20%?" During a prolonged bull market, almost every investor overestimates their risk tolerance because paper losses feel theoretical.
In real market crashes, loss aversion tends to take over. Research by Nobel laureate Daniel Kahneman and Amos Tversky on prospect theory suggests that losses are felt roughly twice as strongly as equivalent gains. Evaluating your risk tolerance requires reflecting on how you actually reacted during real market crashes rather than relying on calm-weather surveys.
Confusing Market Volatility with Permanent Loss
Temporary price fluctuations are a natural feature of liquid stock markets, not a permanent destruction of capital. Investors with low risk tolerance often mistake normal paper drawdowns for actual financial ruin, prompting them to sell solid index holdings at depressed prices. Recognizing that market drops represent temporary unrealized losses helps prevent panic-driven exits.
Failing to Adjust Risk Alignment Over Time
Risk tolerance and financial capacity are not static. As you age or approach major financial milestones, your capacity to absorb long market recovery periods decreases even if your emotional willingness to take risk remains high.
Failing to shift gradually toward a more conservative baseline mix as retirement approaches exposes your capital to sequence-of-returns risk. This is the risk that a major market decline hits just before or early in retirement, when you may need to sell investments at depressed prices.
In practice, many long-term investors discover that their true risk tolerance is significantly lower than they assumed during their first bull market. Accepting a slightly lower equity allocation that allows you to sleep peacefully through a market crash is far better than holding an aggressive 100% stock portfolio that forces you to panic sell at the bottom.
Conclusion
Ultimately, what is risk tolerance? It is the psychological anchor that holds your investment plan together during turbulent markets. By clearly distinguishing between emotional willingness, risk appetite, and financial capacity, you can design an asset allocation that reflects your true boundaries. Pairing a realistic risk profile with low-cost passive index funds can help market volatility feel like a routine phase of long-term investing rather than a source of financial distress.
When you are ready to explore broad-market index funds that fit your personal risk profile, reviewing our ETF reviews is a practical next step.
FAQ
5 questions
What is the main difference between risk tolerance and risk capacity?
Risk tolerance is an emotional construct measuring psychological comfort with portfolio drawdowns. Risk capacity is a financial construct measuring how much monetary loss your balance sheet can absorb without impacting your lifestyle or goals based on your time horizon and liquidity.
What is the difference between risk appetite and risk tolerance?
Risk appetite reflects your financial ambition and desire for higher potential returns. Risk tolerance represents your emotional comfort zone and the maximum market drawdown you can endure without panicking or panic-selling your holdings.
How do you determine your true risk tolerance?
True risk tolerance is best evaluated by examining your real behavior during actual market downturns rather than relying solely on calm-weather questionnaires. Psychological loss aversion often makes paper losses feel far more painful in practice than in hypothetical surveys.
Does risk tolerance change over time?
While emotional personality traits stay relatively steady, your acceptable risk allocation should adjust as your investment horizon shortens. Approaching retirement or financial milestones reduces your risk capacity, requiring a shift toward more conservative baseline assets.
How does risk tolerance affect asset allocation in passive indexing?
Risk tolerance dictates the split between growth assets (stocks) and stability assets (bonds). A well-aligned allocation can reduce the urge to panic sell during market corrections, making it easier to stay invested long enough to benefit from broad-market growth.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.