An annuity is a long-term insurance contract structured to provide predictable periodic income during retirement in return for an initial lump sum or recurring contributions. The account balance grows on a tax-deferred basis until distributions begin, with future payments backed entirely by the financial stability and claims-paying ability of the issuing life insurance company. While an annuity helps manage the risk of outliving your capital, it typically incurs higher recurring management fees and stricter multi-year surrender penalties than standard brokerage investments.
An annuity is a long-term contract with an insurance company where you pay money upfront or in stages in exchange for regular income payments later in life.
The fear of outliving your savings is common, and an annuity promises to turn a nest egg into a steady paycheck. Yet peace of mind comes with serious trade-offs, from steep annual fees to strict lockup periods. This guide covers how annuities work, what they cost over ten years, and how to tell if one fits your retirement plan.
Quick Takeaways
01An annuity is an insurance contract that converts savings into scheduled retirement payouts.
02Income payments depend entirely on the claims-paying ability of the issuing insurer, not government deposit insurance.
03High recurring fees, which can commonly range from about 2.0% to 3.5% each year depending on the contract, create a heavy drag on your returns over ten years.
04Withdrawing money during the surrender period triggers steep penalty fees and potential tax penalties.
05Tax-advantaged retirement accounts usually offer lower costs and greater flexibility for long-term wealth building.
What Is an Annuity?
An annuity is a legal agreement between an investor and an insurance company designed to provide a predictable stream of income during retirement.
The true annuity meaning centers on risk transfer rather than pure investment growth. Instead of managing market swings on your own, you pay an insurer to take on your longevity risk, the chance that you outlive your money. According to the U.S. SEC, an annuity is an insurance contract designed to help protect against the risk of outliving your assets.
Unlike savings deposits protected by the Federal Deposit Insurance Corporation (FDIC), an annuity carries no federal safety net. Your future payouts rely entirely on the financial strength and claims-paying ability of the issuing insurance company. If that insurer fails, your income stream is at risk. For a long-term investor, buying an annuity is not the same as buying stocks or funds; it is buying a private contract backed by a commercial firm.
How an Annuity Works
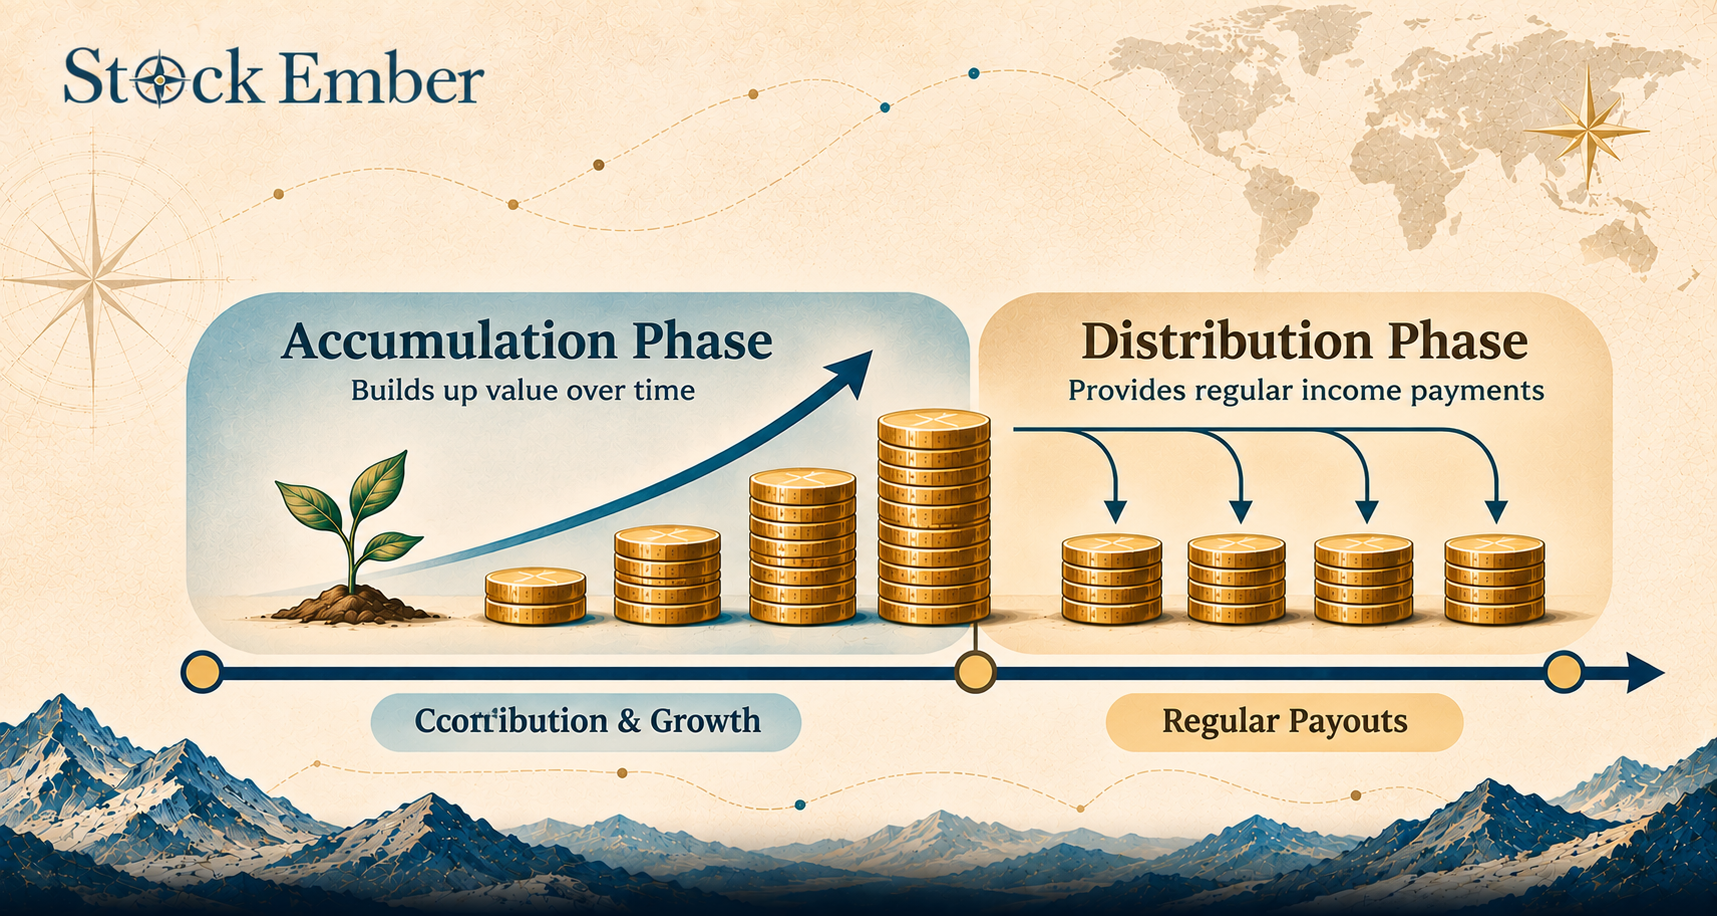
An annuity works through two distinct phases: an accumulation phase where your money builds, followed by a distribution phase where you receive payouts.
Having an annuity explained plainly means looking at how your dollars move through these stages. During the accumulation phase, you fund the contract with a single lump sum or regular payments. Your balance grows on a tax-deferred basis, meaning you pay no taxes on earnings until you take money out.
When you enter the distribution phase, you can choose to annuitize the contract, the formal process of permanently converting your account balance into a series of periodic payments. These payments can last for a set period, such as twenty years, or continue for the rest of your life.
The timing of these payments divides contracts into two broad setups:
Immediate annuities: You pay a lump sum, and income payments start almost right away, usually within one to twelve months.
Deferred annuities: Your money stays invested to grow for years or decades before any income distributions begin.
In practice, many long-term investors find that giving up control through annuitization feels far more binding than they expected. Once you irrevocably convert your balance into monthly checks, you usually cannot change your mind or get your principal back if unexpected life events arise.
Diagram illustrating the accumulation phase and distribution phase of an annuity contract
The Three Main Types of Annuities
Annuity contracts earn returns in three primary ways: fixed interest rates, variable market investments, or index-linked formulas.
Each structure splits market opportunity and downside risk differently:
Contract Type
How It Grows
Downside Protection
Fixed Annuity
Pays a set interest rate declared by the insurer for a specified term
High; principal is protected from market drops by the insurer
Variable Annuity
Invests in underlying sub-accounts holding stocks and bonds
None; your contract value moves up and down directly with the market
Indexed Annuity
Tracks an index like the S&P 500, subject to return caps and participation rates
Moderate; offers a minimum floor (often 0%) to prevent nominal market losses
Fixed contracts behave much like multi-year certificates of deposit, offering steady but modest returns that can fall behind inflation over long stretches. Variable contracts let you pursue market growth through underlying sub-accounts that hold stocks and bonds, but your balance can drop sharply in a market downturn.
Indexed contracts sit in the middle. They promise that you will not lose nominal principal during down years, but in exchange, the insurer caps your gains during bull markets. If the market gains 20% and your contract cap is 6%, you collect only 6%.
The 10-Year Cost and Tax Drag
Annuities carry layered annual fees that compound over time, quietly reducing the total wealth your portfolio builds.
While a plain index fund might cost 0.05% per year, a variable annuity typically charges roughly 2.0% to 3.5% annually based on common industry fee structures, or more with optional riders, across several distinct layers:
Mortality and expense (M&E) risk charges: Typically 1.10% to 1.40% annually to cover the insurer's insurance promises.
Administrative fees: Often around 0.15%, or a flat annual fee, for recordkeeping and paperwork.
Underlying investment management fees: Roughly 0.60% to 1.00% for the sub-account portfolio managers.
Optional riders: Additional charges (often 0.50% to 1.50%) for promised income floors or enhanced death benefits (a payout to your beneficiaries if you die before payouts end).
Consider the 10-year cost math on a $100,000 balance. If an unencumbered portfolio grows at an illustrative 7% per year, it grows to roughly $196,700 in ten years. But inside a variable contract burdened by a 2.5% combined annual fee, your net return drops to 4.5% per year.
After ten years, that same $100,000 reaches only around $155,300. The layered fees quietly cost you over $41,400 in lost compounding over a single decade.
Taxes present another drawback. While your money compounds tax-deferred, withdrawals of earnings from a non-qualified annuity (funded with after-tax money) are taxed as ordinary income at rates up to 37% under current U.S. federal tax brackets (as of the 2026 tax year), rather than at lower long-term capital gains rates (0% to 20%). In addition, withdrawing earnings before age 59½ generally incurs a 10% penalty tax from the Internal Revenue Service (IRS).
These figures are a hypothetical illustration for comparison purposes only; actual returns, fees, and account growth will vary and are not guaranteed.
Surrender Charges and Liquidity Traps
A surrender charge is a penalty fee imposed by the insurer if you withdraw more than a permitted amount, often 10% of your contract value per year, during the initial years of the contract.
These charges help the insurer recover the upfront sales commissions paid to brokers. Schedules vary significantly by issuer, but a commonly cited example starts around 7% in year one and declines by one percentage point each year, phasing out after about six to eight years. Always confirm the exact schedule in your contract's prospectus:
Contract Year
Surrender Penalty
Year 1
7%
Year 2
6%
Year 3
5%
Year 4
4%
Year 5
3%
Year 6
2%
Year 7
1%
Year 8+
0%
Pulling out $30,000 in year two for an urgent medical bill could trigger a surrender charge of up to $1,800 (6% of $30,000), depending on the contract’s free-withdrawal allowance, on top of any regular income taxes and early withdrawal penalties. A steep surrender schedule can lock up your capital, turning an annuity into a relatively illiquid asset that leaves little room for changing circumstances.
Annuities vs Other Retirement Accounts
Annuities serve as private insurance contracts to manage longevity risk, whereas dedicated retirement accounts serve as direct investment vehicles designed for flexible wealth accumulation.
Before tying up money in a high-cost insurance wrapper, most savers prioritize standard tax-advantaged accounts. Funding a Roth IRA allows your investments to compound tax-free and provides completely tax-free withdrawals in retirement without layered insurance charges.
When weighing an annuity vs a 401(k), standard workplace plans hold clear advantages for workers building wealth. A 401(k) provides upfront tax deductions or Roth options, potential employer matching contributions, and access to low-cost index funds without multi-year surrender penalties. For most people, an annuity only makes sense as a supplemental income floor after employer-sponsored plans and personal retirement accounts are already fully funded.
Conclusion
An annuity trades liquidity and investment growth for contractual income certainty. While a fixed payout can provide peace of mind in retirement, the trade-offs are significant: ongoing annual fee drag, steep surrender charges, and ordinary income tax rates on gains. Before committing large sums of savings to an insurance contract, review your existing income sources and explore low-cost, flexible options first.
When you want to evaluate platforms for building and managing a low-cost retirement portfolio, our Broker reviews can help you compare available account features.
Every investment vehicle involves financial risk, and insurance-backed payouts depend entirely on the ongoing solvency of the issuing company. Use this guide as a foundation for your own research, not as personalized financial advice.
FAQ
5 questions
Can you lose money in an annuity?
Yes, you can lose money in an annuity depending on the contract type and timing. With a variable annuity, your balance drops if the underlying market sub-accounts decline. With any annuity, canceling early can trigger heavy surrender charges and tax penalties. Additionally, if the issuing insurance company faces financial insolvency, your payments could be delayed or reduced beyond state guaranty association limits.
What happens to an annuity when you die?
What happens upon your death depends on the payout option chosen in your contract. Under a straight lifetime annuity, payouts cease immediately, and the insurer retains any remaining balance. If you select a joint-and-survivor option, a period-certain term, or pay for a death benefit rider, your named beneficiaries will continue receiving scheduled payments or collect the remaining contract value.
Is money in an annuity protected by the FDIC?
No, annuities are insurance products and carry no federal deposit insurance from the FDIC. Contract obligations are backed solely by the financial stability and claims-paying ability of the issuing life insurance carrier. If an insurer fails, state guaranty associations provide a safety net, but statutory coverage caps vary widely by state and may not fully cover large account balances.
Can you withdraw money from an annuity once payments begin?
Once you formally annuitize a contract into lifetime payments, the conversion is generally permanent and irrevocable. You cannot withdraw lump sums or alter payout amounts, even for emergencies. However, some modern deferred contracts offer living benefit riders that allow scheduled income withdrawals while letting you retain access to whatever cash value remains in the underlying account.
Can you transfer an annuity to another provider without paying taxes?
Yes, in the United States, you can exchange one annuity contract for another without triggering immediate taxes through an IRS Section 1035 exchange. This tax-free rollover allows you to transfer your accumulated cash value directly to a new contract with lower fees or better payout terms, though your existing contract may still impose its own surrender penalties.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.