Socially responsible investing (SRI) is an investment strategy that applies explicit moral, social, or environmental filters to select or exclude specific companies from a portfolio. It enables investors to align their capital allocation with personal values while pursuing long-term financial growth. Investors implement SRI primarily through screened index mutual funds and exchange-traded funds (ETFs).
Socially responsible investing is an investment strategy that applies specific moral, social, or environmental filters to stock and bond selection alongside traditional financial metrics.
When building a long-term portfolio, many individuals want their capital to reflect their personal ethics while still compounding wealth over decades. However, filtering out broad market sectors can alter portfolio risk and change overall index returns. This guide explains how values-based screening works, how it differs from corporate risk scoring, and what long-term investors should evaluate before selecting screened funds.
Quick Takeaways
01Socially responsible investing filters investments using rule-based ethical, moral, or environmental standards.
02Negative screening excludes industries like tobacco, weapons, and fossil fuels, while positive screening selects companies with high sustainability practices.
03SRI uses strict moral exclusion filters, whereas ESG integration evaluates environmental and governance factors as financial risk metrics.
04Removing entire economic sectors introduces tracking drag and sector concentration risk relative to broad market benchmarks.
05Higher expense ratios and index rebalancing turnover can reduce compound returns over a 10-year holding period.
What Is Socially Responsible Investing?
When asking what is socially responsible investing, the core concept centers on aligning capital allocation with personal values. The formal socially responsible investing definition refers to an investment approach where investors apply explicit moral, ethical, or social filters to choose or exclude specific securities.
In finance, SRI socially responsible investing dates back centuries to faith-based investment funds that avoided companies involved in gambling, alcohol, or weapons. Today, institutional and retail investors use these strategies to support environmental sustainability, human rights, and clean energy transition.
As noted by the SEC, funds that apply social or environmental criteria use different screening standards, meaning two funds labeled as socially responsible may hold very different underlying companies.
Types of Socially Responsible Investing: Negative vs. Positive Screening
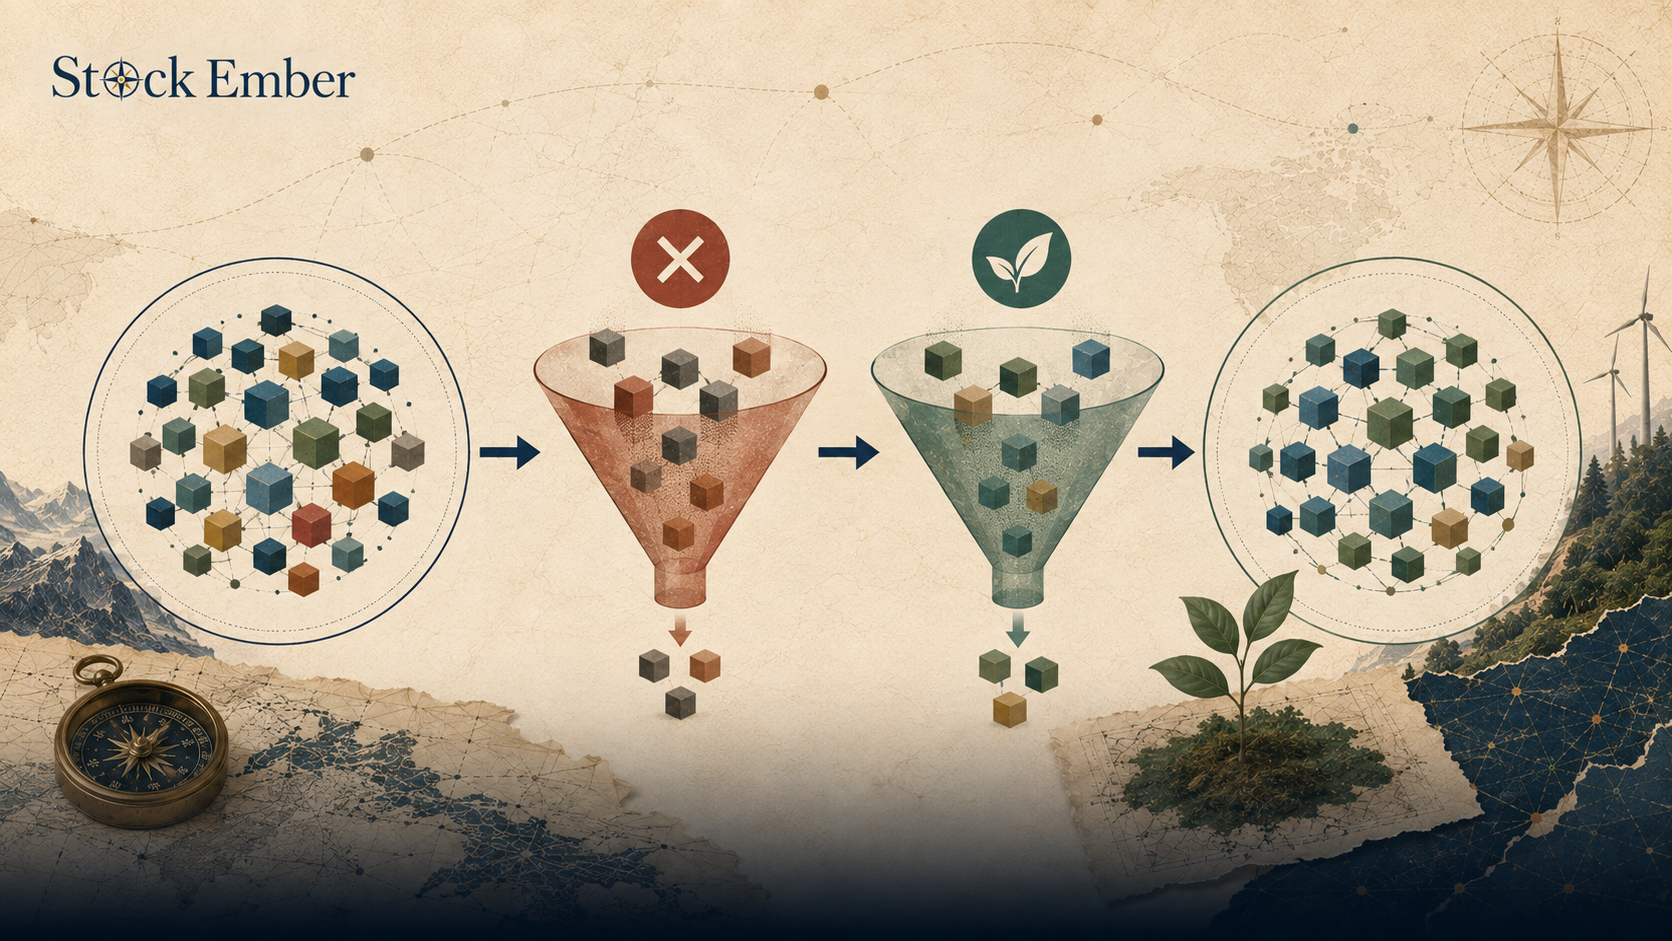
To understand the different types of socially responsible investing, investors must examine how fund managers filter broad equity markets. Index providers typically construct screened benchmarks using two primary methodologies:
Negative (Exclusionary) Screening: This method removes companies or entire industries that fail specific ethical tests. Common exclusions include manufacturers of military weapons, tobacco products, gambling operations, or coal extraction. Negative screening is the most common form of values-aligned filtering.
Positive (Inclusionary) Screening: Rather than focusing solely on exclusions, positive screening actively selects companies that demonstrate strong performance in areas like renewable energy production, fair workforce standards, or corporate transparency.
Norms-Based Screening: Filters companies against international standards, such as United Nations guidelines on human rights, labor relations, and environmental protection.
Combining these approaches creates tailored index rulebooks, but each layer of filtering reduces the total pool of eligible companies.
Socially Responsible Investing Examples in Practice
Looking at socially responsible investing examples helps show how screened strategies operate in real portfolios.
In a negative screening model, a global equity benchmark might start with 1,500 large-cap stocks. Applying exclusionary filters removes defense contractors, fossil fuel producers, and commercial gambling operators, leaving roughly 1,000 eligible constituent stocks.
In a positive screening model, a fund might target clean energy technology. Instead of holding all industrial or utility companies, the fund allocates capital specifically toward solar panel manufacturers, wind turbine producers, and battery technology developers.
While these examples show clear value alignment, screening out certain companies or sectors changes how the portfolio behaves during different economic cycles.
Diagram showing how negative and positive ethical screens filter broad index stocks into an SRI fund.
SRI vs. ESG Integration: Understanding the Core Differences
Investors frequently mix up SRI and ESG, but they serve distinct purposes:
SRI (Moral and Ethical Filtering): SRI focuses on values. It uses clear rules to exclude or include companies based on moral standards, regardless of whether those exclusions boost short-term financial performance.
ESG Integration (Financial Risk Management): ESG integration evaluates environmental, social, and governance factors as material financial risks. An ESG-focused manager evaluates carbon exposure or board independence to assess downside business risk, not to enforce an ethical rulebook.
In short, SRI is driven by values, while ESG integration is driven by financial risk analysis. Understanding this difference helps investors choose products that match their actual goals.
How to Access SRI: Mutual Funds and ETFs
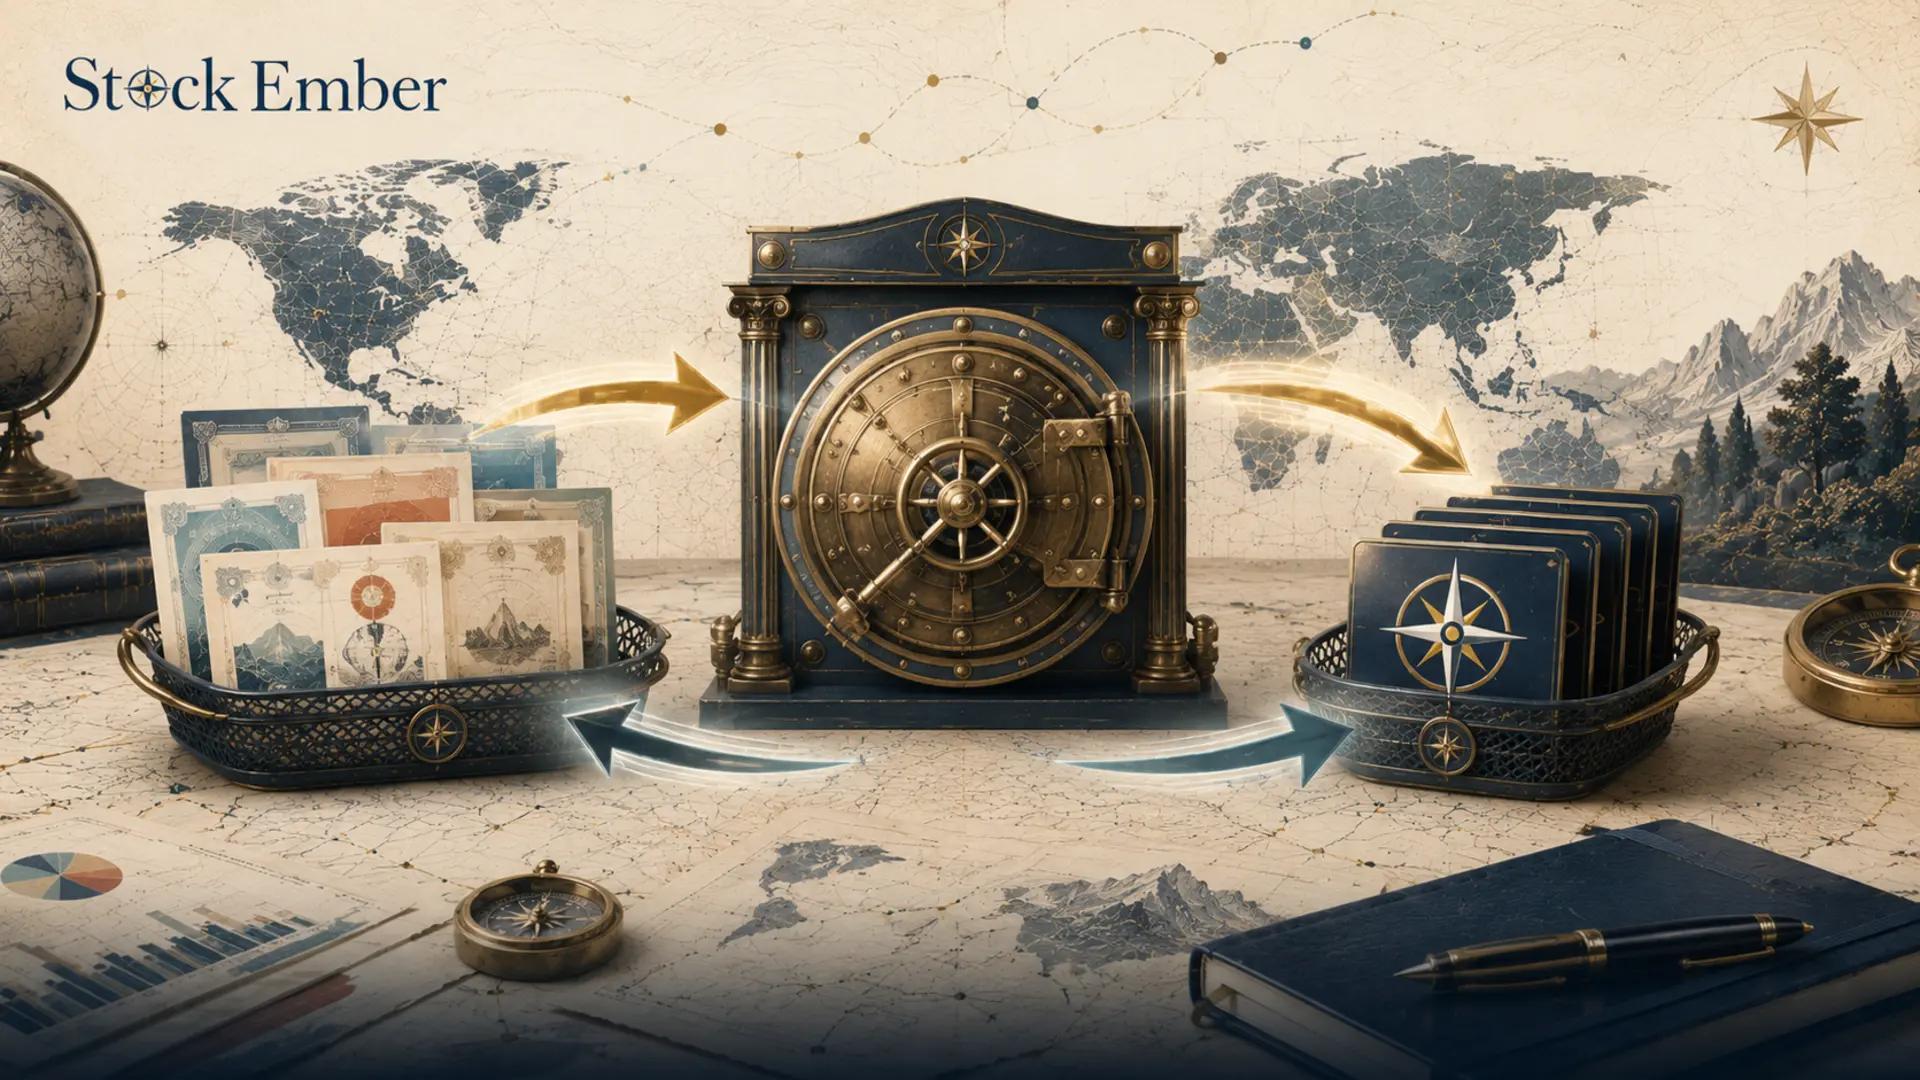
Retail investors rarely build screened portfolios by purchasing individual equities one by one. Instead, most access values-aligned strategies through pooled investment vehicles. Understanding what an ETF is helps explain how an ETF can track a screened benchmark by holding a pre-selected basket of equities.
When an ETF tracks an SRI index, the index provider takes a broad parent benchmark, applies rule-based screens, and weights the remaining companies by market value. Investors can then buy shares in the ETF through a standard brokerage account, gaining instant access to hundreds of screened companies in a single trade.
Benchmark Drag: Tracking Error and 10-Year Fee Impact
While values-based screening allows investors to avoid specific industries, it introduces financial friction. Over a multi-year holding period, higher management costs and tracking differences affect total wealth accumulation.
When an SRI index excludes companies or sectors based on screening criteria, its returns may diverge from broad market benchmarks. Furthermore, when companies become eligible or ineligible under screening criteria, frequent index rebalancing creates portfolio turnover and trading costs.
Consider a hypothetical $10,000 investment held over 10 years, assuming a broad market return of 7% per year:
Broad Market Index Fund (0.05% Fee): Delivers a net annual return of 6.95%, growing $10,000 to approximately $19,579 over 10 years.
Screened SRI ETF (0.35% Total Cost Friction): An SRI ETF charging a 0.25% expense ratio plus 0.10% in rebalancing drag yields a net return of 6.65% per year, ending at roughly $19,037.
These figures are hypothetical illustrations only. Actual fund returns are not guaranteed, and capital remains at risk.
That 0.30% annual difference in friction results in $542 less in cumulative growth over a decade. Long-term investors must decide if this cost trade-off matches their financial plan.
Portfolio Trade-Offs: Sector Concentration and Volatility Risks
Filtering equities by moral criteria introduces structural portfolio trade-offs that every investor should consider:
Sector Concentration Risk: Excluding entire industries like traditional energy, defense, or aerospace increases allocation weight in remaining sectors like technology and consumer goods. When tech stocks decline, screened funds can suffer steeper losses than broader market indices.
Missing Cyclical Rallies: During periods when excluded sectors such as oil and gas during supply shortages experience high profitability, screened portfolios will lag behind unscreened market benchmarks.
Greenwashing Risk: Some financial products market themselves as socially responsible despite holding companies with controversial supply chains or high carbon footprints.
In practice, many long-term investors find that strict negative screening requires periodic portfolio checks, as corporate mergers can inadvertently re-introduce excluded business activities.
Conclusion
Asking why socially responsible investing appeals to buy-and-hold investors comes down to personal priorities. SRI offers a structured, transparent way to build a portfolio that aligns with personal morals while participating in global equity growth.
However, ethical screening alters portfolio diversification, increases tracking drag relative to broad benchmarks, and often comes with slightly higher expense ratios. Long-horizon investors should carefully weigh these structural trade-offs to ensure their values-aligned strategy remains sustainable over decades of market ups and downs.
When you are ready to compare screened index funds and evaluate expense ratios, our ETF reviews offer clear breakdowns of tracking quality and cost structure.
All equity investments carry risk of capital loss and screening does not protect against market declines, so treat this educational guide as a starting point for your personal research.
FAQ
5 questions
What is socially responsible investing (SRI)?
Socially responsible investing is an investment approach that applies explicit moral, ethical, or social standards to select or exclude individual securities from a portfolio. Investors use SRI to align their personal values with their capital allocation, avoiding sectors like weapons, tobacco, or fossil fuels while supporting sustainable business practices.
What is the main difference between SRI and ESG investing?
SRI uses rule-based moral filters to include or exclude specific companies based on personal or ethical values, regardless of short-term financial performance. ESG integration, on the other hand, treats environmental, social, and governance metrics as material financial risk factors to assess corporate management quality and downside business risk.
What is negative screening in socially responsible investing?
Negative screening, or exclusionary screening, is a filtering method that removes entire industries or companies that fail specific ethical tests. Common exclusions in SRI portfolios include defense contractors, tobacco manufacturers, commercial gambling operators, weapons producers, and coal extraction companies.
Does socially responsible investing lower investment returns?
SRI screening does not automatically lower returns, but excluding entire economic sectors alters portfolio diversification and risk profiles. During market cycles where excluded sectors experience high profits, screened funds may lag broad market benchmarks. Additionally, higher fund expense ratios and index rebalancing turnover can create performance friction over long horizons.
How can beginners start socially responsible investing?
Beginner investors can start socially responsible investing by purchasing index-tracking mutual funds or exchange-traded funds (ETFs) that incorporate SRI screening filters. These pooled funds allow investors to hold a pre-screened, broadly diversified basket of ethical equities in a single trade through a standard brokerage account.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.