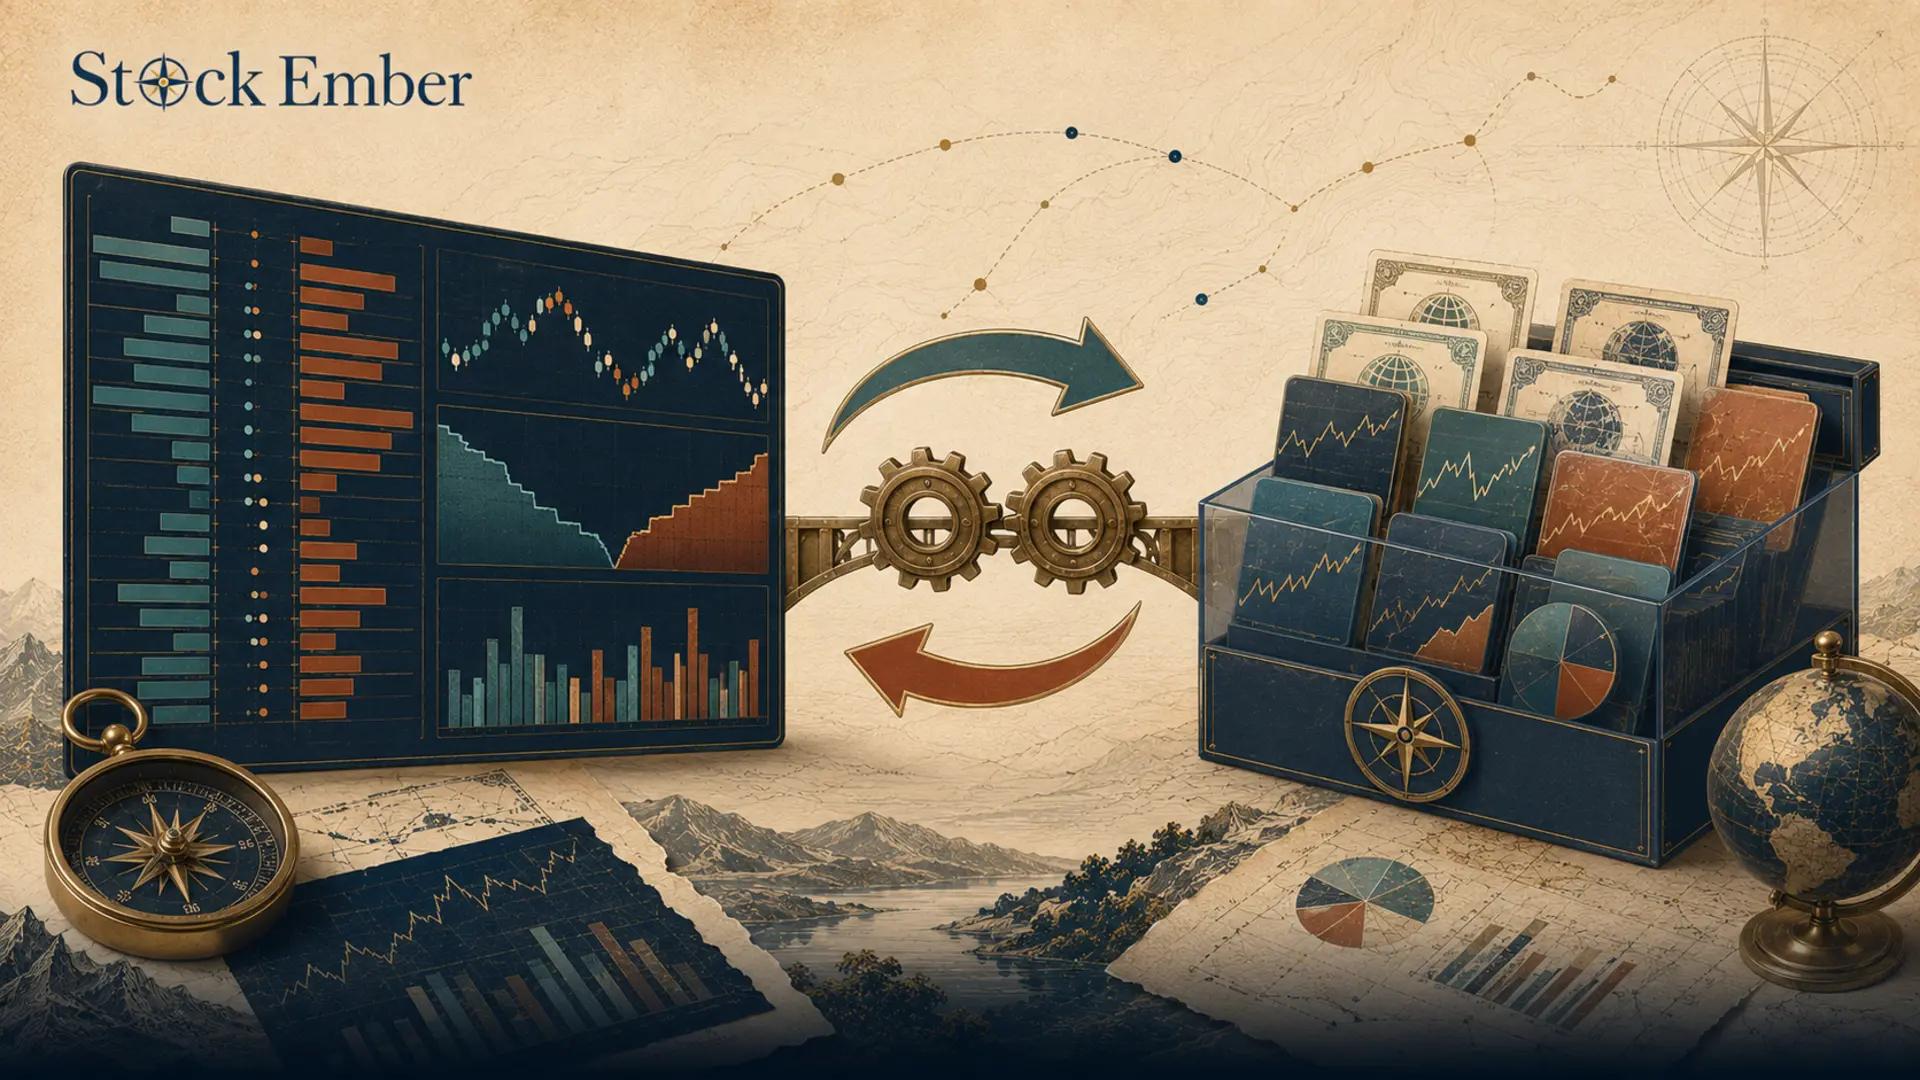
This backend mechanism is where institutional financial firms issue or destroy ETF shares to match market demand. This primary market process keeps trading prices aligned with underlying asset values.
When you buy ETF shares through a broker, you trade on the secondary market with other investors. Behind the scenes, specialized institutions handle large bulk transfers to ensure supply meets demand smoothly. This guide breaks down the creation and redemption engine, how in-kind transfers shield long-term investors from unnecessary taxes, and where the mechanism faces market stress.
What Is ETF Creation and Redemption?
This process is the mechanism through which specialized institutional financial institutions adjust the supply of ETF shares in the market.
Unlike traditional mutual funds, where investors buy directly from the fund company, exchange-traded funds trade continuously on secondary stock exchanges like ordinary equities. To ensure that supply matches buying and selling demand, fund issuers rely on a primary market structure.
In this primary market, only specific institutional firms known as Authorized Participants (APs)—typically investment banks or market makers—have the contractual right to create or redeem ETF shares directly with the fund manager.
Retail investors buy and sell existing shares on public stock exchanges without ever touching this backend mechanism.
The ETF Creation and Redemption Process Explained
This process relies on Authorized Participants assembling or returning large blocks of securities in exchange for fund shares.
The ETF creation process begins when demand for an ETF increases on stock exchanges. When market buying pressure threatens to push the share price above the fund's actual worth, the AP steps in.
The AP buys shares of the individual underlying stocks that make up the index on the open market. Once assembled into a standardized bundle called a creation unit—typically 25,000 to 100,000 shares—the AP delivers this asset basket to the ETF issuer. In exchange, the issuer delivers newly created ETF shares to the AP.
Conversely, the ETF redemption process occurs when selling pressure creates excess fund shares in the market. During an ETF redemption, the AP buys ETF shares on the open market until it accumulates a creation unit.
The AP returns these shares to the ETF issuer, which cancels the shares and returns the underlying portfolio assets back to the AP. The full ETF creation redemption process adjusts total fund shares dynamically to maintain balance.
The In-Kind Advantage: Tax Efficiency and Low Costs
An ETF in kind redemption swaps securities directly between the fund issuer and institutional players without selling underlying stocks for cash.
Most equity creations and redemptions occur as in-kind transfers. Instead of the fund manager selling underlying stocks inside the fund to raise cash when investors leave, the issuer simply transfers the basket of physical stocks directly to the AP.
For buy-and-hold investors, this structure provides a major tax advantage over ten years. In a conventional mutual fund, manager sell-offs generate taxable capital gains that are distributed to all fund shareholders at year-end—even shareholders who did not sell a single share. By avoiding forced internal stock sales through in-kind redemptions, ETFs shield long-term portfolios from these drag costs.
Over a 10-year holding period, avoiding annual capital gains tax distributions may help preserve more of your compounding returns on a modest portfolio — though actual savings vary by fund, tax bracket, and market conditions, and past performance is never a guarantee of future results. This structure applies across different fund formats, including multi-class structures where specific ETF share classes operate alongside traditional fund shares.
How Institutional Arbitrage Keeps ETF Prices Fair
The ETF creation redemption mechanism maintains fair pricing by enabling institutional arbitrage whenever market prices drift from underlying asset value.
An ETF has two prices: its market price (what buyers pay on an exchange) and its Net Asset Value (NAV), which represents the combined value of all underlying stocks divided by outstanding shares. When trading activity moves the market price away from NAV, arbitrage opportunities prompt APs to act immediately.
If high demand causes an ETF to trade at a premium (higher than its NAV), an AP buys the cheaper underlying stocks, creates new ETF shares, and sells them into the market at the higher price to lock in a profit. This selling pressure brings the ETF price back down toward fair value.
If an ETF trades at a discount (lower than its NAV), the AP buys cheap ETF shares, redeems them for underlying stocks, and sells the individual stocks for a profit.
Potential Risks and Market Stress Friction
Friction in creation and redemption mechanics usually surfaces during extreme market volatility or when underlying assets become illiquid.
While the creation and redemption engine works smoothly under normal market conditions, structural risks exist. Long-term investors should stay aware of specific stress points:
- AP Concentration Risk: A limited number of financial institutions act as APs for specialized funds. If several APs withdraw from market-making activities during a market panic, fund liquidity can shrink.
- Underlying Illiquidity: If an ETF holds illiquid assets—such as high-yield corporate bonds or emerging market equities—APs may struggle to buy or sell the underlying securities quickly, causing the bid-ask spread — the gap between the buying and selling price — to widen.
- Premium and Discount Spreads: During severe market dislocations, an ETF's market price may temporarily trade at a significant discount to NAV until market makers can safely price the underlying holdings.
Conclusion
Understanding this mechanism reveals why funds maintain market efficiency, low costs, and strong tax advantages for long-horizon investors.
The creation and redemption mechanism is the backend engine that aligns ETF market prices with real asset values while insulating fund holders from internal capital gains distributions. While retail investors trade on stock exchanges without interacting directly with creation units, institutional arbitrage safeguards portfolio efficiency daily.
When you are ready to evaluate individual funds and select options for your portfolio, our ETF reviews are the place to start. Investing always puts your capital at risk and market conditions can fluctuate, so treat structural insights as a foundation for your overall strategy rather than individual financial advice.