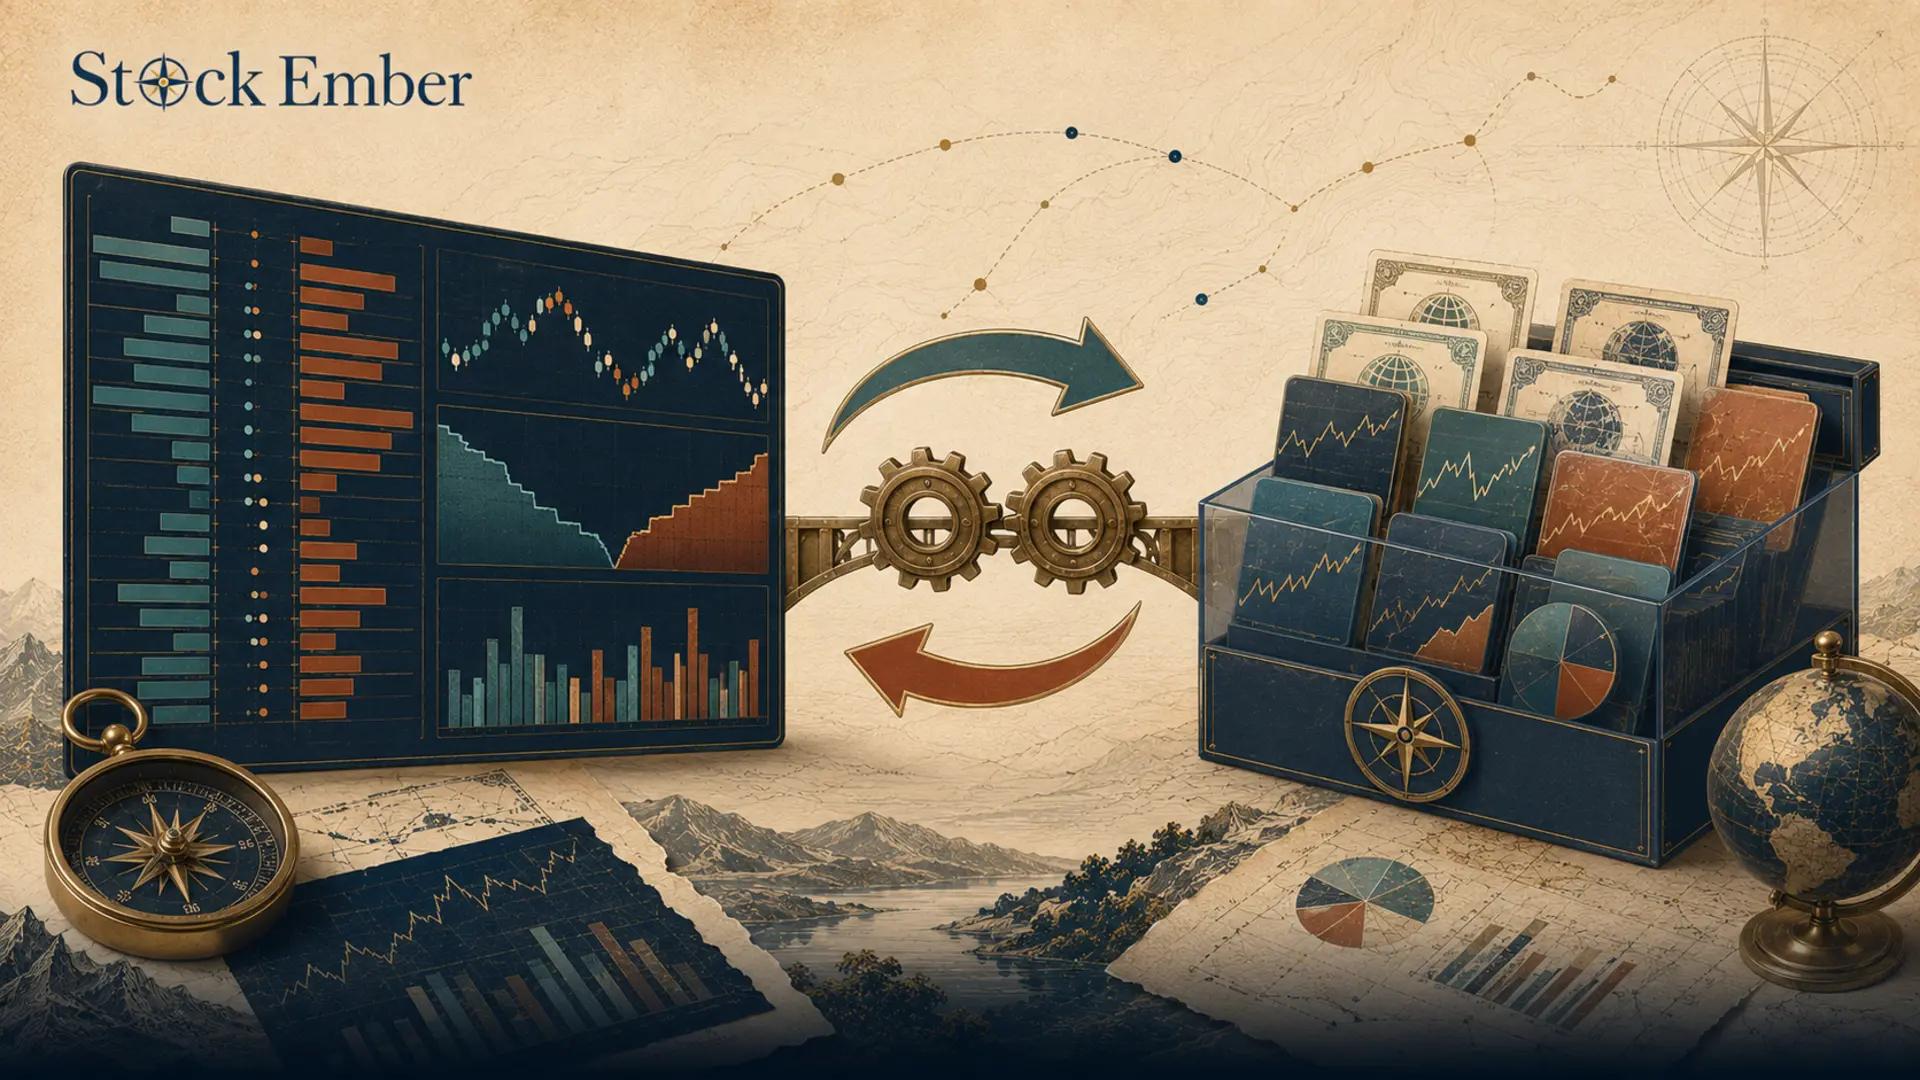
An ETF share class is a structural fund design where an exchange-traded fund operates as a distinct share class of a larger investment fund, sharing a single underlying asset pool with traditional mutual fund classes.
Investors often wonder whether buying this structure differs from owning a standalone fund or a traditional mutual fund class. While the pooled structure offers lower operating expenses through scale, it also introduces unique tax and cash considerations. This guide explains how exchange-traded share classes function, why Vanguard held a patent on this model, and what long-term investors must consider before investing.
What Is an ETF Share Class?
An ETF share class is a specific class of shares within a fund structure that trades on a public exchange like an ETF while drawing from a shared portfolio. In traditional investing, a single fund company creates distinct share classes for institutional investors, financial advisors, and retail buyers to offer different fee structures.
In the US market, an ETF share class usually refers to an exchange-traded class attached to an existing open-end mutual fund. In international markets, such as European UCITS (Undertakings for Collective Investment in Transferable Securities) funds, share classes refer to variations within a standalone fund—such as accumulating dividend classes, distributing classes, or currency-hedged lines. Both designs aim to pool capital into one asset base while serving different investor preference levels.
How the Multi-Share Class Structure Works
The multi-share class structure works by combining money from mutual fund buyers and exchange traders into a single asset pool. When you buy shares in an exchange-traded class, your money invests in the exact same underlying securities as an investor buying the traditional mutual fund version.
For example, a fund tracking the CRSP (Center for Research in Security Prices) US Total Market Index might issue traditional mutual fund shares alongside an exchange-traded class. Traditional mutual fund investors place orders directly with the fund manager at the end of the trading day.
Meanwhile, exchange-traded class investors buy and sell shares throughout the day on secondary stock exchanges using authorized participants (large financial institutions that create and redeem ETF shares directly with the fund). Because all assets remain in one combined pool, administrative costs are split across a much larger asset base.
Vanguard’s Patent Expiration and Industry Expansion
Vanguard patented the multi-share class ETF model in 2000, allowing the firm to add ETF share classes to its existing index mutual funds for over two decades. This exclusive arrangement gave Vanguard a structural edge in building fund scale while keeping expense ratios exceptionally low.
That patent expired in May 2023. Following the expiration, major asset management firms filed for exemptive relief with the SEC to build exchange-traded share classes for their legacy mutual funds. Regulators review these applications to ensure that multi-class structures treat both mutual fund and ETF investors fairly without transferring hidden operational costs between investor groups.
Key Advantages and Risks for Buy-and-Hold Investors
An ETF share class offers cost benefits alongside distinct operational risks over a 10-year holding period. Combining mutual fund capital with exchange-traded volume creates economies of scale. On a 10-year Total Cost of Ownership (TCO) calculation, a fund that lowers its expense ratio from 0.15% to 0.05% saves an investor roughly $1,000 for every $100,000 invested.
However, shared asset pools introduce specific risks:
- Capital Gains Tax Spillover: Standard ETFs shield investors from capital gains taxes using in-kind creation and redemption mechanisms (swapping securities instead of cash, which avoids triggering a taxable sale). In a shared pool, if traditional mutual fund investors pull out large sums of cash, fund managers may need to sell underlying stocks, creating realized capital gains that hit all share class holders.
- Cash Drag: Mutual fund share classes must keep cash on hand to handle daily investor redemptions. Holding cash inside the shared pool can slightly reduce performance during strong bull markets compared to pure standalone ETFs.
- Fee Disparities: While operational costs are shared, specific management fees can differ between share classes within the same fund.
Common Pitfalls to Avoid
Investors often make basic mistakes when evaluating funds that feature multiple share classes. The two most common errors include:
- Assuming Tax Parity Across Borders: US multi-share class funds face capital gains spillover rules, whereas European UCITS ETF share variants handle currency lines and dividend accumulation without mixing mutual fund cash flows.
- Ignoring Class-Specific Expense Ratios: Even within the same pooled fund, the exchange-traded class may carry a different expense ratio than an Admiral or Institutional mutual fund class. Always check the prospectus for the exact class net expense ratio.
Conclusion
This structure provides a flexible way to access pooled investment funds with lower operating costs driven by scale. While the model offers competitive expense ratios over long horizons, buy-and-hold investors should evaluate potential capital gains spillovers and cash drag relative to standalone fund options.
When you are ready to evaluate specific funds for your portfolio, our ETF reviews offer detailed breakdowns of fees and holdings. Investing always carries risk of loss and past fund performance does not guarantee future results, so use this guide as an educational foundation for your independent research.