Smart beta is an investment strategy that uses rule-based, non-market-cap weighting criteria such as value, momentum, quality, or low volatility—to build index portfolios. It combines the passive structure and transparency of index funds with factor selection rules traditionally used by active managers. Investors access smart beta primarily through factor-focused exchange-traded funds (ETFs).
Smart beta is a rule-based investing approach that weights index holdings using specific financial factors such as value, momentum, or dividend yield rather than market capitalization.
When building a portfolio, traditional index funds buy companies based entirely on size, giving the largest corporations the biggest weight. However, some investors prefer a systematic method that screens stocks for specific financial traits without paying for active stock pickers. This guide breaks down factor mechanics, compares smart beta against plain-vanilla indexing, and evaluates the 10-year cost impact of higher fund expense ratios.
Quick Takeaways
01Smart beta combines passive index execution with non-market-cap weighting rules based on financial factors.
02Common style factors include value, momentum, quality, low volatility, dividend yield, and company size.
03Factor strategies introduce factor concentration and multi-year performance cycles relative to broad market benchmarks.
04Higher management fees and portfolio turnover create tracking drag over a 10-year holding period.
What Is Smart Beta?
When examining what is smart beta, the core concept centers on changing how an index selects and weights its underlying holdings. The formal smart beta definition describes a hybrid investing framework that pairs transparent, rule-based index tracking with factor selection criteria traditionally used by active fund managers.
In traditional market-capitalization indexing, a stock's weight equals its market value. If a single technology firm grows to represent 7% of a broad market index, a cap-weighted fund automatically holds 7% of its portfolio in that single stock. In contrast, what is smart beta investing designed to solve? It breaks the link between share price and portfolio weight.
As noted by the SEC, factor-based funds use explicit quantitative rules to screen securities, which means these products carry different risk profiles than standard market-cap benchmarks.
How Smart Beta Strategy Works: Core Factors Explained
To understand how a smart beta strategy operates in practice, investors must evaluate the individual equity factors used to construct the index. Rather than relying on human stock pickers, smart beta investing relies on systematic algorithms that rank companies according to fundamental metrics.
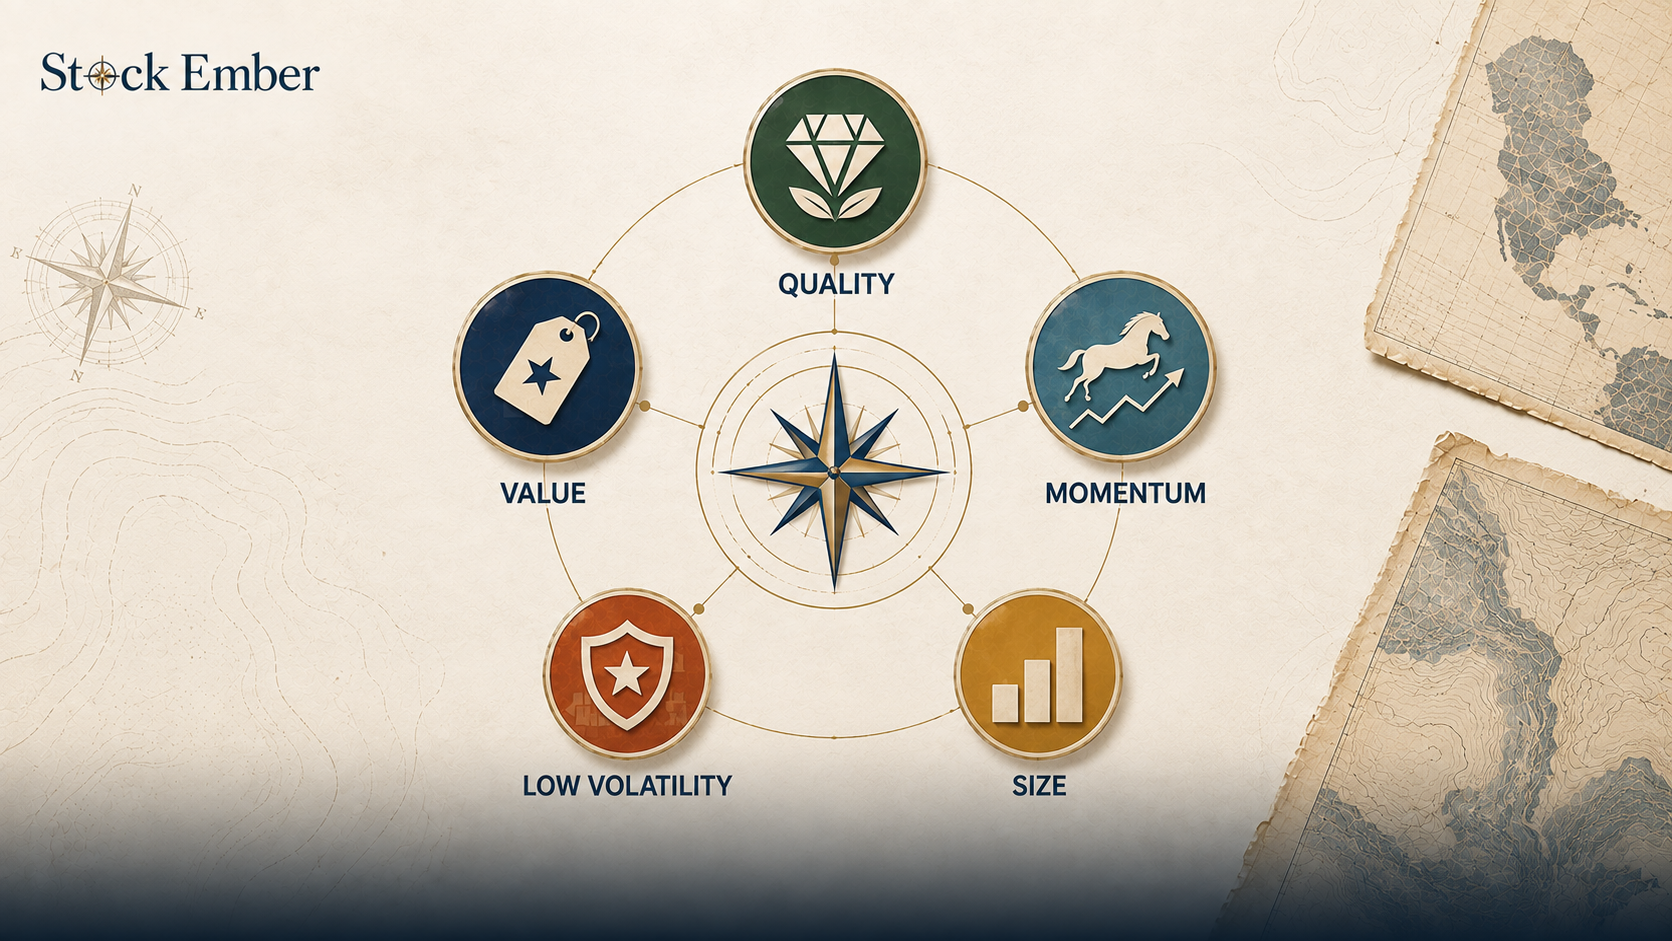
The most common single-factor strategies include:
Value: Weights companies with low price-to-earnings or low price-to-book ratios, aiming to capture stocks trading below their intrinsic fundamental value.
Momentum: Allocates capital toward stocks that have demonstrated strong upward price trend performance over recent months.
Quality: Focuses on companies with low corporate debt, stable earnings growth, and high return on equity metrics.
Low Volatility: Selects stocks that exhibit smaller price fluctuations than the broader market, aiming to reduce portfolio drawdowns during market corrections.
Size: Equal-weights index members or tilts toward smaller-capitalization firms, reducing single-stock concentration.
Each factor strategy targets a specific market anomaly. However, individual factors move through long multi-year performance cycles, outperforming during certain economic conditions and lagging during others.
Diagram illustrating the core financial factors used in smart beta strategy index construction.
Smart Beta vs. Traditional Indexing and Active Management
Investors often ask whether factor investing is active or passive. It sits in the middle ground between traditional cap-weighted indexing and discretionary stock picking:
Traditional Indexing: Fully passive, low cost, and weighted purely by market capitalization. It offers broad market diversification but concentrates exposure in top-valued mega-cap stocks.
Discretionary Active Management: High cost, dependent on human fund manager stock picking, and aims to beat market benchmarks through tactical trading.
Smart Beta: Passive execution following an explicit, rule-based factor formula, charging fees that sit between cap-weighted funds and active managers.
Similar to how ESG investing funds filter broad market indices using environmental and governance rules, smart beta funds filter indices using financial ratios. The index follows a strict mathematical formula without human intervention.
How to Access Smart Beta: Factor ETFs and Index Funds
You can access factor strategies primarily through pooled investment vehicles. Understanding what an ETF is explains how passive funds track these custom index rules while offering daily stock exchange liquidity.
When an index provider constructs a factor benchmark, the fund manager seeks to replicate the benchmark’s constituent weights or use a representative sampling approach. For example, an equal-weighted index holding 500 stocks allocates exactly 0.20% of its weight to every company, rebalancing back to 0.20% at scheduled intervals.
Because factor indices require regular rebalancing to maintain their targeted factor tilts, they can generate higher internal trading activity than simple buy-and-hold cap-weighted funds.
Factor Cyclicality and 10-Year Cost Math
While factor strategies offer deliberate exposure to specific market traits, they can introduce higher ongoing costs and greater performance variability relative to broad market benchmarks. Over a decade-long holding period, fee friction and factor underperformance cycles directly impact net portfolio growth.
Consider a hypothetical $10,000 investment held over 10 years, assuming a broad market return of 7% per year:
Traditional Cap-Weighted Index Fund (0.03% Fee): Delivers a net return of 6.97% per year, compounding $10,000 to roughly $19,616 over 10 years.
Smart Beta Factor ETF (0.35% Total Friction): A factor ETF charging a 0.25% expense ratio plus 0.10% in rebalancing drag yields a net return of 6.65% per year, ending at approximately $19,037.
That 0.32% annual fee difference results in a $580 gap over ten years. Furthermore, if the chosen factor experiences a multi-year period of underperformance such as value stocks lagging growth stocks during extended market rallies, the real return gap widens further.
Structural Risks of Smart Beta Investing
Before incorporating factor strategies into your long-term portfolio, you should evaluate several structural risks:
Extended Factor Underperformance: Individual factors can underperform standard cap-weighted benchmarks for five to ten consecutive years, testing investor patience.
Factor Timing Traps: Attempting to switch between value, momentum, and low-volatility funds based on recent performance often leads to buying factors at peak valuations.
Sector Concentration: Certain factor rules accidentally create heavy industry weightings. For example, a low-volatility fund may concentrate heavily in utilities, while a value fund tilts toward financial firms.
In practice, many long-term investors find that holding a multi-factor ETF or sticking primarily to broad cap-weighted funds helps avoid the emotional temptation to sell factor funds during prolonged underperformance cycles.
Conclusion
These strategies offer a rule-based method to target specific market factors without paying expensive active management fees. By systematically weighting stocks by value, quality, or volatility, factor funds allow investors to customize their risk and return profile.
However, non-market-cap weighting brings higher expense ratios, increased portfolio turnover, and multi-year factor performance cycles. For long-horizon investors, keeping core portfolio holdings in low-cost broad market indices ensures steady compounding while avoiding factor concentration risk.
When you are ready to evaluate transparent, low-cost factor funds and compare management fees, our ETF reviews provide clear breakdowns of structural expenses and tracking quality.
Equity investments carry risk of loss and factor strategies do not protect against broad market downturns, so treat this educational guide as a baseline for your personal portfolio research.
FAQ
5 questions
What is smart beta in investing?
Smart beta is an investment approach that constructs stock index portfolios using alternative weighting rules rather than traditional market capitalization. Instead of giving the largest companies the biggest weight, smart beta strategies select and weight holdings based on fundamental financial traits such as value, momentum, quality, dividend yield, or low share price volatility.
Is smart beta active or passive investing?
Smart beta is a hybrid strategy sitting between active and passive investing. It is passive because it tracks a transparent, rule-based index using an automated algorithm without discretionary human stock pickers. However, it is active in intent because its non-market-cap weighting rules explicitly target factor premiums to achieve specific risk or return characteristics.
What are the main factors used in smart beta ETFs?
The five core equity factors used in smart beta funds are value (low price-to-earnings ratios), momentum (stocks with strong upward price trends), quality (low corporate debt and high return on equity), low volatility (smaller price swings), and size or equal weighting (tilting away from mega-cap dominance).
What is the difference between smart beta and ESG investing?
Smart beta filters and weights index components using financial and valuation metrics to target risk-adjusted returns or specific market factors. ESG investing screens and weights companies based on environmental, social, and governance ethics or corporate sustainability criteria. Both modify traditional market-cap benchmarks, but they pursue different screening goals.
Do smart beta ETFs beat traditional index funds?
Smart beta ETFs do not consistently outperform broad market-cap index funds across every market cycle. While individual factor strategies may generate excess returns during certain economic conditions, factors experience multi-year periods of underperformance. Additionally, higher fund expense ratios and rebalancing turnover create long-term fee friction that can reduce net performance.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.