This process is the periodic adjustment where an index provider updates the weights and company listings within a financial index to keep it aligned with its stated methodology.
If you hold index funds or ETFs, seeing market headlines about an upcoming index reset can trigger unnecessary concern. You might wonder whether you need to take action or if trading costs will eat into your savings. This guide explains how index rebalancing works behind the scenes, why it happens automatically inside your fund, and what its hidden friction means for long-term compound returns.
What Is Index Rebalancing?
This adjustment is the scheduled resetting of a market index's underlying holdings to ensure it continues to reflect the specific market or strategy it was built to measure.
When you buy an index fund—such as a broad global equity index fund—you are purchasing a basket of securities designed to mirror a benchmark. Over time, stock prices move unevenly. Fast-growing companies expand in market value, while lagging firms shrink. Without periodic adjustments, an index would drift away from its core rules, becoming overly concentrated in a few winning stocks or carrying companies that no longer fit its criteria.
Index providers—the independent firms that build and maintain these stock lists—periodically review the index rules. When this process occurs, the provider adds eligible companies, drops ineligible ones, and resets company weightings.
How the Rebalancing Process Works Behind the Scenes
These index adjustments follow strict, transparent schedules rather than discretionary choices by fund managers.
Index methodologies are governed by formal rulebooks maintained by index providers, such as S&P Dow Jones Indices. These rulebooks dictate exactly when and how adjustments take place. Most major benchmarks rebalance on fixed intervals:
- Quarterly resets: Broad US stock benchmarks often adjust every three months (typically in March, June, September, and December) to update share counts and market capitalization weights.
- Semi-annual reviews: Many global and emerging market indexes conduct full reviews twice a year to update market coverage and recheck eligibility rules.
- Annual reconstitutions: Style and small-cap indexes frequently perform a complete overhaul, replacing dozens or hundreds of member stocks at once.
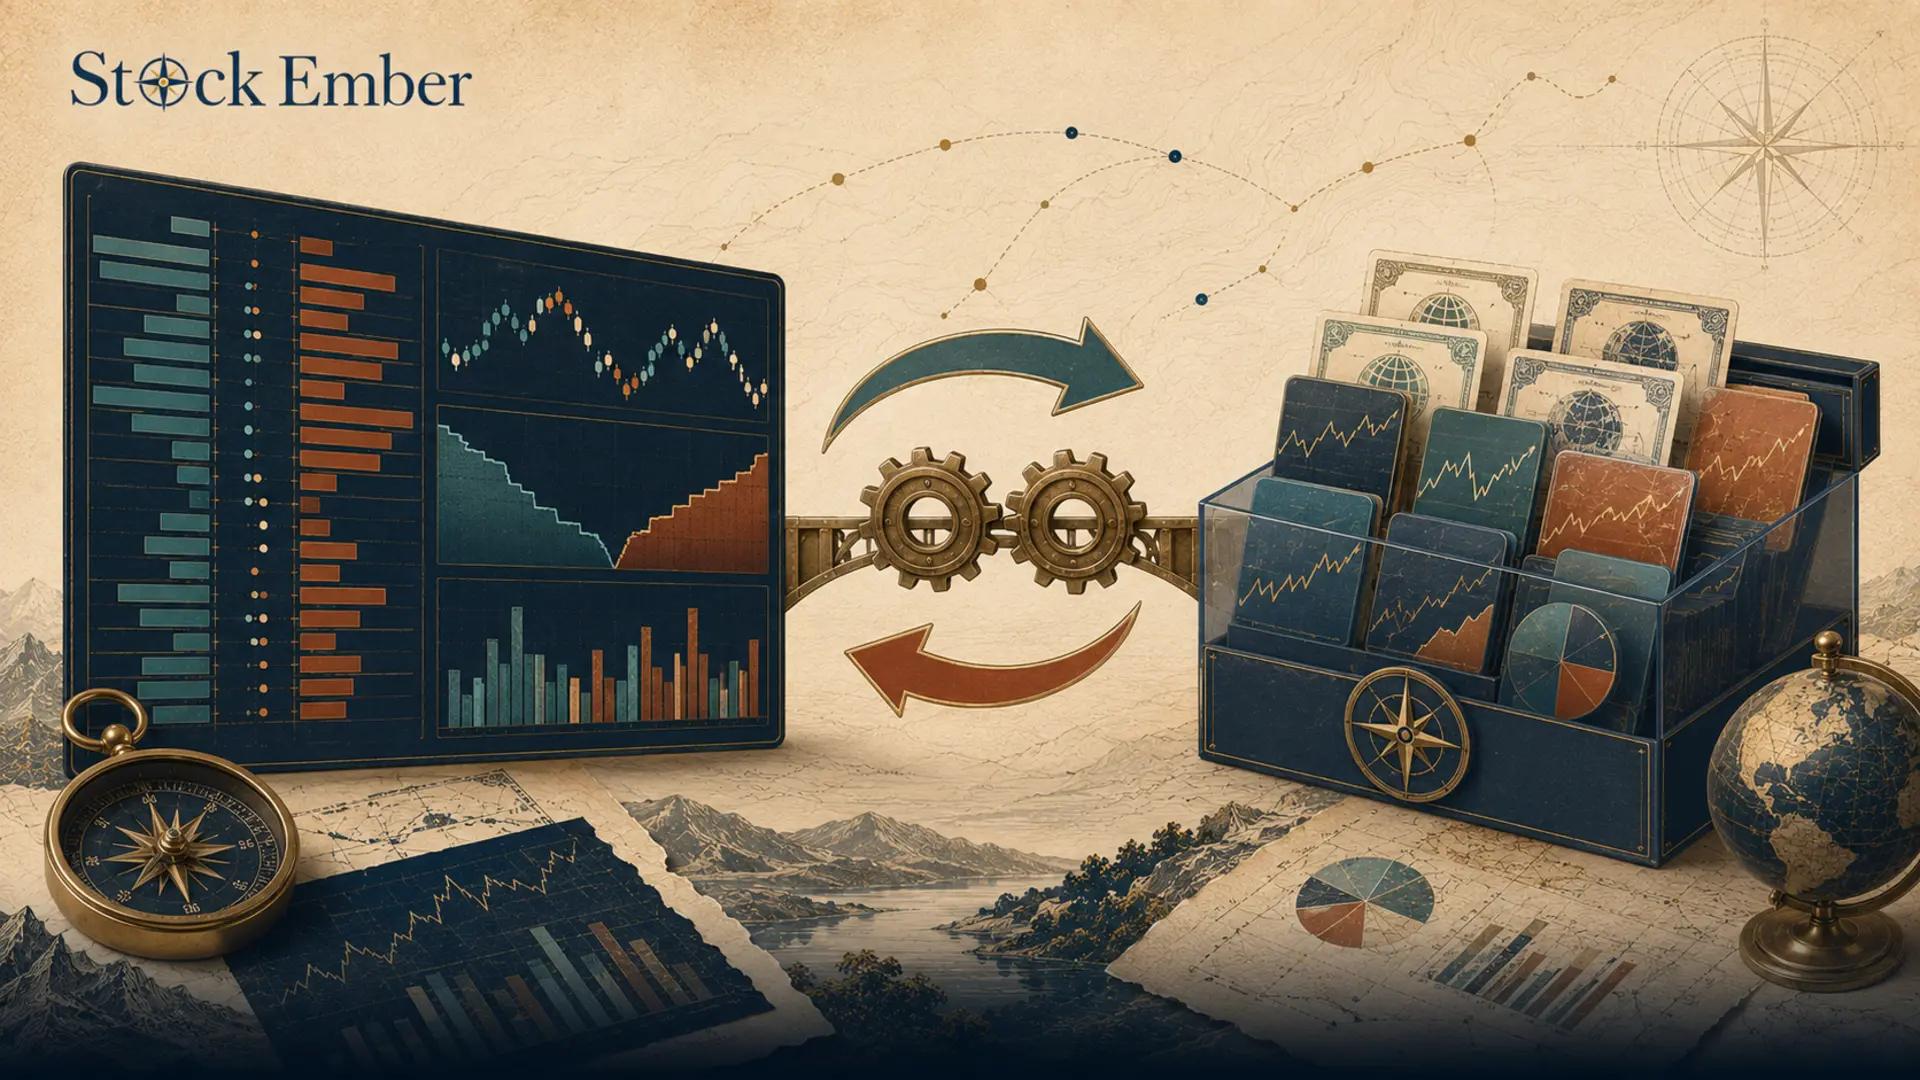
When the index provider announces changes, the ETF portfolio manager steps in. The manager buys shares of newly added companies and sells shares of dropped ones to match the updated benchmark list. Because this work takes place entirely inside the fund structure, individual investors do not place any trades or pay brokerage commissions directly.
Why Index Rebalancing Matters for Long-Term ETF Investors
While index rebalancing keeps funds true to their target strategies, the internal buying and selling process creates real trading costs inside the portfolio.
When a fund manager buys and sells millions of shares during a rebalance, the portfolio incurs transaction costs, including brokerage execution commissions, foreign exchange fees, and bid-ask spreads (the gap between the highest buying price and lowest selling price). Additionally, large market orders can temporarily push stock prices up when buying or down when selling—a friction known as market impact.
These trading costs are paid directly out of fund assets, which creates a slight gap between the performance of the index and the actual ETF. This gap is known as tracking difference.
Consider the long-term impact through a ten-year cost lens. Imagine holding a $10,000 investment in an index fund. If internal trading drag from frequent rebalancing costs the fund just 0.10% each year, that hidden friction removes roughly $100 in direct trading fees over ten years.
More importantly, those lost dollars can no longer compound. Assuming a standard 7% annual return before costs, that small annual drag reduces your final portfolio value by roughly $140 over a decade.
This example is illustrative only — actual returns, fees, and market conditions will vary, and past performance never guarantees future results.
For broad, low-turnover funds, this drag is minimal, but for specialized or high-turnover indexes, internal trading friction can quietly erode long-term gains.
Index Rebalancing vs. Personal Portfolio Rebalancing
A common source of confusion for new investors is mixing up index rebalancing with personal portfolio rebalancing.
The key difference lies in where the adjustments take place and who carries out the trades:
- Index rebalancing (fund-level): Performed automatically by the index provider and fund manager inside the ETF. It resets individual stock weights within a single fund. You do not manage this, nor do you face tax consequences from internal fund trades in most standard structures.
- Personal portfolio rebalancing (investor-level): Performed manually by you across your overall account. It involves adjusting your total allocation between different asset classes—such as shifting money between stock funds and bond funds—to maintain your personal risk profile.
As a buy-and-hold investor, you can leave index-level rebalancing entirely to the fund manager while focusing your energy on your high-level asset allocation.
What to Watch: Turnovers, Spreads, and Arbitrage Drag
Not all indexes rebalance with the same efficiency, and certain fund rules create higher friction than others.
When choosing an index fund, keep these structural factors in mind:
- High turnover drag: Market-cap weighted funds that track top mega-cap stocks typically show turnover below 5% per year, based on S&P Dow Jones Indices' published index methodology reports, while equal-weighted or factor-based indexes can show annual turnover of 20% to 50% or higher.
- Arbitrage front-running: Because index providers publish rebalance changes days or weeks before they take effect, professional trading firms (arbitrageurs) often buy incoming stocks early to push prices up before ETF managers enter the market. This price pressure can force fund managers to buy additions at higher prices and sell deletions at a discount.
- Illiquid market spreads: In foreign or small-cap markets where trading volume is low, buying and selling large blocks of shares during a rebalance incurs wider bid-ask spreads, raising internal execution costs.
Selecting broad, market-cap weighted index funds helps minimize these structural trading costs over long holding periods.
Conclusion
Periodic benchmark recalibration is an essential maintenance process that keeps passive funds aligned with their underlying benchmarks. While fund managers handle all constituent changes automatically behind the scenes, internal trading turnover, bid-ask spreads, and market price pressures generate small execution costs that can accumulate over a ten-year holding horizon.
To protect your long-term returns, favor simple, low-turnover funds with broad market exposure over complex niche strategies that trade heavily. When you're ready to evaluate specific funds, our ETF reviews are the place to start.
Investing always puts your capital at risk and past performance never guarantees future returns, so treat this guide as educational research rather than personalized advice.