A Health Savings Account is an individually owned trust that lets you save, invest, and roll over pre-tax funds for medical care when enrolled in a high-deductible plan. By contrast, a Flexible Spending Account is an employer-owned arrangement granting upfront access to pre-tax medical funds that generally expire at the end of each plan year. Deciding between them depends on whether you prioritize permanent, portable balances or immediate funds alongside lower insurance deductibles.
A Health Savings Account (HSA) is a personal, tax-advantaged account paired with a high-deductible health plan, while a Flexible Spending Account (FSA) is an employer-owned account for eligible out-of-pocket medical expenses.
Choosing between these accounts during benefits enrollment shapes how you pay for prescriptions and doctor visits today, as well as how much cash you preserve for tomorrow. While one provides upfront spending power, the other serves as a permanent investment shelter. This guide examines account rules, tax differences, and how to decide which option matches your healthcare budget.
Quick Takeaways
01Health Savings Accounts (HSAs) belong to you permanently and roll over every year, while Flexible Spending Accounts (FSAs) belong to your employer and follow strict annual spending deadlines.
02An HSA requires enrollment in a qualifying High-Deductible Health Plan (HDHP), whereas an FSA works alongside traditional employer health plans.
03You can invest an HSA in stocks and index funds for long-term growth, but standard FSA balances cannot be invested.
04FSAs grant access to your full annual contribution on day one of the plan year, while an HSA makes money available only as payroll deposits clear.
What Are HSAs and FSAs?
A Health Savings Account (HSA) and a Flexible Spending Account (FSA) are tax-favored accounts created under United States tax law to help workers pay for qualified healthcare expenses with pre-tax income. Both accounts let you set aside money straight from your paycheck before federal income, Social Security, and Medicare taxes apply. The Internal Revenue Service sets these guidelines under IRS Publication 969, defining qualified medical expenses and account rules.
An HSA is an individual custodial account that you own directly. To contribute, you must be enrolled in an eligible High-Deductible Health Plan (HDHP) and have no other disqualifying health coverage. For 2026, a self-only HDHP must carry a minimum annual deductible of $1,700 and an out-of-pocket maximum no higher than $8,500. If your employer does not offer an HSA, you can open one independently at any qualified financial institution.
An FSA, or healthcare flexible spending arrangement, is an employer-sponsored benefit set up under an internal cafeteria plan. You do not need an HDHP to participate; you can pair an FSA with traditional low-deductible coverage. However, you cannot open an FSA on your own. If your employer does not provide the benefit, the account is unavailable to you.
The Core Difference Between an HSA and an FSA
The primary difference between HSA and FSA accounts lies in ownership, rollover rules, and job portability. Because an HSA belongs to you, every dollar you deposit remains yours indefinitely. There is no deadline to spend the money. If you change jobs, move to a new company, or retire, your HSA and its full balance travel with you without tax consequences.
In contrast, an FSA belongs to your employer and operates under a strict "use-it-or-lose-it" rule. At the end of each plan year, unspent FSA money is surrendered back to your employer. Employers may offer one of two optional relief features: a grace period of up to 2.5 months to spend remaining funds, or a small carryover cap of up to $680 for 2026.
Employers can offer either a grace period or a carryover, but never both, and they are not required to offer either. If you leave your job mid-year, you lose any unspent FSA balance immediately unless you elect and pay for COBRA continuation coverage.
Availability of funds also differs in this FSA vs HSA comparison. An FSA provides your full annual election on day one of the plan year under the uniform coverage rule. If you elect to contribute $3,000 for the year, you can spend that entire $3,000 in January, even though only a small deduction has left your paycheck. An HSA works like a regular bank account: you can spend only the actual cash balance deposited to date.
Feature
Health Savings Account (HSA)
Flexible Spending Account (FSA)
Account Ownership
Individual worker owns the account
Employer owns the arrangement
Required Health Plan
Qualifying High-Deductible Health Plan (HDHP)
Any health plan (or no plan, if employer allows)
Rollover Rules
100% rolls over automatically every year
Use-it-or-lose-it (optional small carryover or grace period)
Job Portability
Fully portable; you keep the account forever
Lost upon job departure (unless covered via COBRA)
Fund Availability
Available only as cash is deposited
Full annual election available on day one
Investment Options
Can invest in stocks, bonds, and index funds if your HSA provider offers it
Cash holding only; cannot be invested
The 10-Year Portfolio Lens: Cash Drag vs. Tax-Free Growth
Viewing healthcare accounts through a 10-year investment lens reveals how unspent medical dollars either vanish to forfeiture or compound into meaningful wealth. Because standard FSA balances must be spent annually and cannot be invested, holding excess cash in an FSA creates a drag on your finances. If you forfeit $400 of unspent FSA cash each year, that equals $4,000 of lost capital over 10 years. That is money taken out of your pocket with zero return.
An HSA transforms medical savings into an asset through HSA investing. HSAs offer a triple-tax advantage: contributions go in pre-tax, investments grow tax-free without annual capital gains taxes, and withdrawals remain tax-free for qualified medical costs.
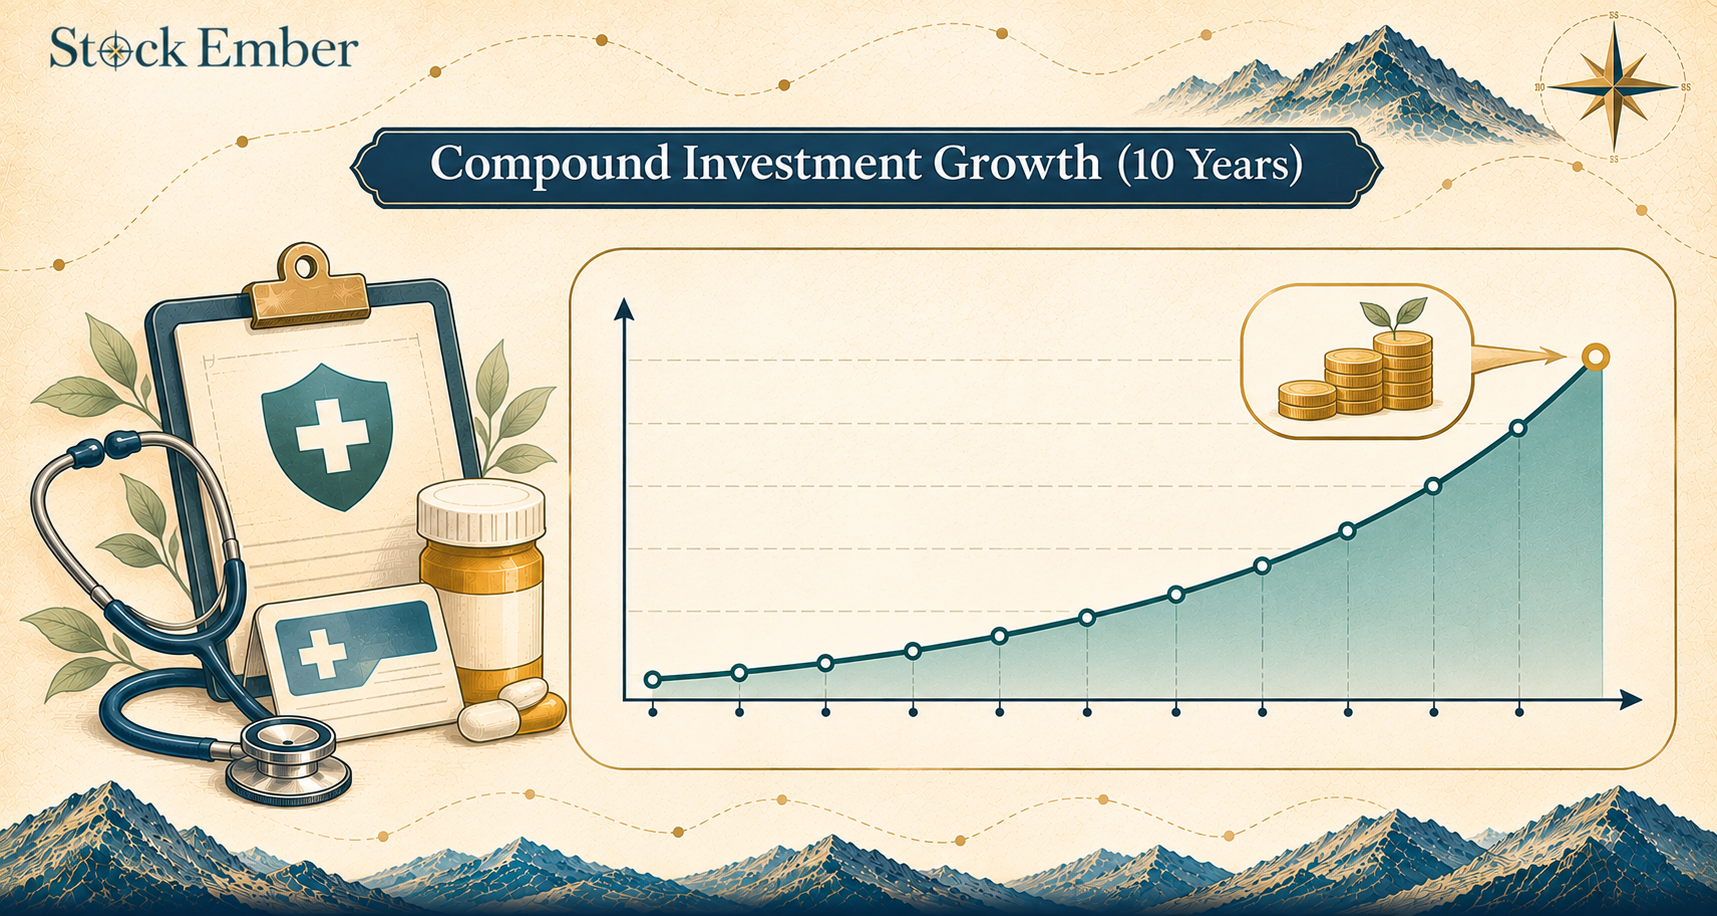
Diagram illustrating long-term investment balance growth over ten years.
Consider a saver who deposits $3,500 into an HSA each year and invests the balance in a broad-market stock index fund. Over 10 years, that saver contributes $35,000. Assuming a hypothetical 7% average annual return, that account could grow to roughly $48,000, though actual returns are not guaranteed and will vary with market performance. Under an FSA, that same surplus money would have faced annual spending pressure or outright forfeiture.
For retirement savers, an HSA functions alongside a Roth IRA to shield long-term savings from taxes. While a Roth IRA accepts after-tax contributions that grow tax-free, an HSA bypasses taxes on the way in as well. This makes an invested HSA one of the most tax-efficient accounts in the financial system.
In practice, many long-term investors find that paying routine out-of-pocket medical bills with cash from a regular checking account while leaving their HSA balance untouched to invest allows the tax-free compounding to work uninterrupted.
Can You Have Both Accounts at the Same Time?
You cannot contribute to a standard healthcare FSA and an HSA in the same tax year under IRS rules. Federal law considers a general-purpose FSA to be disqualifying coverage because it pays for medical expenses before you meet your HDHP deductible. If you enroll in a general FSA, you lose the legal eligibility to put money into an HSA.
There is one important exception: a Limited-Purpose Flexible Spending Account (LPFSA). An LPFSA restricts reimbursements strictly to qualified dental and vision care. Because an LPFSA cannot pay for general medical copays or prescriptions, it does not conflict with HDHP rules. Savers who have access to both can use an LPFSA to pay for dental cleanings, glasses, and contacts out of pre-tax payroll cash while preserving their HSA balance for long-term compounding.
How to Choose: HSA or FSA for Your Situation
Deciding whether to open an HSA or an FSA depends on your expected medical bills, cash reserves, and comfort with high health insurance deductibles. If you are comparing an HSA or FSA, evaluate your health profile alongside your personal budget.
An FSA is practical if you:
Anticipate predictable medical treatments early in the plan year, such as planned surgery or dental work.
Prefer a traditional PPO health plan with fixed copays and lower deductibles.
Lack the liquid cash reserves needed to cover a sudden $3,000 medical bill before insurance kicks in.
An HSA is generally better if you:
Are healthy with low recurring healthcare demands, meaning your medical costs consist primarily of preventive care.
Possess an emergency fund large enough to absorb an unexpected deductible expense without financial strain.
Want to treat healthcare savings as a multi-year investment vehicle that remains under your control for decades.
Pitfalls to Watch: Deductible Shocks and Penalty Traps
Both healthcare accounts carry financial pitfalls that can catch unprepared savers off guard. The greatest danger of an HSA is the upfront deductible shock. Because an HDHP requires you to pay all non-preventive medical bills out of pocket until your deductible is met, a sudden hospital stay early in the year can create serious cash strain if your account has not accumulated enough savings.
With an FSA, the primary trap is overfunding. Employees who overestimate their annual medical outlays risk forfeiting hundreds of dollars at the end of the year. Always review your previous twelve months of health bills before choosing your annual FSA election.
Finally, remember the early withdrawal penalty on HSAs. If you withdraw HSA money for non-medical expenses before age 65, the IRS charges ordinary income tax plus a 20% penalty. After age 65, the 20% penalty disappears; withdrawals for non-medical expenses are then taxed simply as ordinary income, exactly like a traditional retirement account.
Conclusion
Choosing between an HSA and an FSA comes down to balancing current medical needs against long-term financial flexibility. An FSA delivers immediate day-one spending power for known medical costs under low-deductible insurance plans, but it demands careful planning to avoid year-end forfeiture. An HSA requires you to absorb higher upfront insurance deductibles, but it rewards you with portable ownership, rollover protection, and multi-year compound growth.
When you are ready to evaluate platforms for long-term growth, our Broker reviews offer a clear starting point. Every investment carries the risk of loss and past market performance never guarantees future returns, so use this guide as an educational baseline for your personal planning.
FAQ
5 questions
What qualifies as a High-Deductible Health Plan (HDHP) for HSA eligibility?
To qualify as an HDHP, a health insurance policy must meet statutory IRS thresholds for minimum deductibles and maximum out-of-pocket limits. For 2026, an eligible individual HDHP requires a minimum annual deductible of $1,700 and caps annual out-of-pocket costs at $8,500. Additionally, the plan cannot provide coverage for non-preventive medical services until you pay the deductible in full.
What happens to unspent FSA funds if you leave your job mid-year?
Because an FSA belongs to your employer, any balance remaining in the account is generally forfeited immediately upon your employment termination date. You cannot transfer the money to an individual account or your next employer's plan. Your only option to access unspent FSA balances post-departure is electing COBRA continuation coverage, which requires paying the full monthly contribution plus administrative fees.
Can you use an HSA for non-medical expenses after turning 65?
Yes. Once you reach age 65, the 20% IRS early withdrawal penalty for non-qualified distributions is eliminated entirely. You can withdraw funds for any purpose, including everyday living expenses, subject only to ordinary income tax. Qualified medical expenses, however, remain completely tax-free at any age, preserving the account's primary tax advantage throughout retirement.
How does a Dependent Care FSA differ from a healthcare FSA?
A Dependent Care FSA is a separate employer-sponsored arrangement designed specifically for eligible childcare or eldercare expenses, such as preschool, daycare, and after-school programs. While a general-purpose healthcare FSA disqualifies you from contributing to an HSA, a Dependent Care FSA does not. You can freely contribute to an HSA and a Dependent Care FSA concurrently within the same tax year.
Can you change your HSA or FSA contribution amounts during the year?
HSA and FSA contribution rules differ significantly mid-year. You can adjust, stop, or increase your HSA payroll contributions at any point during the year through your employer or make direct contributions independently. Conversely, FSA elections are legally locked under IRS cafeteria plan rules during annual open enrollment and can only be modified if you experience a qualifying life event, such as marriage or job change.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.