A closed-end fund is a publicly traded investment company that raises a fixed pool of capital through an initial public offering and trades its shares on secondary stock exchanges. Unlike open-end funds, its market share price fluctuates based on investor demand, often trading at a premium or discount to its Net Asset Value (NAV). Investors buy closed-end fund shares through standard brokerage accounts.
A closed-end fund is a publicly traded investment company that raises a fixed pool of capital through an initial public offering and trades its shares on secondary stock exchanges.
When searching for high portfolio income, investors often encounter funds offering eye-catching distribution yields. However, these pooled vehicles operate differently from traditional open-end index products. This guide breaks down how a closed-end fund functions, why share prices trade at premiums or discounts to underlying asset values, and how leverage expenses impact 10-year portfolio returns.
Quick Takeaways
01A closed-end fund raises capital once through an initial public offering, creating a fixed share count that trades on public stock exchanges.
02Unlike open-end funds, closed-end fund market prices move based on buyer demand, causing shares to trade at a premium or discount to Net Asset Value.
03Portfolio managers use structural leverage to boost distribution payouts, which amplifies volatility during market downturns.
04Distributions can include return of capital, which returns investor principal rather than true portfolio earnings.
05Higher management fees and borrowing costs create tracking drag over a 10-year holding period.
What Is a Closed-End Fund?
To understand a closed-end fund, you need to look at how capital is raised and managed. The formal closed end fund definition refers to a pooled investment vehicle registered under federal securities regulations that issues a fixed number of shares during an initial fundraising period.
As outlined by the SEC, a closed end investment fund differs structurally from open-end mutual funds because it does not issue new shares or redeem existing shares when investors buy or sell.
While investors often refer to these products as a closed end mutual fund, they trade on stock exchanges throughout the trading day just like corporate stocks. After the initial offering closes, any investor purchasing a closed end fund investment must buy shares from another investor on the secondary market.
How Closed-End Funds Work: Capital Structure and Exchange Trading
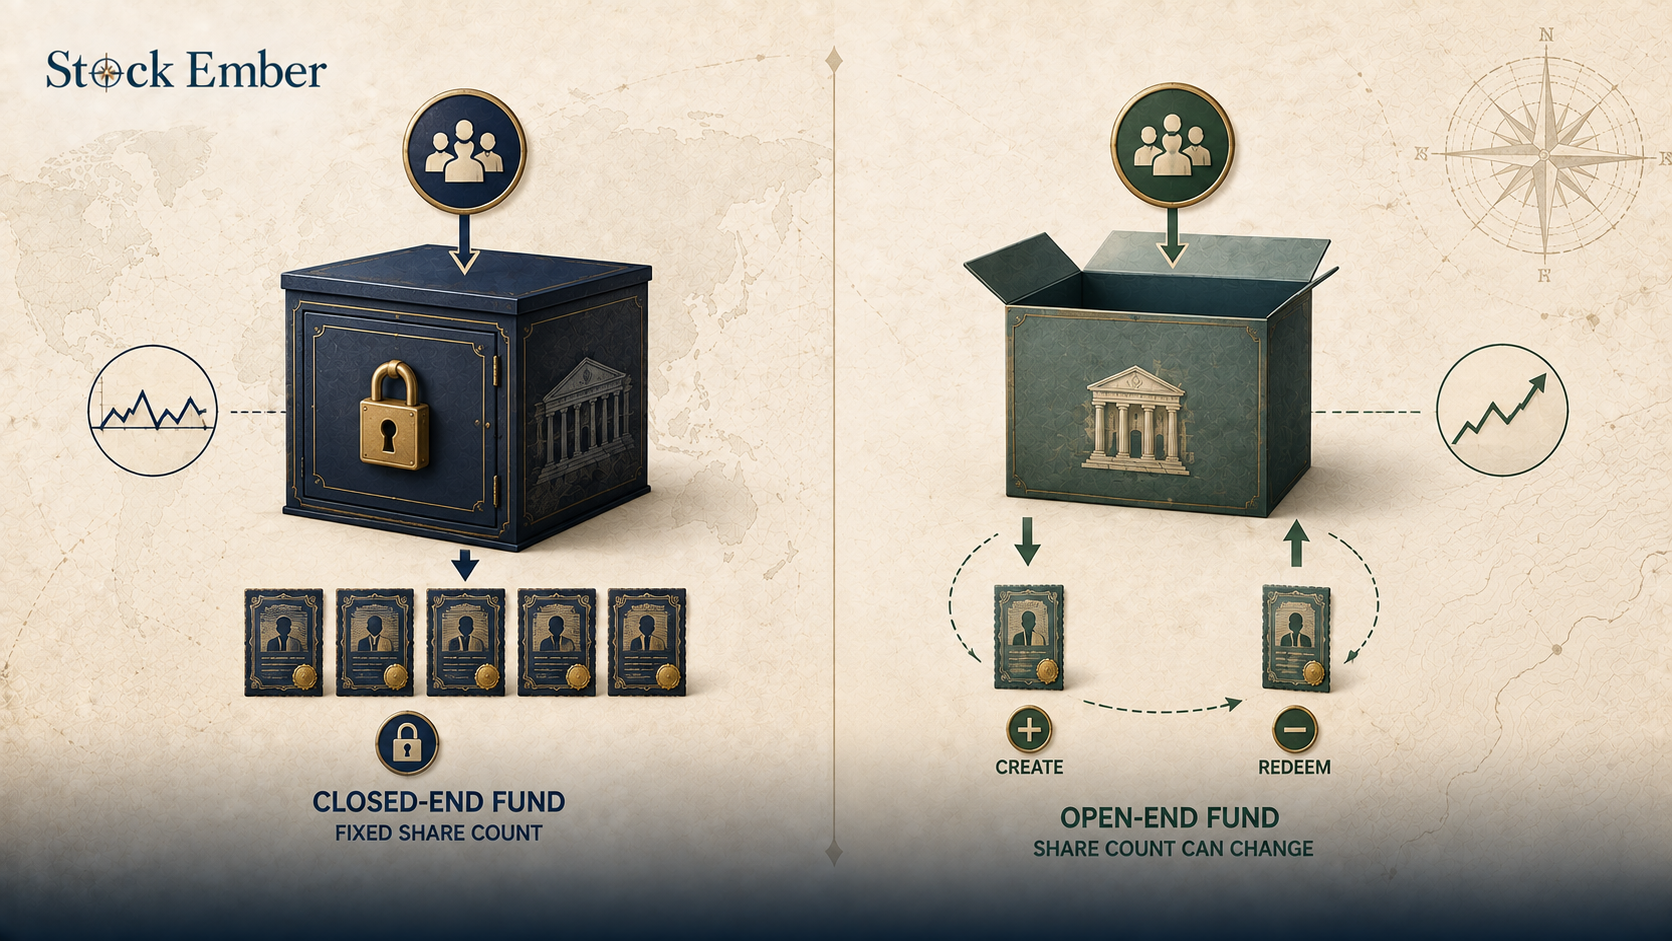
A closed-end fund operates with a fixed capital structure, meaning the fund sponsor does not issue or redeem shares on a daily basis after the initial public offering.
In a traditional open-end fund, new investor cash creates new fund shares, and redemptions destroy shares. Because a closed-end fund keeps its share count fixed, the fund manager does not need to maintain cash reserves to satisfy daily investor withdrawals.
This fixed capital pool allows portfolio managers to invest in less liquid market sectors, such as municipal bonds, private debt, preferred shares, or international equities. The manager can hold assets through market downturns without being forced to sell underlying holdings at distressed prices to pay redeeming shareholders.
Diagram comparing closed-end fund fixed share structure against open-end fund creation.
Net Asset Value vs. Market Price: Discounts and Premiums
A closed-end fund's market price frequently diverges from its Net Asset Value because shares trade on public exchanges, with prices shaped largely by investor supply and demand.
Every closed-end fund has two distinct values:
Net Asset Value (NAV): The total market value of all underlying securities held by the fund, minus any liabilities, divided by the total number of outstanding shares.
Market Price: The price at which individual shares trade on a public stock exchange throughout the trading day.
When investor demand for a fund is high, market price can rise above NAV, causing the fund to trade at a premium. Conversely, when market sentiment turns negative, share prices fall below NAV, creating a discount. Structural discounts often persist for years due to high fund expense ratios, illiquid holdings, or weak historical performance.
How to Access CEFs: ETFs and Share Class Mechanics
Retail investors purchase closed-end fund shares through standard brokerage accounts on secondary stock exchanges, exactly like buying individual corporate shares.
You'll typically buy closed-end fund shares through a standard brokerage account, just like buying individual stocks.
When evaluating pooled products, learning what an ETF is helps clarify how exchange-traded funds use institutional arbitrage to keep market prices close to asset values, whereas closed-end funds lack that creation mechanism.
Understanding ETF share classesalso shows how capital structure determines trading liquidity and expense allocation. While open-end ETFs issue multiple share classes to track benchmarks smoothly, a closed-end fund issues a single, fixed pool of common shares, occasionally issuing preferred shares to raise leverage capital.
10-Year Cost Math: Leverage Costs, Fees, and Managed Distributions
Over a 10-year holding period, borrowing costs for structural leverage and higher management fees eat into total compound returns.
Many closed-end funds use financial leverage by issuing preferred shares or borrowing through debt to buy additional income-producing assets. While this leverage boosts distribution income during low interest rate environments, it increases operating costs and amplifies losses when markets drop or borrowing rates rise.
Furthermore, investors must scrutinize distribution sources. Fund distributions may include "Return of Capital" (ROC). Destructive return of capital returns your own principal investment to maintain advertised payout rates, which erodes fund asset value over time.
Consider a hypothetical $10,000 investment held over 10 years, assuming a baseline annual asset growth of 7%:
Fund Type
Annual Cost
Net Return
10-Year Value
Standard Low-Cost Index Fund
0.10%
6.90%
$19,488
Leveraged Closed-End Fund
0.85%
6.15%
$18,163
These figures are hypothetical illustrations only. Actual fund returns are not guaranteed, and capital remains at risk.
That 0.75% annual cost gap deprives the investor of nearly $1,325 in compound wealth over ten years, even before accounting for potential asset value erosion from destructive distributions.
Structural Risks of Closed-End Funds
Investing in closed-end funds involves distinct structural risks, primarily portfolio leverage and market price volatility.
Leverage Risk: Borrowed capital amplifies downside losses during market downturns and increases fund sensitivity to rising central bank interest rates.
Persistent Discount Traps: Buying a fund at a 10% discount to NAV does not guarantee profit. If investor demand remains weak or management fees remain high, the discount can widen further.
Distribution Cuts: When interest rates rise or underlying portfolio income declines, fund managers may cut monthly distributions, triggering sharp drops in share prices.
In practice, many long-term investors find that inspecting whether a fund's high payout comes from real investment income or destructive return of capital is essential before buying.
Conclusion
A closed-end fund provides access to specialized asset classes and high income payouts through a fixed exchange-traded share structure.
By locking in capital, these funds allow managers to invest in illiquid holdings without facing daily shareholder redemption demands. However, structural leverage, potential price discounts, and higher operating expenses create significant long-term performance drag compared to broad market index funds.
When you are ready to compare pooled fund structures and evaluate fee drag across asset classes, our ETF reviews provide clear breakdowns of structural expenses and tracking quality.
Equity and bond investments carry risk of capital loss, and leverage can amplify portfolio declines, so treat this educational guide as a starting point for your personal portfolio research.
FAQ
5 questions
What is a closed-end fund?
A closed-end fund is a registered investment company that raises a fixed pool of capital through an initial public offering and issues a set number of shares. These shares trade on secondary stock exchanges throughout the trading day, with market prices determined by supply and demand rather than direct creation or redemption by the fund sponsor.
What is the difference between an ETF and a closed-end fund?
The main difference lies in capital structure. Exchange-traded funds (ETFs) have an open-end structure with continuous share creation and redemption, keeping market prices closely aligned with Net Asset Value (NAV). Closed-end funds have a fixed share count without continuous creation/redemption, allowing market prices to trade at persistent discounts or premiums to NAV.
Why do closed-end funds trade at a discount to NAV?
Closed-end funds trade at a discount to Net Asset Value when market supply exceeds investor demand. Factors contributing to persistent discounts include high management fees, structural leverage expenses, poor historical performance, investor skepticism regarding illiquid assets, or broader negative sentiment toward specific asset classes.
How do closed-end funds pay distributions?
Closed-end funds pay distributions using three potential sources: net investment income (interest and dividends earned by underlying assets), realized capital gains from selling portfolio holdings, and return of capital (ROC). Destructive return of capital returns investor principal to sustain payout rates, which erodes the fund's underlying asset value over time.
What are the main risks of investing in a closed-end fund?
The primary risks of closed-end funds include structural leverage risk (borrowed capital that amplifies losses and borrowing costs during market downturns), persistent NAV price discounts that fail to narrow, potential distribution cuts when portfolio income falls, and higher total expense ratios compared to standard index funds.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.