Recency bias is a cognitive shortcut where investors give excessive weight to recent market events while discounting long-term historical data. In financial markets, this leads investors to extrapolate short-term market swings into permanent future trends, driving performance chasing during bull markets and panic selling during downturns. Rule-based passive strategies help insulate portfolios from these emotional shortcuts.
Recency bias is a psychological shortcut where investors give excessive weight to recent market events while discounting long-term historical data. In financial markets, this cognitive bias causes individuals to expect current bull or bear trends to continue indefinitely into the future.
When stock markets experience rapid gains or sudden downturns, emotional reactions often lead investors to abandon their established asset allocation strategies. For long-term index and ETF investors, overreacting to short-term market noise creates unnecessary portfolio turnover and locks in avoidable capital losses.
This guide explains how recency bias distorts risk perception across market cycles, its hidden compounding cost over a 10-year horizon, and how rule-based passive strategies protect long-term portfolio growth.
Quick Takeaways
01Recency bias causes investors to extrapolate recent market swings into permanent future trends.
02During market booms, this bias drives performance chasing; during market downturns, it triggers panic selling.
03Over-weighting short-term results distorts risk tolerance and increases portfolio turnover.
04Rule-based rebalancing and automated dollar-cost averaging insulate investors from emotional decision-making.
What Is Recency Bias?
To understand what is recency bias, it helps to look at how human memory processes financial risk. By standard recency bias definition principles, it is a cognitive shortcut where recent experiences dominate an individual's decision-making process because those memories are most easily recalled.
In everyday life, remembering recent events quickly is useful. In financial markets, however, this psychological mechanism creates severe distortions. Investors suffering from this cognitive bias evaluate market risk based almost entirely on what happened over the last few months or quarters, rather than analyzing multi-decade historical returns.
Understanding the broader recency bias meaning reveals why so many market participants change strategies at the worst possible moments. Rather than recognizing that markets move in cyclical patterns, biased investors assume that a short-term economic trend reflects a permanent structural shift.
How Recency Bias Works in Market Cycles
Recency bias alters investor behavior differently depending on where the market sits within a broader economic cycle. Both extreme optimism and deep pessimism stem from the same underlying cognitive error: extrapolating the immediate past into the distant future.
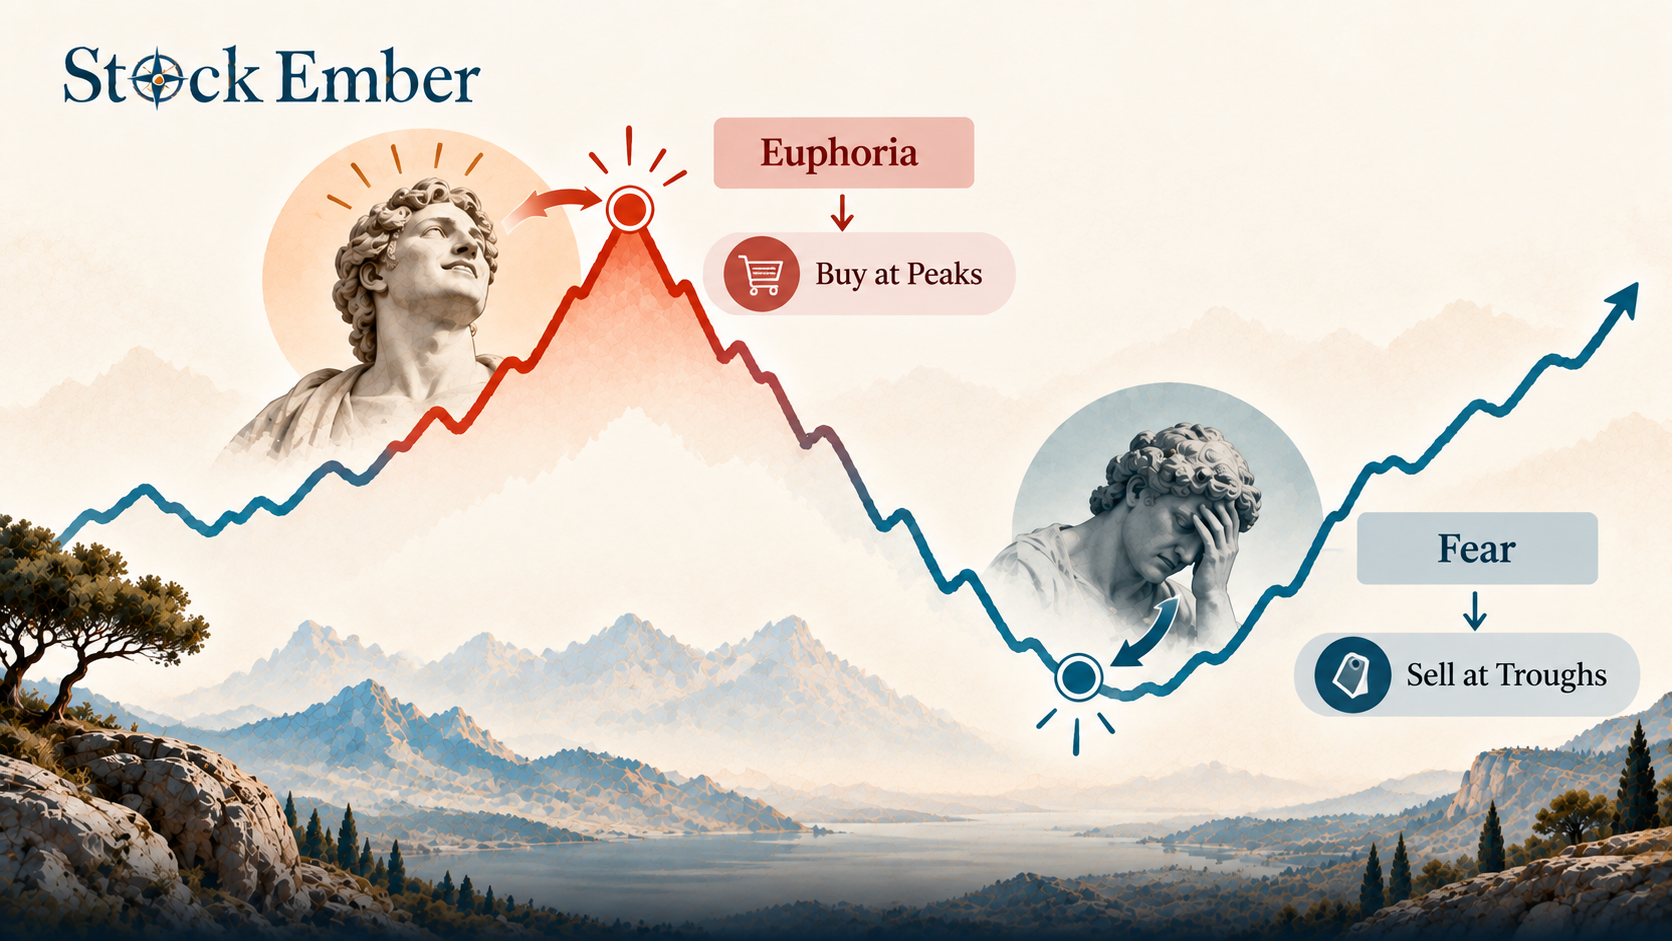
Diagram depicting the psychological cycle of recency bias in bull and bear markets.
1. Bull Market Euphoria and Performance Chasing
During prolonged bull markets, rising asset prices create a false sense of security. As portfolio values rise month after month, investors forget that severe market drawdowns are a normal feature of equity investing.
This environment fosters fear of missing out (FOMO). Investors often shift cash into asset classes or sector ETFs that have performed best over the preceding 12 months, frequently purchasing shares at peak valuations right before a market cycle turns.
2. Bear Market Panic and Over-Defensiveness
Conversely, during market downturns, recency bias makes recent declines feel endless. Investors who were comfortable taking equity risks during a bull market suddenly view stocks as unacceptably dangerous after a 20% drawdown.
This psychological pressure leads many individuals to liquidate equity holdings at depressed valuations, moving capital into cash or money market funds. By prioritizing short-term capital preservation, they miss the subsequent recovery phase, locking in paper losses permanently.
The Hidden 10-Year Cost of Recency-Driven Investing
The financial damage caused by recency bias is rarely obvious in the short term, but it compounds significantly over a multi-year horizon. Switching strategies based on recent trailing returns creates a pattern of buying high and selling low.
Investor Behavior
Short-Term Action
Long-Term 10-Year Result
Recency-Driven Investor
Shifts capital into top 12-month performers; sells during market corrections.
High turnover, locked-in losses, missed recovery rallies, lower net returns.
Disciplined Passive Investor
Rebalances back to target asset allocation regardless of recent market noise.
Low turnover, systematically buys undervalued assets, captures full market recovery.
Consider an investor who panics during a major market correction and moves their portfolio into cash. If the broader market recovers over the following 18 months while the investor remains on the sidelines waiting for "clarity," the opportunity cost is substantial.
Over a 10-year period, missing just a handful of the market's best recovery days can drastically reduce total portfolio accumulation. This behavioral flaw transforms temporary price volatility into permanent capital destruction.
Recency Bias vs. Disciplined Passive Investing
Managing emotional shortcuts requires shifting from subjective market timing to a structured system rooted in behavioral finance. Behavioral finance studies how cognitive errors directly impact financial decisions, helping investors build safeguards against their own psychological traps.
In practice, many long-term investors find that checking portfolio balances daily during volatile periods strongly increases the urge to trade. Reducing monitoring frequency to a scheduled quarterly or annual review noticeably helps reduce emotional reactions to short-term price swings.
This bias also interacts with other cognitive shortcuts, such as the disposition effect, where investors hold onto losing positions too long while selling winning positions prematurely to lock in a feeling of safety. A disciplined passive strategy removes these emotional dilemmas by enforcing pre-set rules for buying, holding, and rebalancing.
Practical Strategies to Overcome Recency Bias
Overcoming cognitive bias does not mean trying to overpower human emotion through sheer willpower. Instead, effective portfolio management relies on establishing systematic operational rules.
1. Automating Investments with Dollar-Cost Averaging
Automating monthly contributions into broad-market index funds removes short-term market conditions from the buying decision. Dollar-cost averaging ensures that you continue buying shares whether recent headlines are optimistic or pessimistic.
2. Using Pre-Set Rebalancing Schedules
Establish a fixed schedule (such as once per year) or a percentage threshold (such as a 5% drift from target allocation) to rebalance your portfolio. Rebalancing forces you to systematically sell asset classes that have recently surged and buy asset classes that have recently underperformed.
3. Maintaining a Written Investment Policy Statement
A written policy outlines your target asset allocation, investment horizon, and rebalancing rules. Reviewing your written policy during market turbulence serves as a helpful reminder of your original multi-year goals.
Common Pitfalls: Extrapolation and Strategy Hopping
The most common error driven by recency bias is strategy hopping, abandoning a sound index investment plan to chase whatever fund or sector performed best last year.
Financial media frequently highlight recent top performers, encouraging investors to treat short-term past performance as a forecast of future results. However, historical data consistently demonstrates that top-performing asset classes rotate over time. Buying last year's winner often means entering an asset class right as its valuation becomes stretched.
Conclusion
Recency bias is an understandable human tendency that leads investors to treat recent market trends as permanent realities. By over-weighting short-term performance, investors risk chasing market highs, selling during corrections, and undermining their long-term wealth accumulation.
Overcoming this cognitive trap requires replacing emotional market reactions with a clear, rules-based passive framework. When you are ready to evaluate transparent, broad-market index options for your portfolio, exploring our ETF reviews offers a practical next step.
Investing always involves risk, and past performance does not guarantee future results. Treat this guide as educational material to support your own independent research, not personalized financial advice.
FAQ
5 questions
What is recency bias in simple terms?
In simple terms, recency bias is the tendency to assume that whatever is happening in the market right now will continue happening indefinitely. It causes investors to overreact to recent short-term price movements while ignoring decades of historical market data.
What is an example of recency bias in financial markets?
A classic example occurs during a market boom when investors buy hot sector ETFs at peak valuations because they performed well over the last 12 months. Conversely, during a market correction, this tendency causes investors to panic-sell stocks into cash because they expect prices to keep falling.
How does recency bias affect long-term portfolio returns?
Recency bias harms long-term returns by encouraging high portfolio turnover, bad market timing, and locking in paper losses. Selling during downturns and chasing recent top performers creates a recurring cycle of buying high and selling low, which significantly reduces total compounding over a 10-year horizon.
What is the difference between recency bias and the disposition effect?
This phenomenon focuses on over-weighting recent market events to project future trends. In contrast, the disposition effect describes the psychological tendency to hold onto losing assets too long in hopes of breaking even while selling winning assets prematurely to lock in small gains.
How can passive investors avoid recency bias?
Passive investors can avoid recency bias by automating contributions through dollar-cost averaging, adhering to a fixed rebalancing schedule (such as annually), and using a written Investment Policy Statement to guide decisions during market volatility rather than reacting to daily headlines.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.