The debt-to-equity ratio compares a company's total liabilities with its shareholders' equity. It shows how much a business relies on debt financing relative to owner capital.
Debt financing can help a company fund operations and growth, but it also increases financial obligations. This ratio helps investors assess how a business balances borrowed capital with the equity provided by shareholders.
When evaluating public companies, looking at revenue alone can hide financial stress caused by excessive borrowing. A company with heavy debt obligations must make regular interest payments regardless of whether sales go up or down. Understanding financial leverage helps investors evaluate long-term solvency and financial safety before committing capital. This guide explains how this ratio works, what benchmark ranges indicate, how borrowing impacts long-term returns, and common balance sheet red flags.
Quick Takeaways
01This leverage ratio compares total liabilities to shareholders' equity to reveal how a company funds its assets.
02A lower ratio generally indicates a conservative capital structure funded mostly by equity, while a higher ratio reflects greater reliance on debt.
03Benchmark ranges vary significantly across industries; capital-intensive sectors naturally carry higher debt loads than asset-light businesses.
04Heavy debt obligations create fixed interest expenses that can squeeze profit margins and increase default risks during economic recessions.
What Is Debt to Equity Ratio? Definition & Formula
In balance sheet accounting, this leverage measure reflects a company's reliance on borrowed capital relative to owner funding.
To understand what is debt to equity ratio in practical terms, investors must break down the two main components of the balance sheet:
Total Liabilities: The sum of all short-term and long-term financial commitments, including supplier accounts payable, short-term bank loans, corporate bonds, and lease obligations.
Shareholders' Equity: The residual interest in the company's assets after subtracting total liabilities, generally including contributed capital, retained earnings, and other equity accounts.
A commonly used balance sheet formula expresses this relationship as a straightforward division:
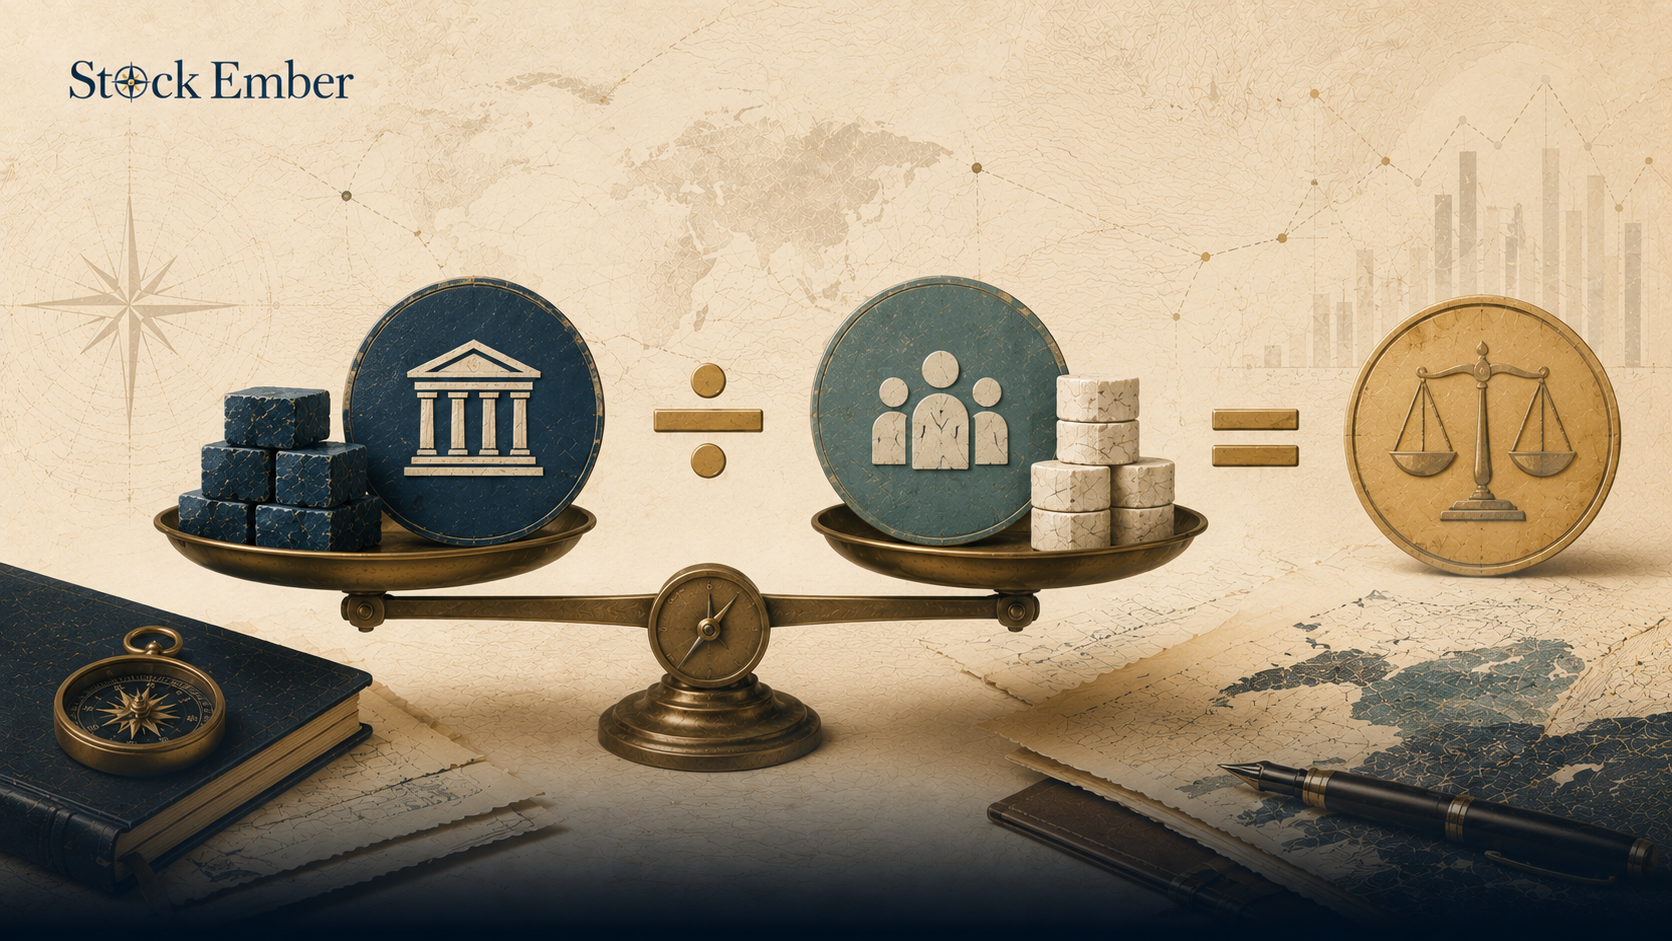
Debt-to-Equity Ratio = Total Liabilities / Total Shareholders' Equity
For example, if a business reports $150,000 in total liabilities and $100,000 in total shareholders' equity, the result is 1.5 ($150,000 / $100,000). This means the firm holds $1.50 of debt for every $1.00 of owner equity.
For anyone building fundamental analysis skills when investing in stocks, checking capital structure helps investors assess a company's debt burden and the financial risks associated with leverage.
Diagram illustrating Total Liabilities divided by Shareholders' Equity to calculate debt-to-equity ratio.
What Is a Good Debt to Equity Ratio? Benchmark Ranges
A ratio between 1.0 and 2.0 may indicate a moderate use of debt relative to equity. However, acceptable baseline levels depend heavily on industry capital requirements, cash flow stability, and prevailing interest rates.
Investors generally evaluate ratio ranges across three major categories:
Below 1.0 (Conservative Financing): Shareholders' equity exceeds total liabilities. The business relies primarily on internal profits and equity capital, resulting in low default risk and lower interest burdens.
1.0 to 2.0 (Moderate Financial Cushion): Represents a typical funding balance for established companies using moderate borrowing to grow without over-extending their balance sheets.
Above 2.0 (High Financial Leverage): Total liabilities are more than double shareholders' equity. While borrowing can boost returns during economic expansions, high debt increases vulnerability to rising interest rates and temporary revenue drops.
Industry context plays an important role when setting ratio benchmarks. Capital-heavy sectors such as electric utilities, telecommunications, and manufacturing infrastructure regularly operate with leverage levels above 2.0 or 3.0. They use predictable long-term utility cash flows to support large debt obligations needed to build power plants or fiber optic networks. Conversely, asset-light technology and software businesses usually maintain low ratios below 0.5 because they require minimal physical equipment and can fund expansion through ongoing operational cash flow.
According to financial analysis documentation published by the SEC, comparing solvency metrics against industry peers provides a clearer picture of balance sheet safety than relying on single absolute limits.
Why Financial Leverage Matters for Buy-and-Hold Investors
For long-term buy-and-hold investors, monitoring financial borrowing helps evaluate how well a company can withstand unexpected recessions over a ten-year holding period.
When a firm takes on heavy corporate debt, interest payments become a fixed operating expense that must be settled regularly regardless of business conditions. High interest costs directly drain operational profits, reducing overall gross margin profitability and leaving less net capital available to reinvest into research or fund dividend payouts.
Over a ten-year horizon, economic contractions will test every business. A company entering a recession with low debt can use its excess cash flow to acquire struggling competitors or buy back undervalued shares. On the other hand, an over-leveraged business may be forced to cut dividend payouts, sell assets at distressed prices, or issue new shares at low market valuations, permanently diluting existing owners.
In practice, many long-term investors find that tracking multi-year trends in this leverage metric reveals whether management uses debt responsibly to build lasting business value or uses excessive borrowing to mask slowing sales growth.
Common Debt-to-Equity Red Flags
Analyzing debt levels requires looking past the headline ratio number to spot underlying accounting risks:
Negative Ratio: A negative ratio occurs when total shareholders' equity turns negative due to multi-year operating losses creating an accumulated deficit. This indicates severe insolvency risk, showing that historical losses have erased all contributed equity capital.
Off-Balance-Sheet Commitments: Unfunded pension liabilities, large legal commitments, or heavy operating lease obligations may not show up in short-term debt metrics, understating true financial risk.
Rising Borrowing paired with Declining Sales: When a company continuously issues new debt while sales and cash flows shrink, it may be borrowing simply to cover routine operational costs or maintain dividend payouts.
Conclusion
This leverage ratio provides a clear snapshot of a company's financial position by comparing total liabilities to shareholders' equity. While a ratio between 1.0 and 2.0 indicates moderate financial balance for most commercial firms, comparing ratios against industry peers ensures fair analysis.
When you are ready to select an investment platform to build your long-term stock portfolio, our broker reviews offer an objective breakdown of trading platforms and account options. Always remember that solvency analysis represents one component of fundamental research, and all stock investments involve the risk of capital loss.
FAQ
5 questions
What is debt to equity ratio?
The debt-to-equity ratio is a balance sheet financial metric that compares a company's total liabilities to its shareholders' equity. It acts as a solvency measure to evaluate how much debt a business uses to finance its operations relative to owner capital.
What is a good debt to equity ratio?
A debt-to-equity ratio between 1.0 and 2.0 is generally considered moderate and healthy for standard commercial firms. However, acceptable levels vary significantly by industry; capital-heavy utilities regularly operate above 2.0, whereas asset-light technology companies often stay below 0.5.
How do you calculate debt to equity ratio?
You calculate it using the formula: Debt-to-Equity Ratio = Total Liabilities / Total Shareholders' Equity. Both figures are found on a company's balance sheet under total liabilities and total equity.
What does a high debt to equity ratio mean?
A high debt-to-equity ratio (above 2.0) indicates that a company relies heavily on debt financing. While leverage can boost returns during growth periods, high debt creates fixed interest obligations that increase financial risk during economic downturns or rising interest rate environments.
What does a negative debt to equity ratio mean?
A negative debt-to-equity ratio occurs when total shareholders' equity turns negative due to multi-year net operational losses (accumulated deficit). It signals severe insolvency risk, showing that historical losses have erased all contributed equity capital.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.