Active investing relies on human security selection and market timing to pursue market-beating returns, whereas passive investing uses automated rules to match the performance of a broad market index. Over a 10-year horizon, passive index funds typically carry significantly lower expense ratios and remove single-manager risk, offering a cost-efficient baseline that many long-term investors use to build wealth.
Active investing relies on human fund managers who selectively pick individual securities and time trades to outperform a market benchmark, whereas passive investing aims to match the returns of a benchmark index by holding a broad market basket.
Choosing between active vs passive investing dictates how much you pay in management fees, how your capital is taxed, and ultimately how your portfolio compounds over multi-decade horizons. While active strategies promise the possibility of beating the market, decades of empirical performance data favor low-cost passive tracking for most long-term buy-and-hold investors.
Understanding how these strategies differ and how automated index tracking functions helps you build a disciplined wealth engine.
Quick Takeaways
01Active investing uses human security selection and market timing to pursue higher-than-average market returns.
02Passive investing uses automated index rules to replicate a market benchmark at a low operating cost.
03Higher expense ratios and turnover costs in active funds create a steep fee drag that compounds against investor wealth over 10 years.
04According to S&P Dow Jones Indices' SPIVA (S&P Indices Versus Active) scorecards, roughly 80% to 90% of actively managed US equity funds have trailed their benchmark over 10- to 15-year periods.
What Is the Difference Between Active and Passive Investing?
The core difference in active vs passive investing lies in each approach's primary objective, management mechanism, and underlying cost structure.
Active management attempts to generate "alpha" returns above a market benchmark by buying undervalued securities and selling overvalued ones or holding cash during downturns.
Passive management accepts broad market returns ("beta") by holding the exact components of an index, eliminating stock-selection risk and minimizing management turnover. Fee ranges in the table below reflect typical US fund expense ratios reported in Morningstar's 2024 US Fund Fee Study.
Dimension
Active Investing
Passive Investing
Primary Objective
Outperform a benchmark index (generate alpha)
Match a benchmark index's return (capture beta)
Management Mechanism
Human portfolio managers and analyst teams
Automated rules and index tracking algorithms
Expense Ratios
High (~0.50%–0.85%+ per year)
Low (~0.03%–0.15% per year)
Tax Efficiency
Lower (frequent turnover triggers capital gains distributions)
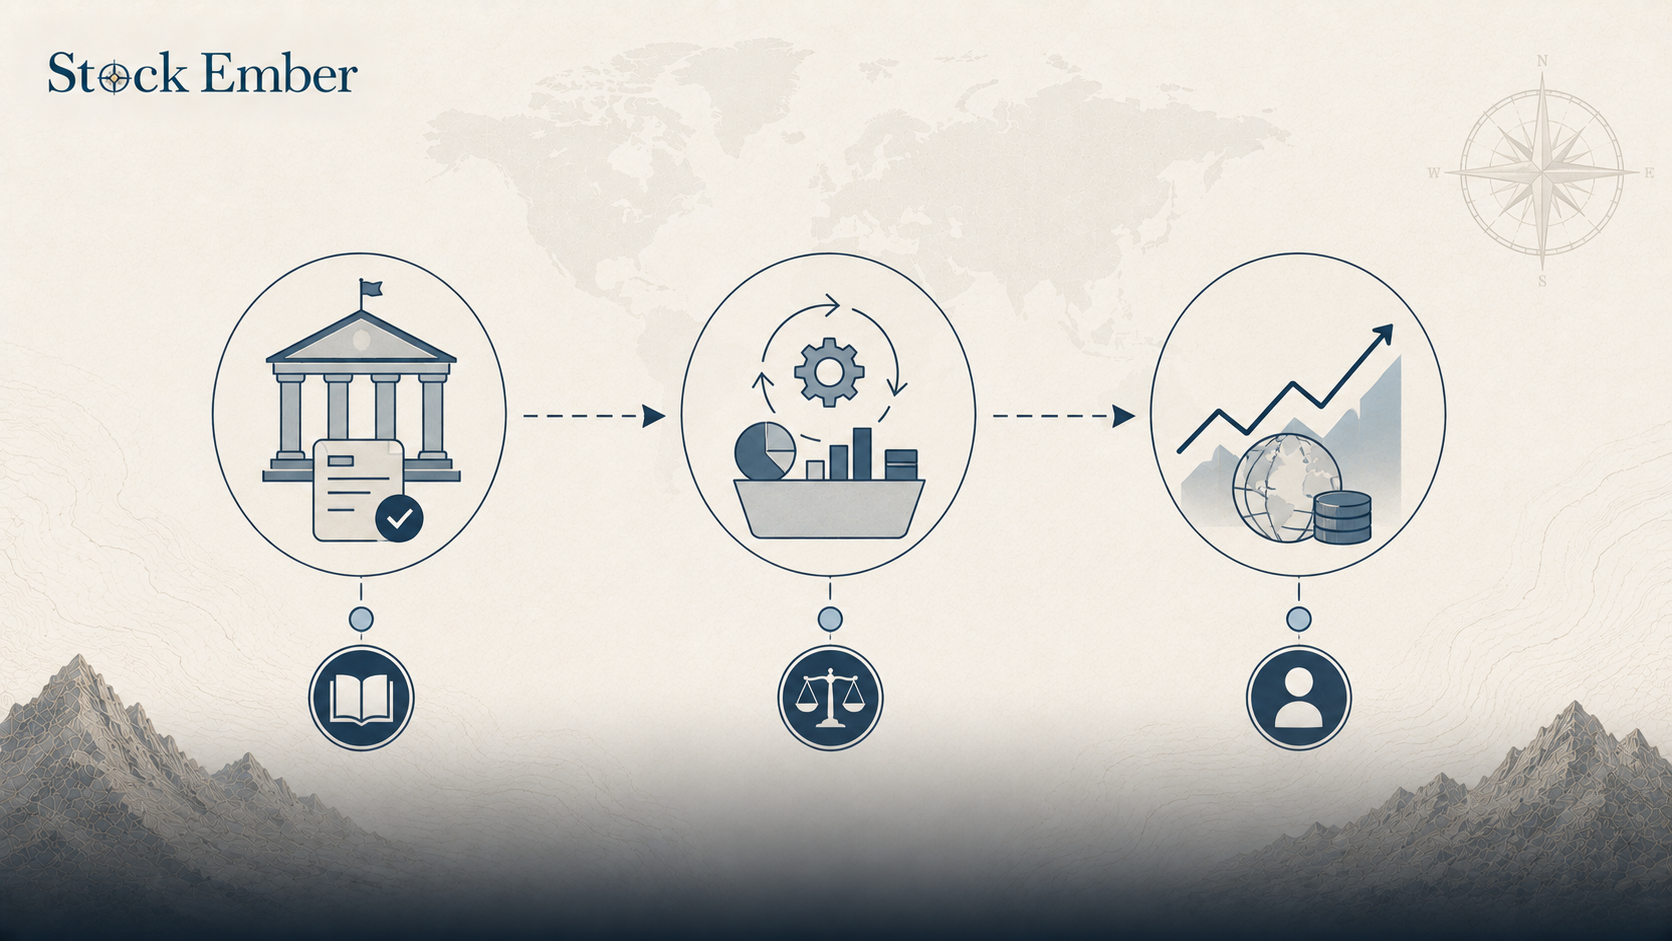
A common misconception is that passive index funds are completely unmanaged, leading beginners to ask who manages passive investing if no human stock picker is calling the trades.
In reality, passive investing is managed by strict, automated rules and specialized benchmark committees rather than individual fund managers. Independent index providers such as S&P Dow Jones Indices, MSCI, or FTSE Russell define the explicit inclusion rules for an index, including company market cap, liquidity, and country classification.
When you invest in a passive fund, portfolio managers use specialized computer algorithms to buy and sell securities solely to mirror the target benchmark. Rebalancing happens automatically on set calendar dates when companies enter or leave the index. By replacing human stock pickers with rule-based systems, this automated structure captures the core mechanics of passive investing, offering greater transparency and much lower operating fees.
Diagram showing how automated index providers and algorithms manage passive index funds.
The 10-Year Fee Advantage: How Costs Compound Against Active Returns
Management fees may look small on an annual report, but fee drag compounds silently against your capital over long investment horizons.
Consider a hypothetical $10,000 investment compounding over 10 years, assuming a constant gross annual return of 7.0%. This illustration is for educational purposes only; actual market returns vary from year to year, are not guaranteed, and any investment, including an index fund, can lose value:
Low-Cost Passive Index Fund (7.0% Gross Return minus 0.08% Expense Ratio = 6.92% Net Return): Grows to approximately $19,525 over 10 years.
Actively Managed Fund (7.0% Gross Return minus 0.75% Expense Ratio = 6.25% Net Return): Grows to approximately $18,335 over 10 years.
The active management fee markup erodes nearly $1,200 per $10,000 invested over a single decade without delivering any performance guarantee.
Furthermore, historical SPIVA scorecards consistently show that over 10- to 15-year periods, roughly 80% to 90% of active fund managers across major equity categories fail to beat their benchmark index. Paying higher fees for a strategy that statistically underperforms the market over time creates a structural handicap for long-term compounding.
Asset Allocation Across Stocks and Bonds
The active vs passive investing decision applies across all asset classes within your overarching asset allocation plan.
In highly liquid, heavily researched markets such as US large-cap equities, new information tends to be priced in quickly, which may make it difficult for active managers to consistently find mispriced stocks. In contrast, some investors seek active management in less efficient market niches, such as emerging market debt or specialized corporate bonds, hoping managers can navigate credit defaults.
However, when structuring your foundational asset allocation between bonds vs stocks, low-cost passive index funds provide broad, predictable market exposure for both growth equities and defensive fixed income. Holding total market index exchange-traded funds (ETFs) across both asset classes keeps total portfolio expense ratios near zero while capturing global market compounding.
Common Pitfalls for Active and Passive Investors
Understanding the common mistakes on both sides of the active vs passive investing debate can help prevent behavioral errors from undermining your returns.
Watch out for these three major traps:
Expecting Active Managers to Protect You in Market Crashes: Investors often assume active managers will pivot to cash before a market panic. In practice, cash drag, trading friction, and mistimed re-entry frequently cause active funds to capture downside losses while missing sudden market recoveries.
Turning Passive Index ETFs into Active Vehicles: Buying passive index ETFs but trading them frequently based on market headlines turns a low-cost passive instrument into a high-cost active trading habit.
Ignoring Tax Inefficiencies in Taxable Accounts: Active funds generate internal trading turnover that triggers annual capital gains distributions, generating unexpected tax liabilities even in years when the fund's net price drops.
In practice, many long-term investors find that passive investing isn't about giving up on high returns; it's about recognizing that fees and behavior are among the few factors they can actually control. Historically, accepting average market returns through broad index funds has put investors ahead of most actively managed funds over 10-year periods, although past performance does not guarantee future results.
Conclusion
Active investing relies on human stock selection and tactical timing to pursue market outperformance, but higher operating fees and tax friction create significant drag over long horizons. Passive investing uses automated index rules to deliver broad market returns at a fraction of the cost, making it a cost-efficient foundation that many investors use for multi-decade wealth building.
By establishing a low-cost, index-based portfolio, you eliminate manager risk and focus on the factors you can control. When you are ready to evaluate broad index funds and low-cost index ETFs, exploring our ETF reviews is a logical next step.
FAQ
5 questions
Why is passive investing often recommended for long-term investors?
Passive investing is widely recommended for long-term investors because it drastically reduces fee drag and turnover costs while delivering broad market returns. Historical SPIVA scorecards show that roughly 80% to 90% of actively managed equity funds fail to beat their benchmark indexes over 10- to 15-year horizons, making broad index tracking a higher-probability long-term strategy.
Who manages passive investing if there is no human stock picker?
Passive funds are run by portfolio managers who follow strict, rule-based processes rather than picking stocks. Index providers such as S&P Dow Jones Indices and MSCI set the index rules, and the fund adjusts its holdings when companies are added to or removed from the index or at scheduled reconstitution dates. Because most index funds weight holdings by market cap, their weights shift automatically with prices, so no trading is needed simply because market values change.
What are the primary fee differences between active and passive funds?
Passive index funds typically carry low expense ratios ranging between 0.03% and 0.15% per year because they require no active stock research team. Actively managed funds charge higher expense ratios, often 0.50% to 0.85% or higher, to cover research analysts, management salaries, and frequent trading turnover.
Do passive index funds protect investors during severe market downturns?
No, passive index funds do not try to time downturns or move to cash; they remain fully invested in the target index through all market cycles. While active managers have the flexibility to hold cash, historical data shows active flexibility rarely offsets high fee drag and cash-drag friction during sudden market recoveries.
Which strategy is more tax-efficient in a taxable brokerage account?
Passive investing is significantly more tax-efficient. Passive funds feature low portfolio turnover, which minimizes realized capital gains distributions. In contrast, active funds trade frequently, triggering taxable short- and long-term capital gains that are passed on to fund holders annually.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.