SIPC insurance is a statutory financial safeguard provided by the Securities Investor Protection Corporation that recovers missing stocks, bonds, and uninvested cash if an SEC-registered brokerage firm collapses. It offers baseline coverage up to $500,000 per customer registration capacity, including a $250,000 limit for cash claims. However, SIPC does not protect against investment losses, stock price drops, or market volatility.
SIPC insurance is statutory protection provided by the Securities Investor Protection Corporation that safeguards cash and securities up to statutory limits if a member U.S. brokerage firm fails financially.
When headline news reports a brokerage firm going under, investors naturally worry about the safety of their portfolio. However, many confuse brokerage protection with bank deposit insurance or assume it shields against falling stock prices. This guide explains how SIPC coverage works, its exact financial limits, and what it does not protect.
Quick Takeaways
01SIPC protects customer assets if a member U.S. broker-dealer becomes insolvent or goes into liquidation.
02The standard protection limit is $500,000 per customer capacity, which includes up to $250,000 for cash claims.
03SIPC insurance does not protect against investment losses, market drops, or declining stock values.
04Accounts registered under different capacities (such as individual, joint, and IRA) at the same broker qualify for separate $500,000 coverage limits.
What Is SIPC Insurance?
SIPC insurance refers to the protection provided by the Securities Investor Protection Corporation, a non-profit membership corporation created by the U.S. Congress under the Securities Investor Protection Act of 1970.
When you open a brokerage account, your shares and uninvested cash are held by a broker-dealer. If that brokerage firm suffers financial failure or commits accounting fraud that leaves assets missing, SIPC steps in to help restore those customer assets. It acts as an emergency safeguard that works to return your stocks, bonds, mutual funds, and cash, or transfer your portfolio to another solvent brokerage firm.
It is essential to understand that SIPC is not a government agency, nor is it commercial insurance you buy individually. Instead, nearly all SEC-registered broker-dealers are required by U.S. law to be SIPC members and pay into a central reserve fund.
SIPC Insurance Limits: How Much Protection Do You Get?
According to the Securities Investor Protection Corporation, the baseline sipc insurance limit is $500,000 per customer for missing cash and securities, with a sub-limit of $250,000 for uninvested cash claims.
This statutory cap applies per account capacity (or registration ownership type) at a single broker-dealer. If a broker fails and customer cash or stocks are unaccounted for, SIPC attempts to replace the exact shares held. If those shares cannot be recovered from the failed firm, SIPC pays out up to the $500,000 ceiling based on the cash value of the assets on the date a trustee is appointed.
How "Separate Capacities" Multiply Protection
Investors often wonder if holding multiple accounts at one brokerage firm caps their total coverage at $500,000. SIPC applies its limits separately to accounts held in different legal ownership capacities.
For example, an investor can hold the following accounts at the same broker:
An individual taxable account ($500,000 coverage)
A joint taxable account held with a spouse ($500,000 coverage)
A Traditional IRA retirement account ($500,000 coverage)
A Roth IRA retirement account ($500,000 coverage)
Because each of these represents a distinct legal capacity, each receives its own $500,000 limit, providing a total statutory protection umbrella of $2,000,000 across the four accounts at that single firm. However, opening two separate individual accounts at the same brokerage firm does not double your coverage; SIPC treats them as a single capacity and combines their balances under one $500,000 cap.
What SIPC Insurance Does NOT Cover
Understanding what SIPC excludes is just as important as knowing what it protects. SIPC protection is intentionally narrow, designed to fix broker failure, not bad investment decisions.
Market Losses and Price Drops
SIPC insurance does not compensate you if your stocks lose value, an ETF drops 30%, or a company goes bankrupt. Market risk is a built-in reality of investing in securities; SIPC only steps in if your broker disappears with your shares or fails to segregate your property properly.
Excluded Asset Classes
SIPC protection strictly applies to registered securities and cash held to buy securities. It explicitly excludes the following asset categories:
Commodity futures contracts and spot commodities
Foreign currency holdings
Fixed annuity contracts
Unregistered investment contracts
Cryptocurrencies and digital assets held on brokerage platforms
If a brokerage firm that offers both stock trading and cryptocurrency services fails, any missing crypto tokens fall entirely outside SIPC coverage.
SIPC vs. FDIC Insurance: Key Differences
Investors frequently confuse SIPC protection with FDIC insurance because both serve as safety nets for personal finance. However, they protect entirely different financial institutions and asset types.
The Federal Deposit Insurance Corporation (FDIC) is an independent U.S. government agency that protects bank deposits (such as checking, savings, and certificates of deposit) against bank failure up to $250,000 per depositor, per bank.
Feature
SIPC Insurance
FDIC Insurance
Entity Covered
SEC-registered broker-dealers
FDIC-insured banks
Primary Purpose
Restores missing stocks, bonds, and cash
Guarantees bank deposit balances
Total Coverage Limit
$500,000 per capacity
$250,000 per depositor
Cash Protection Limit
$250,000 sub-limit
$250,000 (full limit)
Protection Trigger
Broker bankruptcy or missing assets
Bank failure
Cash Sweep Programs
Many contemporary online brokerages offer "cash sweep" programs. Uninvested cash in your account is automatically swept into affiliated partner banks overnight. While the cash sits inside the bank, it gains FDIC insurance. Once the funds move back into the brokerage account to purchase stocks, they fall under SIPC protection rules.
Custodian Mechanics: Protection Before SIPC Gets Involved
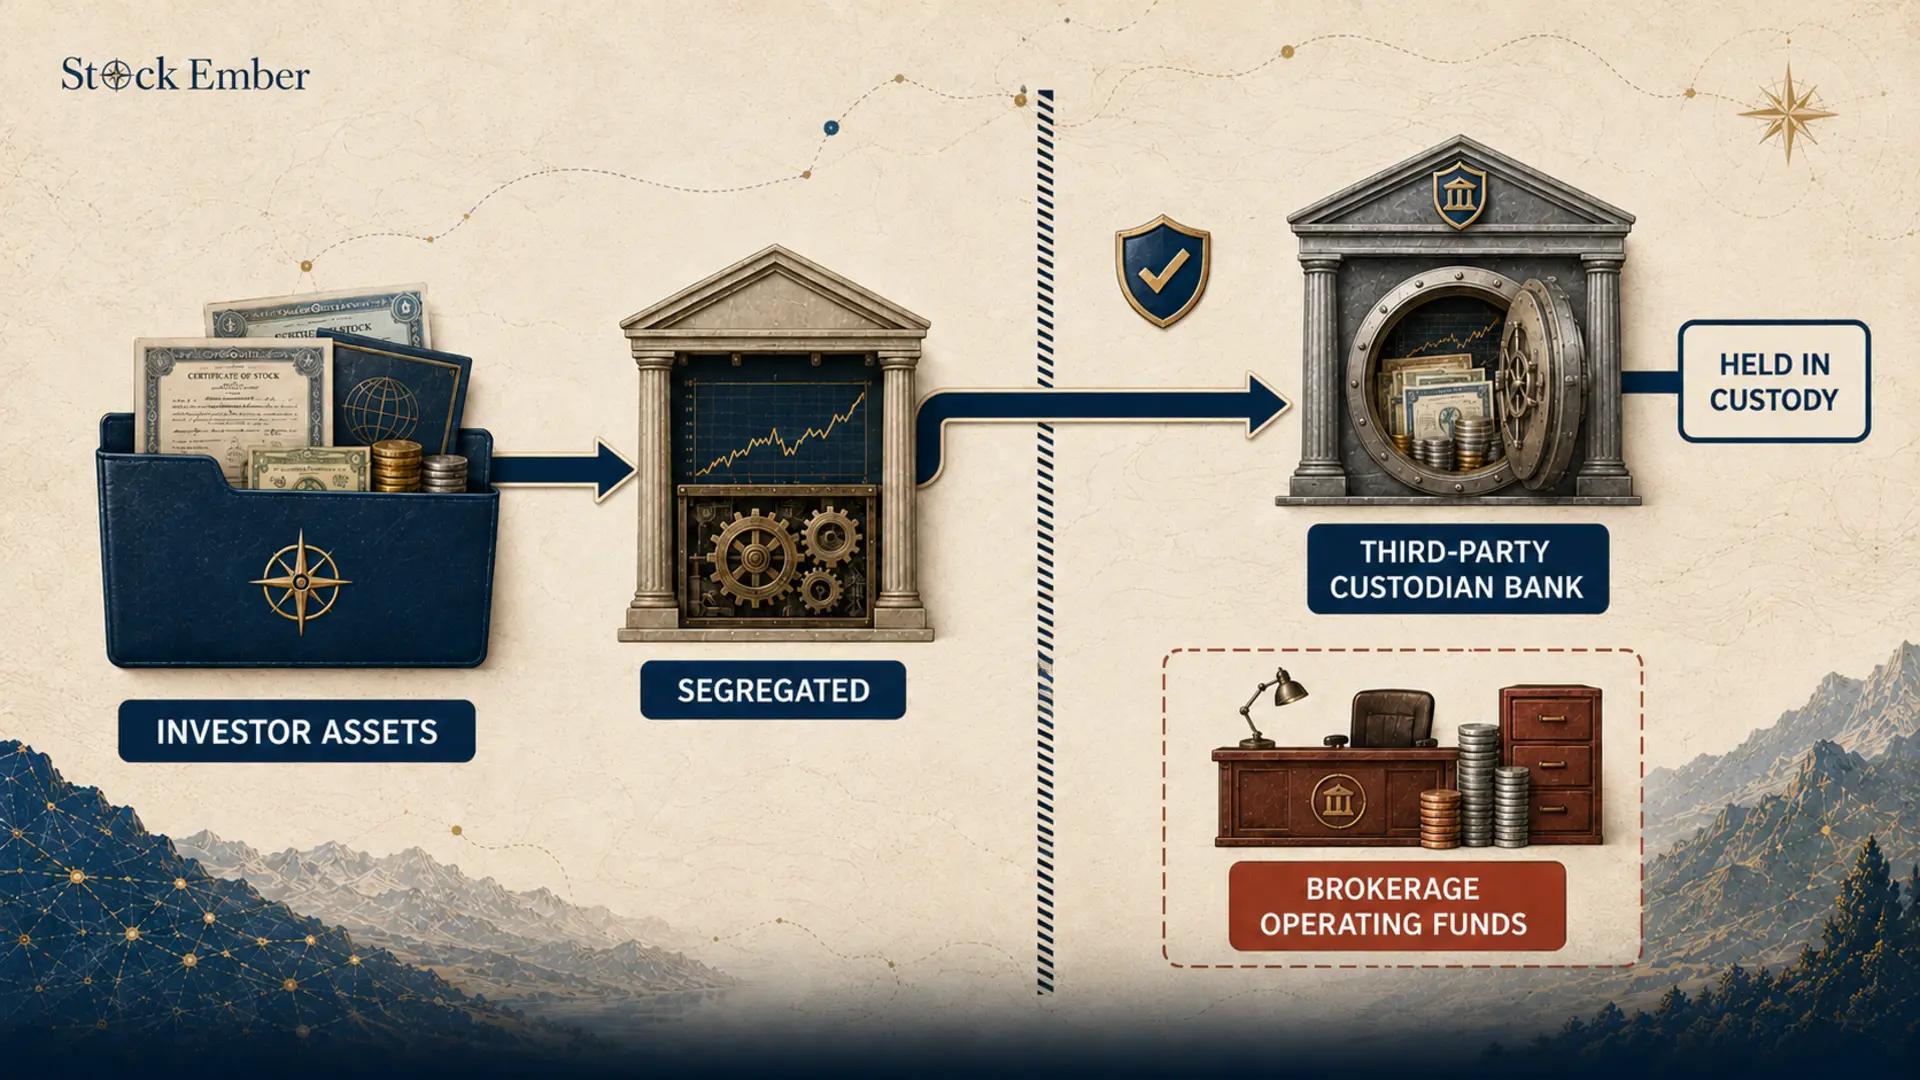
SIPC is actually a safety net of last resort. Before SIPC ever steps in, federal regulations require brokerages to safeguard investor property through strict asset segregation rules.
Under SEC Rule 15c3-3 (the Customer Protection Rule), broker-dealers cannot mix customer cash and securities with their own operating capital. Your shares are legally held separately at a third-party custodian bank.
Diagram illustrating customer asset segregation at a custodian bank
Because your assets sit safely at an independent custodian, if a brokerage firm files for bankruptcy, its creditors cannot claim customer stocks to pay off the firm's corporate debts. In most broker liquidations, a federal court appoints a trustee who simply transfers customer accounts intact to another healthy broker-dealer. SIPC reserve funds are only drawn down if audit records reveal that customer assets are missing or mismanaged.
Common Misconceptions About SIPC Coverage
Clearing up common misunderstandings helps investors build a practical risk perspective:
Misconception 1: "SIPC functions like auto or property insurance." Unlike standard insurance policies, you do not file a claim when an asset loses value. It only activates during broker-dealer liquidation.
Misconception 2: "Money market funds are covered as cash." Money market funds are mutual funds, not cash. They count toward the general $500,000 securities limit, not the $250,000 cash sub-limit.
Misconception 3: "SIPC guarantees complete safety against financial fraud." While SIPC covers stolen or missing assets caused by broker fraud, it does not compensate investors who fall victim to third-party scams or unauthorized account access due to weak personal passwords.
Conclusion
SIPC insurance provides a critical institutional safety net by protecting cash and securities up to $500,000 if a U.S. broker-dealer fails. By maintaining segregated accounts at custodian banks and enforcing strict ownership capacity limits, the framework ensures that firm insolvency does not erase your accumulated wealth. However, SIPC offers no protection against market drops or falling share prices, which remain standard risks of long-term investing.
When you are ready to evaluate platforms and their protective account structures, our Broker reviews & rankings are the place to start.
Investing always involves risk, including the loss of principal, and past protection events offer no assurance of future outcomes, so treat this breakdown as an educational guide rather than individual financial advice.
FAQ
4 questions
What does SIPC insurance actually protect?
SIPC protects cash and securities held in your brokerage account up to $500,000 (which includes up to $250,000 for cash) if your brokerage firm fails financially or goes out of business.
Does SIPC insurance protect my portfolio against market crashes?
No. SIPC does not cover losses caused by drop in investment value or bad financial decisions. It only steps in if the brokerage itself fails and customer assets are missing.
How does SIPC insurance differ from FDIC insurance?
FDIC insures bank deposits such as checking and savings accounts. SIPC covers investment accounts at registered brokerages. They protect different types of financial institutions.
What happens if my brokerage balance exceeds $500,000?
Many brokerages purchase additional private insurance, often called "excess SIPC" coverage, to protect customer balances above the standard $500,000 federal limit.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.