A REIT ETF is an exchange-traded fund that pools shares of publicly traded Real Estate Investment Trusts, providing instant diversification across commercial property sectors. It trades continuously on major exchanges, allowing investors to earn real estate income distributions without directly purchasing or managing physical properties.
A REIT ETF is an exchange-traded fund that invests in a basket of publicly traded Real Estate Investment Trusts. It gives you liquid exposure to commercial property markets through a single investment on a stock exchange.
Buying physical property requires significant capital, mortgage management, and direct landlord duties. A real estate fund strips away those physical hurdles while delivering regular income distributions. This guide explains how REIT ETFs function, how payouts work, tax considerations to keep in mind, and how they fit into a 10-year portfolio.
Quick Takeaways
01A REIT ETF pools shares of multiple real estate investment trusts, providing instant diversification across property sectors without direct physical property management.
02Cash distributions are often higher than standard equity dividends because underlying REITs must pay out at least 90% of their taxable income to shareholders.
03In standard taxable accounts, REIT ETF payouts are generally taxed as ordinary income rather than lower qualified dividend rates.
04Rising interest rate cycles can compress real estate valuations and increase borrowing costs for property expansion.
What Is a REIT ETF?
A Real Estate Investment Trust Exchange-Traded Fund (REIT ETF) is a fund that holds shares in publicly traded real estate companies. It trades on major stock exchanges just like an individual stock share.
Instead of purchasing a single apartment building or office park, you buy shares of a fund that owns dozens of property companies. The underlying companies own, operate, or finance income-generating real estate assets.
Holding funds provides a low-barrier entry point to real estate. For investors building a strategy around passive investing, real estate funds offer property market exposure without tenant management, property maintenance, or long acquisition timelines.
How a REIT ETF Works: Payout Mechanics and Property Sectors
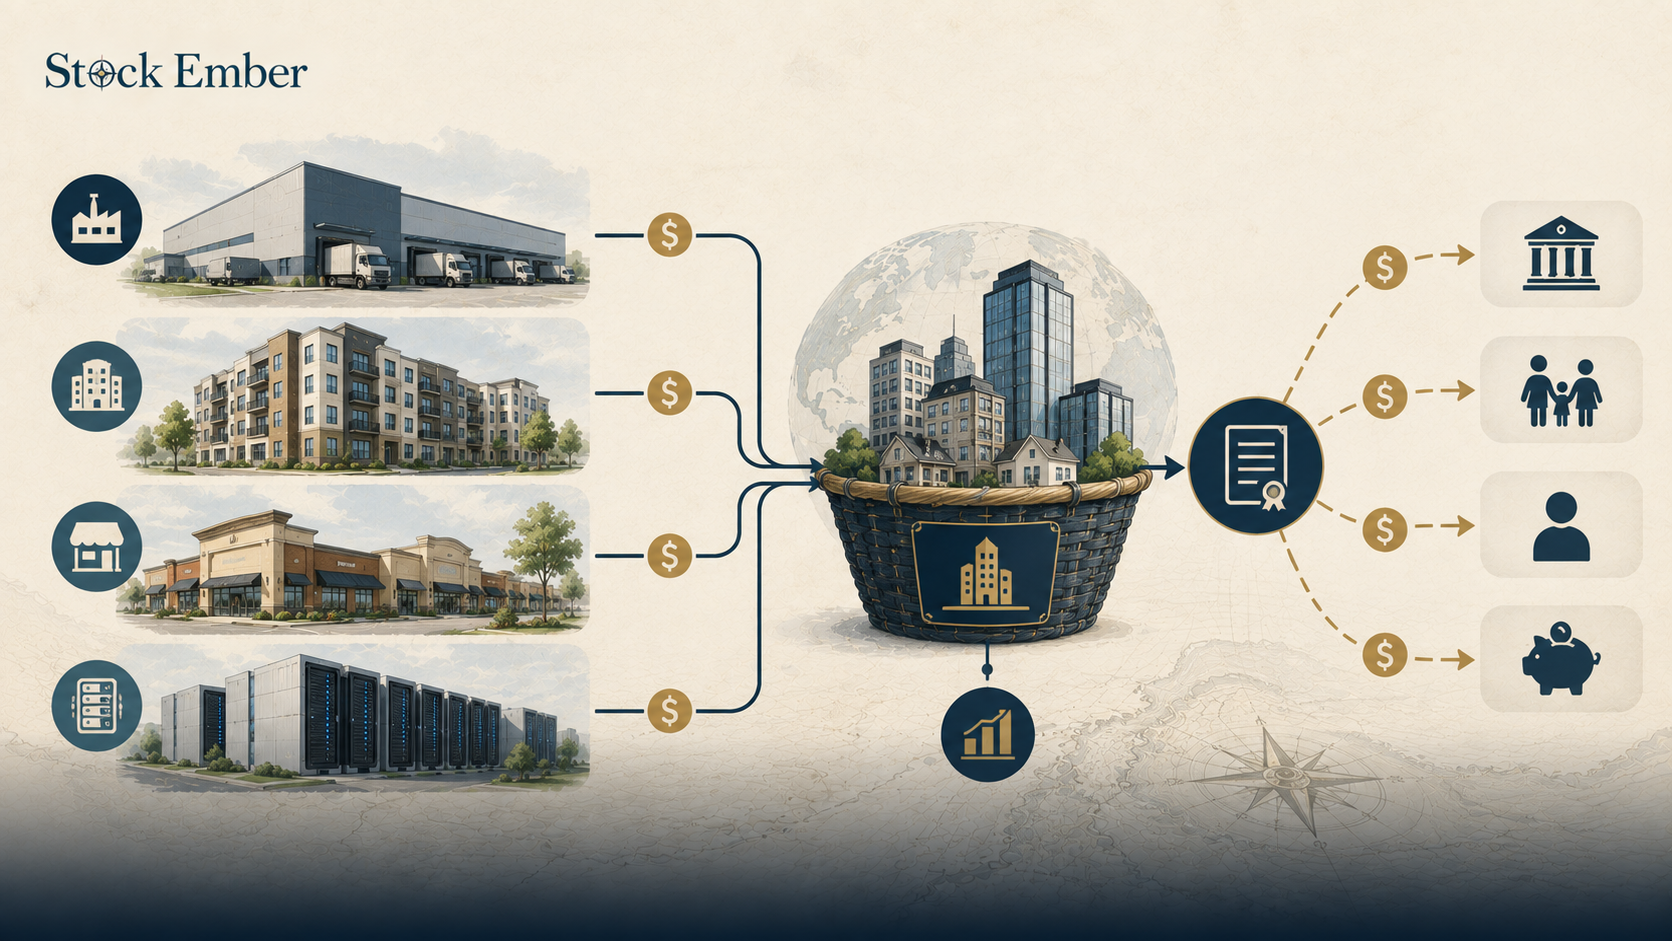
REIT ETFs collect rental income and capital gains from their portfolio companies and pass those revenues directly to shareholders as cash distributions.
To maintain REIT status under federal tax law, REITs generally must distribute at least 90% of their taxable income to shareholders each year. The ETF collects these corporate payouts and distributes them to fund holders on a monthly or quarterly schedule.
Diagram showing property sub-sectors feeding income payouts into an ETF.
Most REIT ETFs diversify across several major property sectors:
Industrial & Logistics: Distribution hubs, fulfillment centers, and storage warehouses.
Residential: Multi-family apartment complexes and single-family rental communities.
Healthcare: Medical office buildings, hospitals, and senior living facilities.
Data Centers & Towers: Facilities housing cloud servers and cellular infrastructure.
Retail: Shopping centers, grocery-anchored plazas, and standalone commercial sites.
While most funds focus on equity REITs, companies that own physical structures, a subset tracks companies specializing in real estate debt. If you want to evaluate funds that back property loans instead of owning buildings, reviewing how a mortgage REIT operates provides essential context.
REIT ETFs vs. Direct Real Estate & Broad Stock Index Funds
REIT ETFs sit between physical property ownership and broad market index funds. They trade direct control for daily market liquidity and low capital requirements.
Buying physical real estate offers localized control and potential mortgage leverage, but it requires significant capital down payments and hands-on maintenance. In contrast, a REIT ETF trades continuously during market hours, letting you buy or sell positions instantly.
Broad market stock index funds already contain real estate exposure. For example, a broad U.S. total market fund may already provide some REIT exposure, typically around 2% to 4% depending on the fund and index. Adding a dedicated real estate ETF increases your specific allocation to commercial property income.
Feature
Physical Real Estate
Dedicated REIT ETF
Broad Stock Index Fund
Initial Capital
High (down payment needed)
Low (cost of 1 share)
Low (cost of 1 share)
Daily Liquidity
Low (months to sell)
High (instant market hours)
High (instant market hours)
Real Estate Exposure
100% property focused
100% property focused
~2%–4% of total fund
Landlord Duties
Direct management
Zero
Zero
Payout Tax Rates
Net rental income / depreciation
Mostly ordinary income
Mostly qualified dividends
The 10-Year Cost and Tax Lens
Management fees and tax placement influence long-term total returns over a 10-year holding period.
Low-cost index REIT ETFs can have expense ratios below 0.15% annually, while actively managed real estate ETFs can charge 0.50% or more. On a $10,000 investment held for ten years, paying a 0.50% fee removes hundreds of dollars in wealth compared to a 0.12% fund due to compounding fee drag. Keeping fund costs low preserves more of your total return.
Tax efficiency is another factor. Unlike standard stock dividends that often qualify for lower capital gains tax rates, REIT ETF distributions are largely taxed as ordinary income. In a standard taxable brokerage account, those payouts face your top marginal income tax bracket.
In practice, many long-term investors find that placing income-heavy funds inside tax-advantaged accounts such as an IRA, helps shield distributions from annual tax drag, allowing payouts to compound fully over a decade.
Key Risks and Pitfalls to Watch
While real estate funds offer high cash distributions, they face distinct structural risks.
Interest Rate Sensitivity: When central bank interest rates rise, borrowing costs increase for property developers. Higher yields on low-risk bonds can also reduce the relative attraction of real estate payouts, pressing fund prices down.
Sector Concentration: Property trends do not affect all sectors equally. Changes in remote work impact commercial office buildings differently than online shopping trends affect logistics hubs.
The Yield Trap: A high distribution yield can reflect a dropping share price rather than business growth. If underlying real estate values fall, total returns can turn negative even while cash distributions remain high.
Conclusion
A REIT ETF provides long-term investors with a convenient tool for real estate diversification and regular cash distributions without physical landlord burdens.
Adding a targeted allocation can help smooth long-term equity returns and generate income. However, because broad index funds already hold real estate companies, a dedicated real estate fund is an optional sector emphasis rather than a required core asset.
Building a patient portfolio starts with broad market index funds and low holding costs. When you are ready to compare specific fund options and index mechanics, reviewing dedicated ETF reviews offers a practical next step for your research. Real estate market cycles shift and distribution yields fluctuate over time, so evaluate your tax accounts and long-term risk tolerance before adding sector funds.
FAQ
5 questions
What is a REIT ETF and how does it work?
A REIT ETF is an exchange-traded fund that buys shares of publicly traded companies that own or finance real estate. The fund collects rental income and capital gains from these underlying companies and distributes the revenue to ETF investors as regular cash payouts.
Are REIT ETF distributions taxed as ordinary income?
Yes, in standard taxable accounts, REIT ETF payouts are generally taxed at ordinary income tax rates rather than lower qualified dividend rates. Because underlying REITs avoid corporate tax by distributing at least 90% of their taxable income, the tax burden passes directly to individual shareholders.
What is the difference between an equity REIT ETF and a mortgage REIT ETF?
Equity REIT ETFs invest in companies that own, operate, and manage physical commercial properties like warehouses, apartments, and shopping centers. Mortgage REIT ETFs invest in companies that hold real estate debt, mortgages, and mortgage-backed securities, earning income primarily from loan interest.
Is a REIT ETF better than buying physical real estate?
Neither is universally better; they serve different investor needs. Physical real estate provides direct property ownership, localized control, and potential mortgage leverage, but requires heavy initial capital and hands-on landlord duties. A REIT ETF provides low minimum investment requirements, broad diversification, and instant daily liquidity without maintenance responsibilities.
Should you hold REIT ETFs in a taxable account or an IRA?
Holding REIT ETFs inside a tax-advantaged account like an IRA or 401(k) is often preferred because payouts are taxed as ordinary income. Shielding distributions inside a tax-deferred or tax-free wrapper prevents annual tax drag, allowing total returns to compound more efficiently over a long holding period.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.