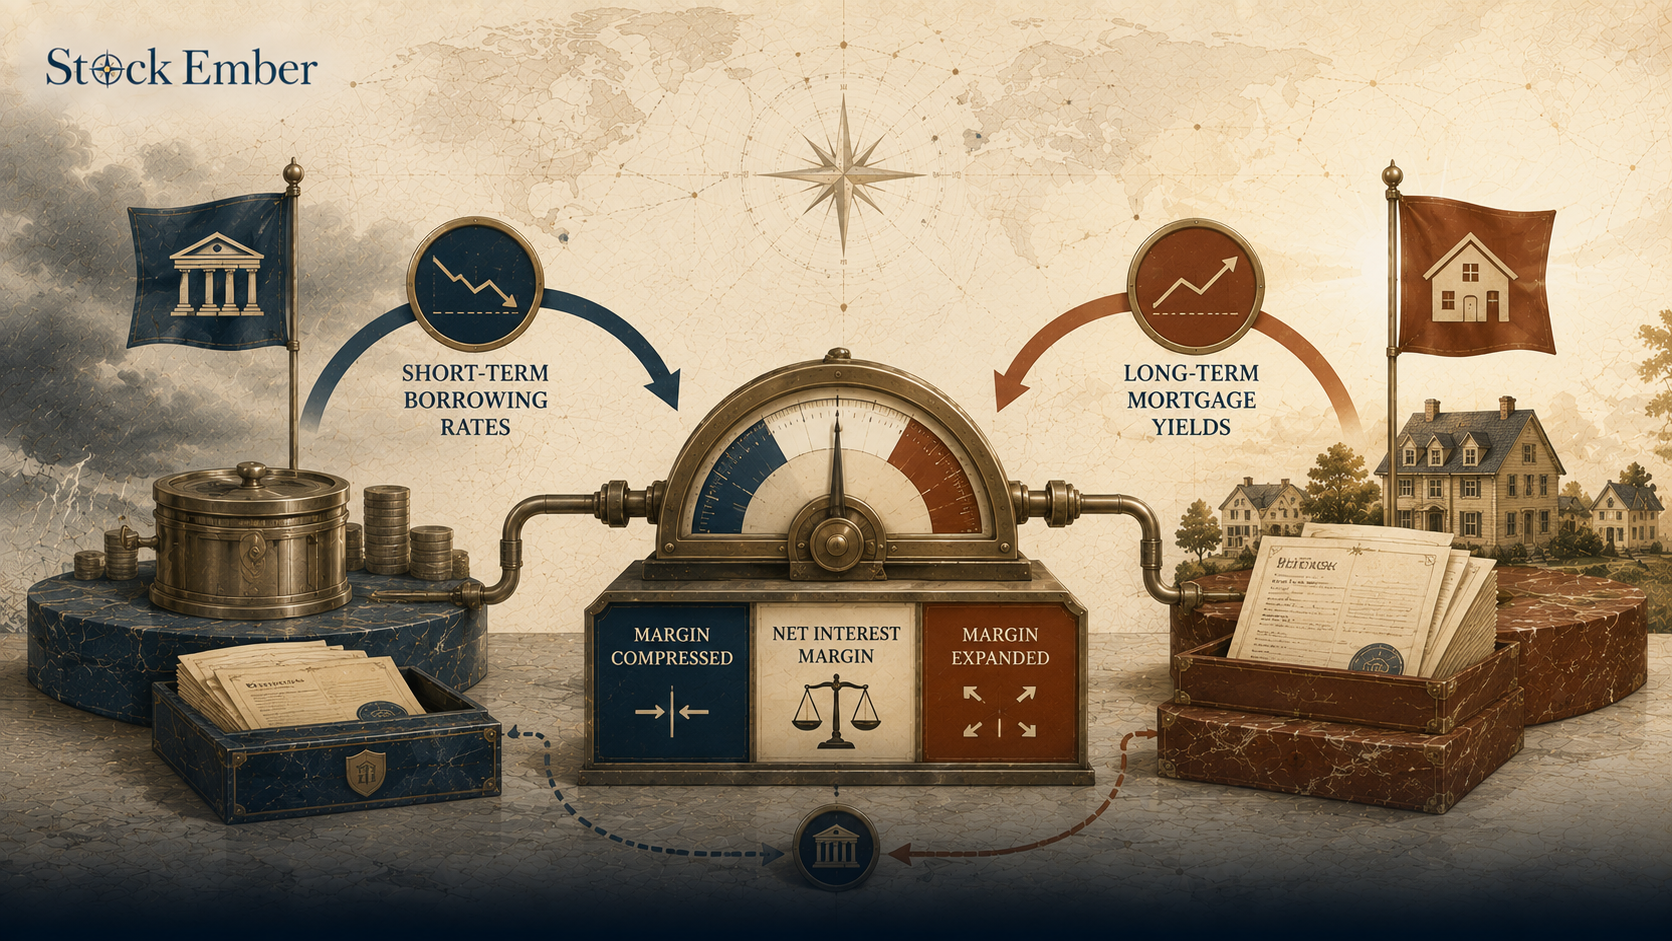
A mortgage REIT (mREIT) is a real estate investment trust that finances real estate by purchasing or originating mortgages and mortgage-backed securities rather than owning physical property. Mortgage REITs earn revenue through the net interest spread between short-term borrowing costs and long-term interest earned on mortgage holdings.
A mortgage REIT (or mREIT) is a real estate investment trust that finances real estate by purchasing or originating mortgage loans and mortgage-backed securities rather than owning physical property.
Investors seeking high dividend distributions often encounter mortgage REITs offering double-digit yields. However, these specialized financial entities operate very differently from traditional brick-and-mortar real estate trusts. This guide explains how mortgage REITs make money, how interest rate changes affect their cash flows, and what risks you face when holding them in a long-term portfolio.
Quick Takeaways
01Mortgage REITs earn income from the net interest spread between short-term borrowing costs and long-term interest earned on mortgage assets.
02Unlike traditional Equity REITs that collect property rent, mortgage REITs hold paper real estate debt and mortgage-backed securities.
03High distribution yields from mortgage REITs carry elevated risks, including extreme sensitivity to central bank interest rate hikes.
04Rising interest rates and yield curve inversions can cause book value decay, leading to dividend cuts over multi-year holding periods.
What Is a Mortgage REIT?
Understanding what is a mortgage REIT requires separating physical real estate from real estate debt. Under United States tax laws, a Real Estate Investment Trust (REIT) is a company that distributes at least 90% of its taxable income to shareholders annually in exchange for paying zero corporate income tax.
While most real estate trusts buy physical buildings, a mortgage REIT operates as a debt vehicle. Instead of purchasing apartment complexes, office towers, or warehouses, mREITs buy home loans, commercial mortgages, and mortgage-backed securities (MBS).
The mortgage REIT sector is divided into two primary categories:
Agency mREITs: These trusts invest primarily in residential mortgage securities backed by government-sponsored entities such as Fannie Mae or Freddie Mac. Because government guarantees limit credit default risk, Agency mREITs rely heavily on financial debt to boost interest returns.
Non-Agency mREITs: These trusts invest in commercial property loans or private residential mortgages that lack government backing. They carry higher credit default risk but offer higher interest rates on their underlying loans.
How Mortgage REITs Work in Practice
Mortgage REITs generate revenue through an investment mechanism known as the net interest margin, the difference between the interest rate earned on mortgage assets and the interest rate paid to borrow funds.
To generate income, an mREIT borrows cash at low short-term interest rates, often using short-term financing arrangements called repurchase agreements. It uses that capital to purchase long-term mortgages paying higher interest rates. The profit earned on this difference represents the net interest spread.
REIT Feature
Equity REITs
Agency Mortgage REITs
Non-Agency Mortgage REITs
Primary Assets
Physical buildings and land
Government-backed mortgage securities
Commercial loans & private mortgages
Revenue Source
Monthly tenant rent payments
Net interest spread on mortgage debt
High-yield mortgage interest
Primary Risk
Property vacancies and tenant defaults
Central bank interest rate increases
Loan defaults and borrower non-payment
The U.S. Securities and Exchange Commission notes that mortgage REITs invest in mortgages or mortgage-backed securities rather than physical real estate[cite: 1, 2]. Because mREITs hold financial paper rather than physical property, their underlying asset values adjust rapidly whenever market interest rates change.
Why mREITs Offer High Dividend Yields (and the Risks Attached)
When reviewing stock listings, income investors often notice mortgage REITs displaying dividend yields of 9%, 11%, or higher. These yields appear attractive compared to standard stock market payouts, leading many to consider them for cash flow generation.
These high payouts exist because mREITs combine pass-through distribution requirements with significant balance sheet leverage. To generate returns from thin interest spreads, an Agency mREIT might borrow six to eight dollars for every dollar of equity capital it holds.
However, chasing high yields without reviewing balance sheet mechanics can create financial traps. For investors following passive investing strategies through broad market funds, high-yield debt trusts represent specialized assets rather than simple bond replacements.
The Silent Drag: How Leverage, Rate Hikes, and Book Value Decay Erode Capital
While a 10% dividend yield sounds rewarding, multi-year total returns can prove disappointing if the underlying share price drops continuously.
Consider the ten-year total return impact of holding $100,000 in a mortgage REIT during a central bank rate-hiking cycle. If short-term borrowing rates rise faster than long-term mortgage yields, the net interest spread narrows or turns negative. To cover short-term financing costs, the mREIT must reduce its dividend payout.
Simultaneously, rising interest rates reduce the resale value of the existing fixed-rate mortgages held on the balance sheet. This process causes book value decay, lowering the trust's net asset value. Over a ten-year holding period, an investor receiving $10,000 in annual dividends might experience a $40,000 decline in principal value, resulting in poor compounding growth compared to broad market equity holdings.
In practice, many long-term investors find that tracking book value per share over five-year periods reveals whether an mREIT is generating real economic growth or simply returning capital.
Major Pitfalls and Market Risks to Watch
Holding debt-focused real estate trusts involves specific economic risks that do not apply to standard equity investments:
Interest Rate Spikes: When central banks raise benchmark interest rates, short-term borrowing costs rise immediately, squeezing net interest margins before long-term assets can adjust.
Yield Curve Inversion: If short-term interest rates rise higher than long-term rates, the cost of borrowing exceeds the yield on mortgage holdings, forcing mREITs to cut dividend payouts or liquidate assets.
Prepayment Risk: When interest rates fall rapidly, homeowners refinance their mortgages early. The mREIT receives its principal back early and must reinvest that cash at lower market yields.
To balance volatile sector-specific risks, long-term investors often favor diversified equity strategies. For example, comparing cap-weighted indexes to the S&P 500 equal weight index helps investors distribute equity concentration across five hundred large companies without over-exposing capital to leveraged financial sectors.
Diagram illustrating how net interest spread drives mortgage REIT income.
Conclusion
Understanding what is a mortgage REIT clarifies why these high-yielding financial trusts require careful risk evaluation. Mortgage REITs provide essential liquidity to housing markets by holding mortgage debt, but their profits depend on net interest margins and financial leverage. Because rapid central bank rate changes and yield curve shifts can shrink dividends and erode book values, mREITs serve as complex interest-rate bets rather than low-risk income substitutes.
When you are ready to evaluate broad-market index funds and low-cost income options for your long-term portfolio, our ETF reviews offer a practical next step.
Investing always involves risk of capital loss, and historical dividend distributions do not guarantee future payouts. Treat financial metrics as educational reference points to maintain discipline throughout your investing journey.
FAQ
5 questions
What is the difference between an equity REIT and a mortgage REIT?
Equity REITs buy and operate physical properties, earning revenue from tenant rent payments. Mortgage REITs hold paper real estate debt, earning revenue from the net interest spread between borrowing costs and mortgage interest.
How do mortgage REITs make money?
Mortgage REITs make money through net interest margin. They borrow capital at lower short-term interest rates using leverage and invest in higher-yielding, long-term mortgages or mortgage-backed securities.
Why do mortgage REITs offer such high dividend yields?
Mortgage REITs offer high yields because US tax rules require them to distribute at least 90% of taxable income to shareholders, combined with significant balance sheet leverage to magnify narrow net interest spreads.
What happens to mortgage REITs when interest rates rise?
When central banks raise short-term interest rates, borrowing costs rise immediately, shrinking the net interest spread and reducing net income. Additionally, rising rates reduce the resale value of existing fixed-rate mortgages, causing book value decay.
Are mortgage REITs suitable for long-term buy-and-hold investors?
Because mortgage REITs are sensitive to interest rate cycles, leverage friction, and yield curve inversions, they are volatile financial instruments rather than simple bond replacements for long-term buy-and-hold portfolios.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.