ETFs are taxed primarily when investors receive dividend or interest payouts and when they sell fund shares for a capital gain. Unlike traditional mutual funds, ETFs manage institutional transactions using an in-kind creation and redemption process that limits annual capital gains distributions to shareholders, helping reduce year-end tax drag in taxable brokerage accounts.
Exchange-traded funds (ETFs) are taxed primarily when investors receive dividend or interest payouts and when they sell fund shares for a capital gain.
Buying fund shares seems straightforward until tax season arrives and you start asking how are ETFs taxed on the payouts and sales that affect your net returns. Understanding how ETFs are taxed helps long-term investors keep more of their money compounding over time.
This guide covers how capital gains and distributions work, why the fund design limits annual tax hits, and how tax drag impacts a portfolio over a ten-year horizon.
Quick Takeaways
01In short, this is how ETFs are taxed: you owe taxes when you receive fund distributions or sell shares at a profit.
02Structural in-kind share redemptions help shield long-term investors from unwanted annual capital gains distributions.
03Holding shares longer than one year usually qualifies your capital gains for lower long-term tax rates.
04Different asset types, such as bond or commodity funds, follow distinct tax rules compared to stock funds.
05Limiting tax friction preserves compounding efficiency, but tax strategies cannot protect against market volatility.
The Two Primary Tax Triggers: Capital Gains and Distributions
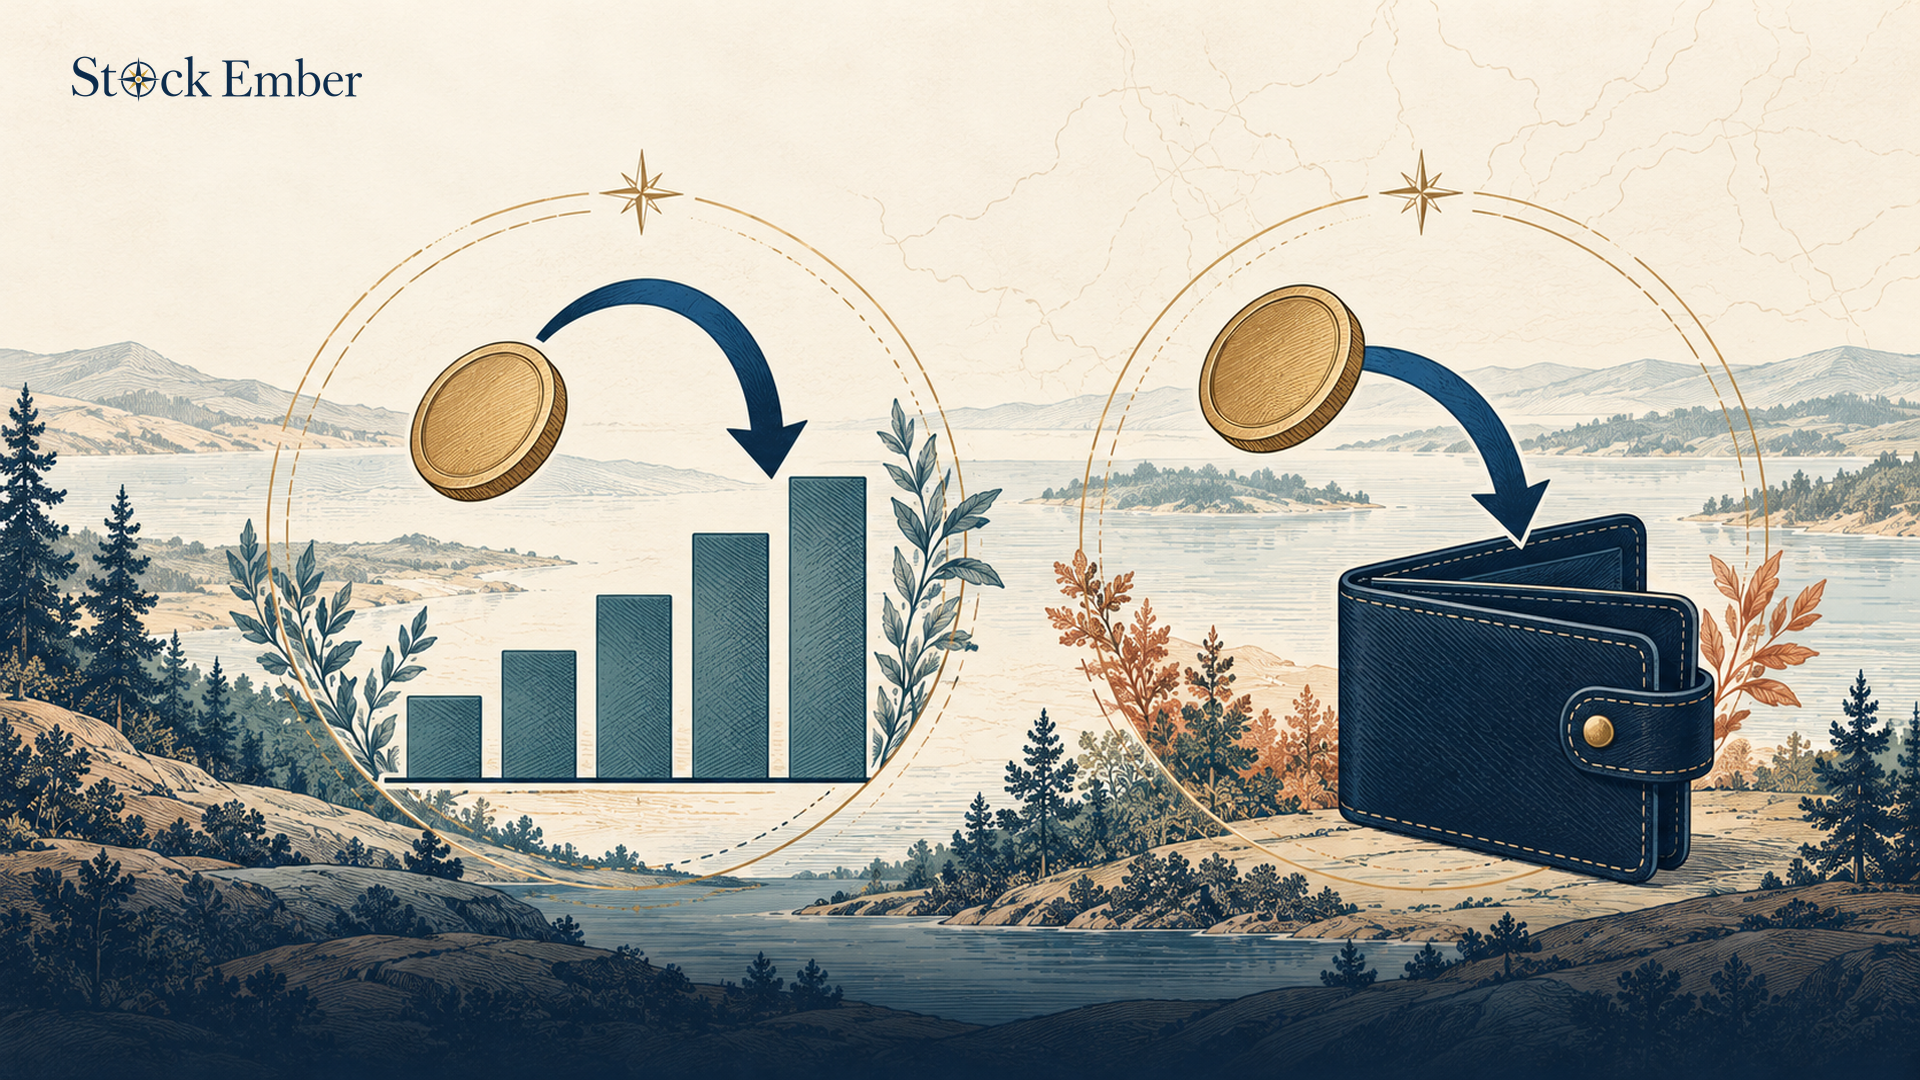
So how are ETFs taxed in practice? Taxes on fund holdings generally occur under two scenarios: receiving income payouts while holding shares, or realizing a profit when selling shares.
When you invest in what an ETF is, the underlying assets inside the fund often generate income. Stock funds collect cash dividends from companies, while bond funds collect interest payments. The fund manager passes these earnings through to shareholders as taxable distributions. Even if you automatically reinvest these payouts back into the fund, the tax obligation remains due for the year they were paid.
The second tax trigger occurs when you personally sell fund shares for more than your purchase price. The difference between your buying price (your cost basis) and your selling price represents a taxable capital gain. If you sell at a loss, that capital loss can offset other realized gains in your portfolio.
Taxes generally apply only in taxable brokerage accounts. Holding your shares inside tax-advantaged account wrappers—such as individual retirement accounts or workplace pension plans—allows your investments to grow without annual tax drag until withdrawal.
How In-Kind Creation and Redemption Minimizes Capital Gains
The primary structural advantage of index funds traded on exchanges lies in how fund managers handle daily inflows and outflows.
With traditional mutual funds, when investors cash out, the fund manager often must sell portfolio holdings to generate cash. If those holdings have grown in value, selling them triggers a capital gain. Mutual funds must pass these capital gains distributions down to all remaining shareholders at year-end, creating an unexpected tax bill even for investors who did not sell a single share.
In contrast, fund managers handle large trades through specialized institutional partners using an "in-kind" redemption process. Instead of selling internal stocks for cash, the manager transfers underlying shares directly to the institutional partner in exchange for fund shares. Because no cash changes hands inside the fund, this transaction does not trigger a taxable event for regular shareholders.
According to educational guidance from the U.S. Securities and Exchange Commission, this structural design allows fund holders to maintain far greater control over when they realize capital gains taxes.
Holding Periods and Asset Class Nuances: Stock vs. Bond and Commodity ETFs
How are ETFs taxed differently based on timing? How much tax you owe depends heavily on how long you hold your shares and the specific type of assets inside the fund.
For stock funds, holding your shares for longer than a year before selling generally qualifies your profit for long-term capital gains rates. These rates are lower than standard income tax brackets. Conversely, selling shares held for one year or less triggers short-term capital gains, which are taxed at higher ordinary income rates.
Different fund categories carry unique tax characteristics:
Fund Type
Tax Treatment
Equity Funds
Dividends paid by stock funds may qualify for lower tax rates if the fund meets specific holding period requirements.
Bond Funds
Interest distributions from fixed-income funds are usually taxed as ordinary income rather than lower dividend rates, though government bond funds may offer exemption from local or state taxes.
Commodity Funds
Funds holding physical metals or derivative contracts often follow specialized rules. For example, physical gold or silver funds may be categorized as collectibles, carrying higher maximum capital gains rates.
Because asset classes are taxed differently, placing income-heavy bond funds or high-yield equity funds inside tax-deferred accounts can preserve more of your total return.
The 10-Year Cost Lens: Quantifying the Impact of Tax Drag
Once you understand how ETFs are taxed, the next question is how much that adds up to over time. Tax drag refers to the portion of your portfolio's growth lost to annual tax payments. While a small percentage paid in taxes each year may seem minor, its cumulative effect over a decade can lower your total wealth.
Consider a simplified, hypothetical example of two investors who each place $10,000 into a fund that generates an 8% total annual return (comprising 6% capital growth and 2% dividend yield):
Scenario
Annual Tax on Dividends
Net Compounding Rate
Value After 10 Years
Investor A (Tax-Deferred Account)
$0
8.00%
≈ $21,589
Investor B (Taxable Account)
Illustrative 20% tax on dividend yield
7.60%
≈ $20,803
In this simple scenario, annual tax drag removes nearly $786 in compound growth over a single decade on a modest balance. Scaling this math across a larger diversified ETF portfolio over decades highlights why tax efficiency directly supports long-term wealth accumulation.
Note: These figures are for illustration only and do not represent guaranteed or expected real-world returns
Common ETF Tax Pitfalls to Watch
Even with a structurally efficient fund, investor habits can lead to unnecessary tax liabilities.
Ignoring Asset Location: Placing high-yielding dividend funds or bond funds in taxable accounts exposes cash flows to annual taxation. Matching asset types to appropriate account structures protects income from premature tax exposure.
Buying Right Before a Distribution: Purchasing shares immediately prior to an annual or quarterly dividend distribution creates an instant tax bill. You receive the cash payout, but the share price drops by an equivalent amount, effectively turning a portion of your principal into taxable income.
Chasing High Yields Without Strategy: Selecting funds solely for high current yields can backfire if those payouts are taxed at ordinary income rates, creating heavy annual tax drag that offsets capital growth.
Conclusion
Understanding how fund investments face taxation reveals why these vehicles remain popular for wealth accumulation. You pay taxes primarily when selling shares for a profit or receiving income distributions, but the in-kind redemption mechanism limits unwanted year-end capital gains payouts. By aligning your holding periods and placing heavy income producers in tax-advantaged accounts, you can limit tax drag and let more of your money compound over time.
When you are ready to evaluate individual funds and compare their structures, our ETF reviews provide clear details to help you build your strategy. Always remember that tax rules depend on your personal financial situation and local laws, and tax efficiency alone does not protect investments against market downturns.
FAQ
5 questions
Are ETFs taxed when you buy them or only when you sell them?
Purchasing ETF shares does not trigger a taxable event. You face taxes only when receiving income distributions while holding shares or when selling shares for more than your purchase price. Holding shares in tax-advantaged accounts can defer or eliminate these tax triggers until withdrawal.
Do you have to pay taxes on reinvested ETF dividends?
Yes. Reinvested dividends are subject to taxation in the year they are paid if held in a taxable brokerage account. Even if you do not withdraw the cash and automatically reinvest the funds into additional ETF shares, the tax authority considers the payout taxable income.
How do taxes differ between stock ETFs and bond ETFs?
Stock ETFs generate dividend income and capital gains, which may qualify for lower long-term rates if held for over a year. Bond ETFs generate interest payments typically taxed as ordinary income at personal rates, though government bond ETFs may offer local tax exemptions.
Can you sell ETF shares at a loss to lower your tax bill?
Yes. Selling ETF shares at a loss allows you to offset capital gains realized on other investments in the same tax year. If losses exceed gains, you can typically use a portion of the net loss to reduce ordinary taxable income, subject to wash-sale rules, which block the deduction if you buy back a substantially identical investment within 30 days.
Why do ETFs distribute fewer capital gains than mutual funds?
ETFs manage large transactions via an in-kind redemption mechanism. Institutional market makers exchange fund shares for underlying securities directly without selling assets for cash inside the fund, preventing internal capital gains realization.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Investing puts your capital at risk: the value of investments can go down as well as up, you may get back less than you invest, and past performance doesn’t guarantee future results. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.