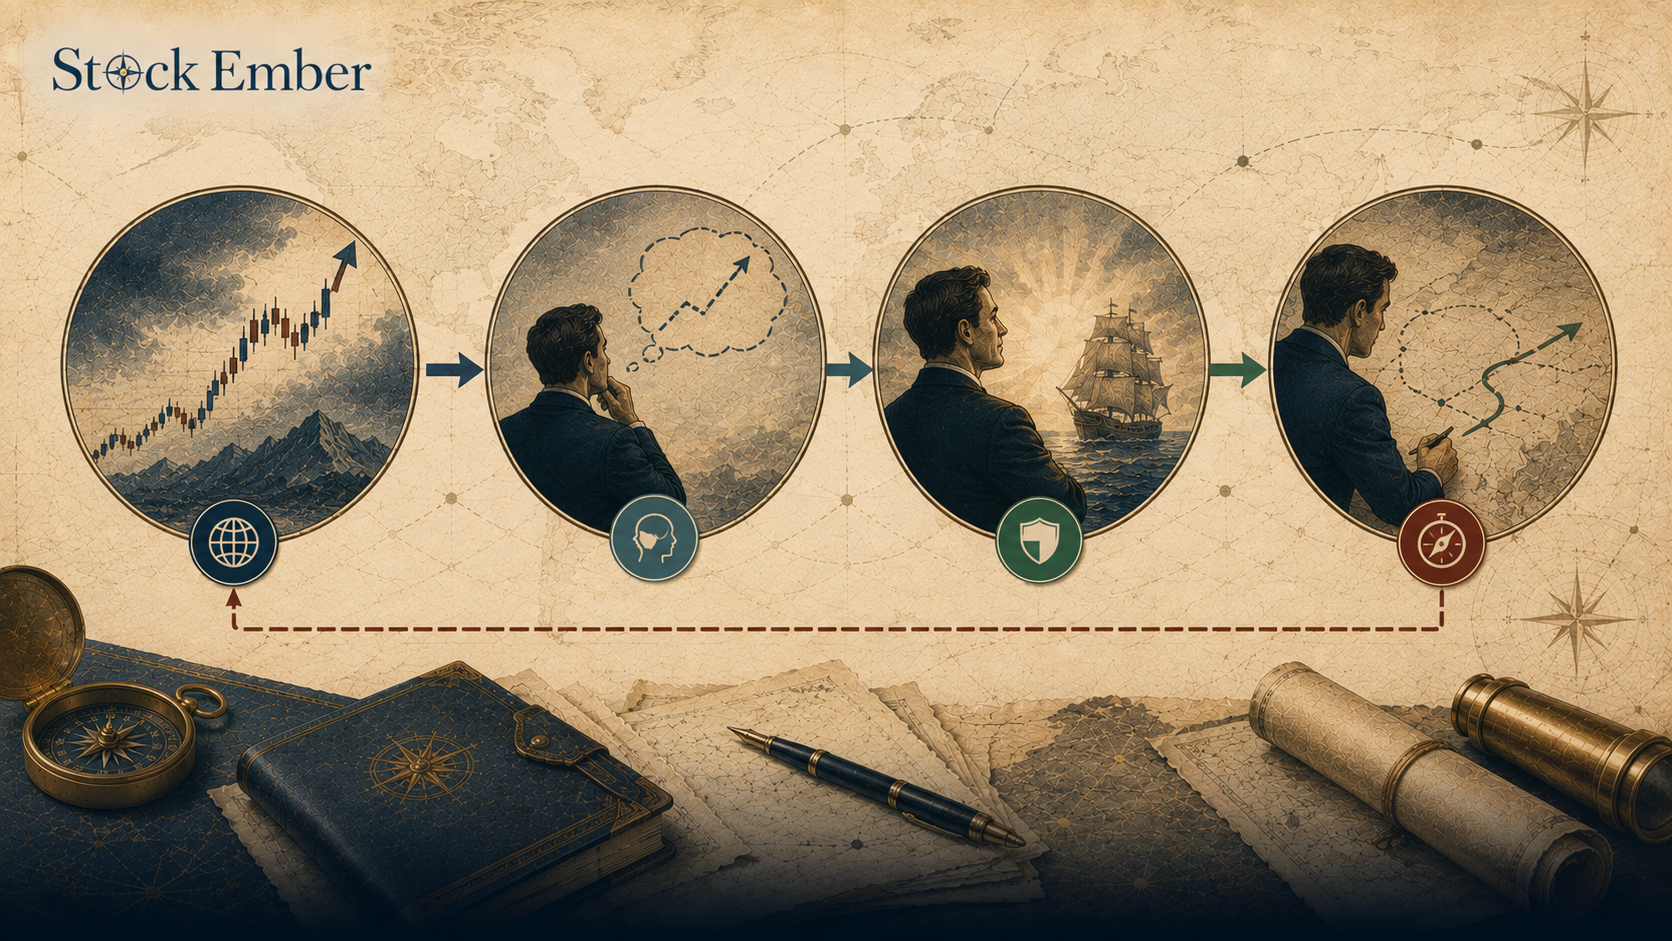
Hindsight bias is the cognitive illusion where investors view past market events as having been predictable before they occurred. Believing you foresaw past market moves creates false confidence, leading to strategy churning and long-term portfolio performance drag.
Hindsight bias is a cognitive illusion where people view past events as having been predictable before they happened. In investing, it leads individuals to believe they foresaw market movements that were actually uncertain at the time.
After a sharp market drop or a multi-year bull run, it is tempting to look back and think the outcome was obvious. However, rewriting your memory of past uncertainty distorts your judgment of future risk. This guide breaks down what hindsight bias is, how it harms your portfolio, and how to build a disciplined process to prevent it from quietly undermining your long-run returns.
Quick Takeaways
01Believing past market movements were predictable creates false confidence when forecasting future market trends.
02Rewriting your memory of past decisions hides investment mistakes, preventing you from learning from flawed logic.
03Reacting to past price patterns leads to strategy switching, creating tax drag and transaction fees over a 10-year horizon.
04Maintaining a written decision journal builds an honest record of your original expectations when you invest.
What Is Hindsight Bias?
To define hindsight bias in plain terms, it is the psychological tendency to believe, after an outcome is known, that you predicted or expected it all along.
In psychology, researchers often refer to this phenomenon as the "knew-it-all-along" effect. The meaning of this cognitive bias relies on three distinct cognitive steps: memory distortion (misremembering your original expectation), inevitability (believing the market move had to happen), and subjective foreseeability (feeling that you personally should have seen it coming).
When you look back at past market cycles, this mental shortcut tricks your brain into flattening past uncertainty. You forget the noise, the conflicting economic reports, and the personal hesitation you felt before making an investment choice. Instead, your mind constructs a clean narrative where the outcome appears obvious. Whether you are trying to understand the bias during a market crash or analyzing personal trading history, this memory distortion makes random market events feel predictable.
How Hindsight Bias Distorts Investor Decision-Making
Hindsight bias distorts investor decisions by replacing realistic risk management with false confidence in future market predictions.
Diagram illustrating how hindsight bias creates false overconfidence in investing.
When an index rebounds sharply or a sector experiences a deep drawdown (the drop in portfolio value from a peak), this bias makes the move seem logical after the fact. You might tell yourself that you knew tech stocks would recover or that energy prices were bound to fall.
This dynamic creates two distinct risks for buy-and-hold portfolio management:
False overconfidence: If you believe you successfully predicted past market turns, you begin to trust your intuition over a disciplined allocation plan. You may take concentrated positions or try to time market tops and bottoms.
Misattributed skill: When a bad process yields a positive outcome purely by luck, this pattern convinces you that your logic was sound. You repeat risky habits because the favorable outcome hides the original flaw in your decision.
In practice, many long-term investors find that reviewing past investments without written notes leads them to rewrite history, taking credit for random gains while blaming unexpected losses on bad luck.
The Hidden 10-Year Cost: Strategy Churning and Lost Compounding
The main financial cost of this bias comes from strategy churning, repeatedly altering your portfolio strategy in response to past market moves.
Consider a hypothetical $10,000 index portfolio modeled at an assumed average historical return of 7% per year over ten years, for illustration only. Left untouched, that portfolio could grow to approximately $19,670, though actual returns are never guaranteed and past performance does not predict future results.
However, suppose this mental shortcut tricks you every few years into believing you "knew" a specific sector or asset class was the right choice. Each time you switch strategies after an asset has already run up, you pay transaction costs, trigger taxable capital gains, and often sell the underperforming asset right before it recovers.
If these reactive changes lead to a modest 2% annual performance drag from bad timing and fees, your portfolio growth drops to 5% per year. After ten years, your $10,000 grows to only about $16,290. In this hypothetical scenario, that cognitive mistake costs you over $3,380, roughly 17% of the potential final wealth, a reminder that real-world returns and losses will always vary.
Hindsight Bias vs. Anchoring Bias in Behavioral Finance
Hindsight bias and anchoring bias are two distinct cognitive errors studied in behavioral finance that distort how you evaluate asset prices.
Quick comparison:
Hindsight bias: rewrites your memory of the past to make an outcome feel obvious after it happens.
Anchoring bias: fixates on one reference price, like your purchase price, when judging current value.
While hindsight bias alters your memory of past expectations to make outcomes seem obvious, anchoring bias works differently. It fixes your mind on a specific reference point, such as the purchase price of a stock or a recent market peak, when you're making current choices.
For instance, if a fund drops from $100 to $80, anchoring bias makes you fixate on the $100 price as its true value. If the price later rises to $120, hindsight bias takes over, convincing you that the recovery was bound to happen all along.
Both tendencies hinder sound decision-making. Anchoring keeps you tied to historical prices, while this bias creates a false belief that future price swings are easy to forecast. Educational materials from bodies like the CFA Institute point out that recognizing these mental shortcuts is necessary for maintaining portfolio discipline.
Practical Ways to Neutralize Hindsight Bias
You cannot eliminate cognitive biases entirely, but you can build a systematic process that limits their impact on your portfolio:
Keep an investment decision journal: Whenever you buy an ETF (exchange-traded fund), adjust your asset allocation, or rebalance, write down your exact reasoning, expected timeline, and the risks you identify. Re-reading your original notes years later provides an accurate record of your thoughts at that time.
Conduct pre-mortems: Before executing a major portfolio shift, ask yourself: "If this choice results in a loss three years from now, what will have caused it?" This practice forces you to evaluate risks before committing capital.
Use automated rebalancing rules: Establish clear rules for adjusting portfolio weights such as rebalancing once per year or when an asset class deviates by more than 5%. Automated rules reduce the temptation to act on intuitive predictions.
Conclusion
Recognizing this bias is key to maintaining a long-term investment plan. By documenting your decisions and evaluating your investment process rather than short-term outcomes, you protect your capital from unnecessary strategy switches. When you are ready to review low-cost building blocks for your portfolio, exploring our ETF reviews provides a clear look at broad index funds. This article is for educational purposes only and is not investment advice. All investing involves risk, including the possible loss of principal, and past performance is never a guarantee of future results.
FAQ
5 questions
What is a real-world example of hindsight bias in the stock market?
A classic stock market example occurs after a deep market crash or rapid recovery. Investors often look back at the shift and claim the outcome was obvious, forgetting the market uncertainty and contradictory economic reports present at the time. This illusion makes random market movements feel predictable in reverse.
What is the main cause of hindsight bias?
Hindsight bias is driven by memory distortion and the human tendency to build neat, logical stories after an event occurs. When new information arrives, your brain automatically alters past memories to align with current facts, making past decisions feel far more predictable than they actually were.
How does hindsight bias differ from overconfidence bias?
Hindsight bias involves rewriting your memory of past expectations to believe you predicted an outcome after it happened. Overconfidence bias, by contrast, is an exaggerated belief in your current abilities, knowledge, or future predictions. Hindsight bias frequently feeds overconfidence bias over time.
Why is hindsight bias dangerous for long-term investors?
Believing you can predict market shifts causes strategy churning, where you frequently buy and sell assets based on past trends. Over a 10-year period, these reactive switches generate transaction fees, tax liabilities, and bad market timing, significantly reducing long-term compound growth.
Can you completely eliminate hindsight bias?
You cannot completely eliminate cognitive biases, but you can neutralize their impact through systematic rules. Keeping a detailed decision journal, conducting pre-mortems before major asset shifts, and adhering to automated rebalancing rules prevent subjective memory shifts from disrupting your investment strategy.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.