A 401(k) rollover transfers accrued retirement savings from a former employer's workplace account into an IRA or new employer plan without incurring immediate income taxes or penalties. Conducting a direct trustee-to-trustee rollover preserves tax deferral and avoids the mandatory 20% tax withholding associated with indirect distributions.
A 401(k) rollover is the transfer of retirement savings from a former employer’s workplace retirement plan into an individual retirement account or a new employer's retirement plan without triggering immediate tax penalties.
When changing jobs, leaving an old workplace savings account behind often means dealing with ongoing administrative fees and limited investment options. Deciding what to do with those funds is an important step in preserving long-term investment growth. This guide breaks down the four main rollover options, step-by-step transfer mechanics, key IRS rules, and potential tax traps to watch for along the way.
Quick Takeaways
01A direct 401(k) rollover moves funds straight between account custodians, avoiding taxes and withholding penalties.
02Rolling over to an individual account gives you broader investment choices and lower fund fees than most legacy employer plans.
03Choosing an indirect rollover triggers mandatory 20% tax withholding and a strict 60-day window to deposit the funds.
04Cashing out early results in immediate income taxes plus a 10% tax penalty if you are under age 59½.
What Is a 401(k) Rollover?
A 401(k) rollover is the process of moving accrued retirement funds from a previous employer's tax-advantaged retirement plan into another eligible account. Understanding what is a 401k rollover comes down to knowing how tax-deferred assets move between financial institutions without triggering a taxable event.
When you participate in a workplace 401(k), your contributions and investment gains grow tax-deferred. When you leave that employer, the account remains intact, but you can no longer add new contributions. Moving those assets allows you to maintain continuous tax advantages while consolidating your savings.
For investors accustomed to international account wrappers, a 401(k) operates similarly to an employer pension in other markets, whereas rolling over into an individual retirement account offers flexibility comparable to a tax-advantaged wrapper like a Stocks and Shares ISA or personal pension.
In the US tax system, pre-tax contributions from a Traditional 401(k) roll into a Traditional IRA or pre-tax employer plan, keeping your money tax-deferred until withdrawal. Post-tax contributions from a Roth 401(k) roll directly into a Roth account, preserving future tax-free withdrawals.
Your 401(k) Rollover Options
When leaving a job, you generally face four primary 401k rollover options for managing your existing balance:
Leave the account with your old employer: If your plan balance exceeds minimum account thresholds (typically $5,000), you can usually keep the money where it is. However, you cannot make further contributions, and you may face higher administrative maintenance fees.
Roll over to your new employer’s 401(k): If your new workplace plan accepts transfers, moving old funds into the new plan consolidates your retirement savings under one umbrella.
Roll over to an Individual Retirement Account (IRA): Moving assets into a traditional IRA or a Roth IRA provides broad investment control. You gain access to individual stocks, low-cost index ETFs, and broad market assets that workplace plans rarely offer.
Cash out the balance: Withdrawing cash removes your savings from the market entirely. Doing so triggers immediate federal and state income taxes, plus a 10% early withdrawal penalty if you are under age 59½.
How to Roll Over a 401(k): Direct vs. Indirect
Knowing how to rollover 401k assets safely requires choosing between two main transfer methods: a direct transfer or an indirect transfer. Learning how to rollover a 401k correctly ensures your money stays protected from unexpected IRS tax bills.
Direct Rollover (Trustee-to-Trustee)
In a direct rollover, your former plan administrator transfers your money directly to your new IRA or employer account custodian. The funds move electronically or via a check made payable directly to the receiving custodian for your benefit (for example, "Fidelity, FBO John Doe").
Because you never hold the cash yourself, no income taxes are withheld, and the entire account balance continues compounding uninterrupted.
Indirect Rollover (The 60-Day Window Trap)
In an indirect transfer, your old 401(k) administrator issues a check directly in your name. Once you receive the funds, you have exactly 60 calendar days to deposit the full amount into a new eligible retirement account.
However, federal tax rules require the administrator to withhold money upfront. Per IRS rollover regulations, your former employer must apply 20% mandatory tax withholding on any indirect distribution.
To roll over the complete balance and avoid penalties, you must make up that 20% difference out of your own pocket when depositing funds into the new account. If you miss the 60-day window or fail to replace the withheld 20%, the missing amount counts as an early distribution subject to income tax and a 10% penalty.
How to Roll Over a 401(k) to a New Employer
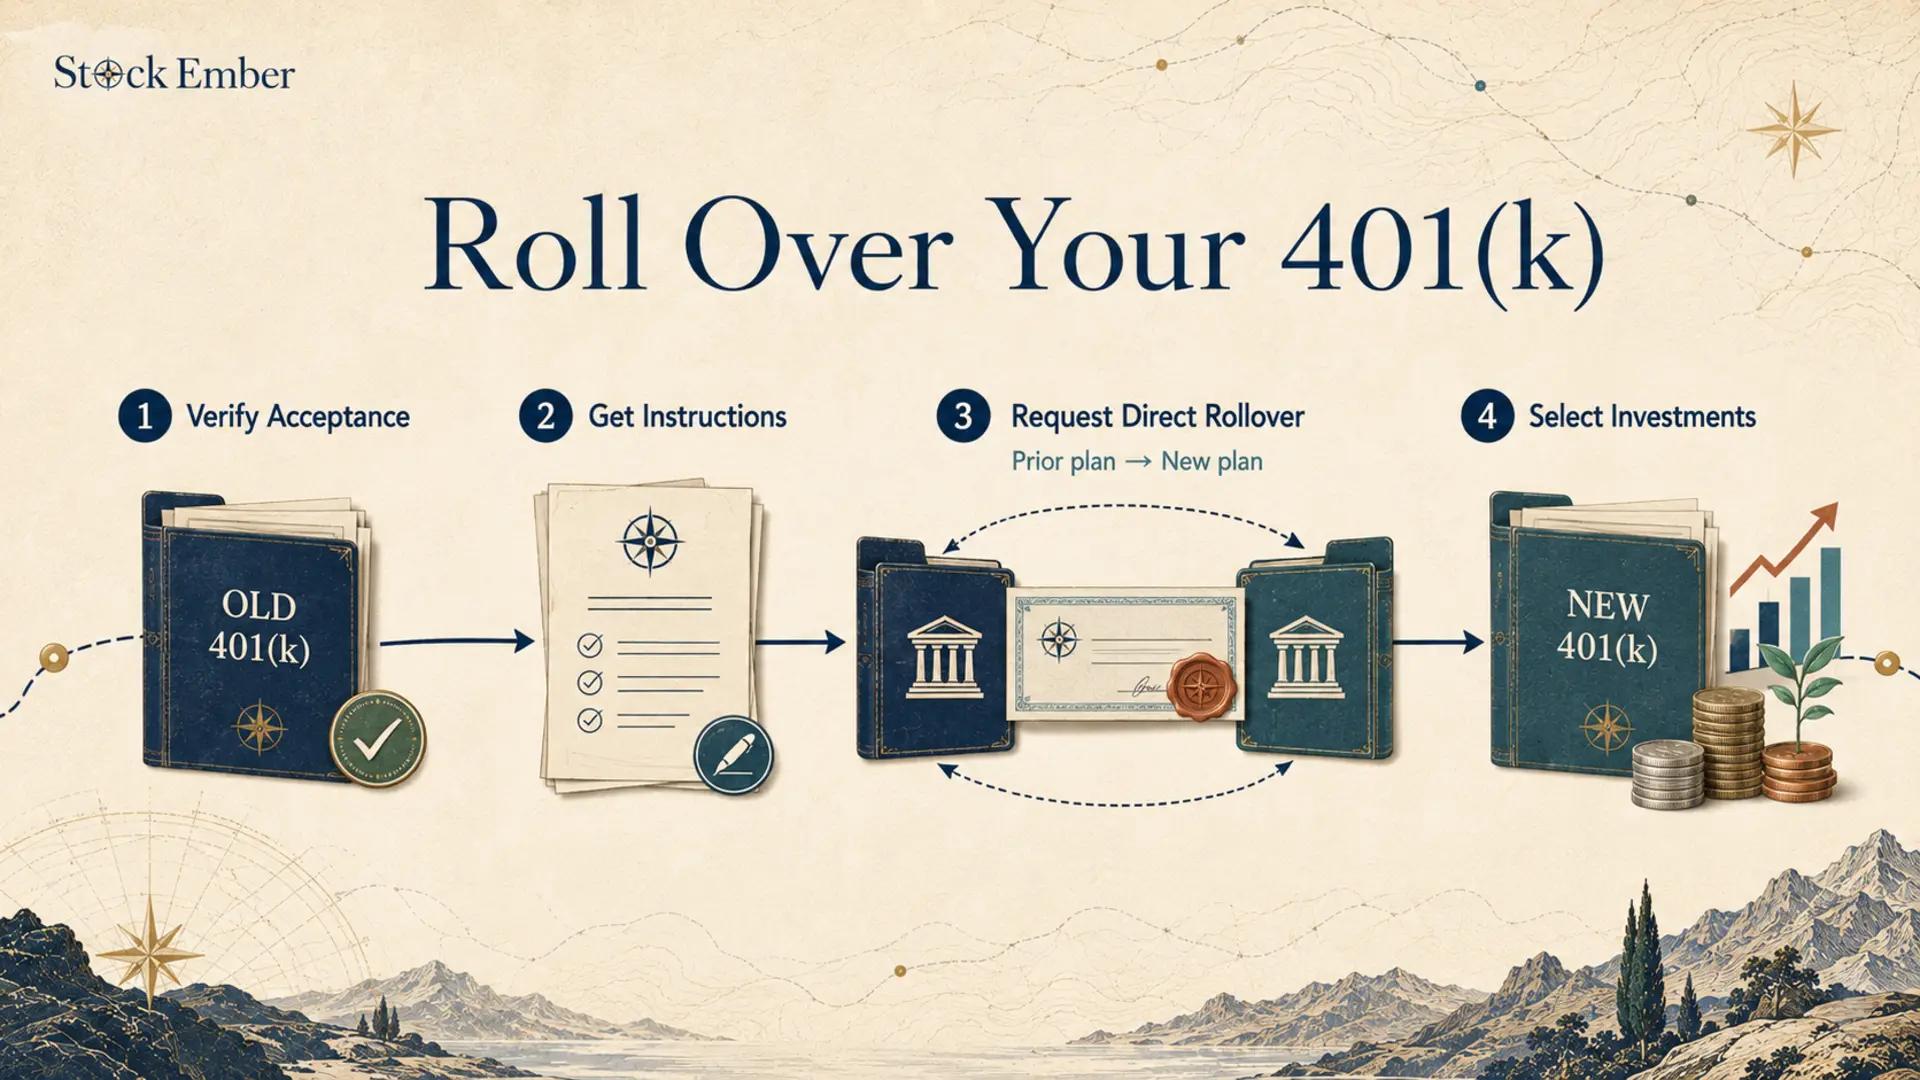
Step-by-step workflow showing how a 401(k) rollover to a new employer account works.
If you prefer keeping your investments under a single workplace umbrella, learning how to rollover 401k to new employer accounts involves a few administrative steps:
Verify plan acceptance: Confirm with your new HR department or plan provider that the current plan accepts "roll-ins" from prior qualified plans.
Request rollover paperwork: Obtain transfer instructions and forms from your new 401(k) custodian.
Contact your prior plan administrator: Request a direct rollover distribution and provide the receiving custodian's exact payment instructions.
Select your new investments: Once the funds land in your new account, assign those dollars to your chosen plan investment options.
Completing a 401k rollover to new employer plans makes sense if your current employer offers low-fee institutional index funds. It also keeps all tax-deferred workplace savings in one central login.
The 10-Year Cost Impact: Old Plan Fees vs. Rollover Control
Keeping legacy retirement accounts open across multiple former employers often means paying ongoing administrative fees and higher investment management expenses.
Workplace 401(k) plans frequently charge annual administrative fees, recordkeeping expenses, and fund expense ratios ranging from 0.80% to 1.20% per year. By contrast, an individual account gives you direct access to broad-market index ETFs with expense ratios as low as 0.03% to 0.08%.
Consider an example with round numbers:
Suppose you have a $100,000 balance from an old job.
Leaving that money in a former plan paying 1.00% in combined annual fees means paying roughly $1,000 every year in administrative and fund costs.
Moving that same balance into an account with access to low-cost index funds charging 0.05% in fees drops your yearly expense to just $50.
Over a 10-year holding period, that 0.95% annual difference compounds significantly. Paying higher fees takes thousands of dollars directly out of your portfolio—money that would otherwise remain invested to build compound growth over time.
Understanding account costs is a core topic across accounts and tax planning, where minimizing fee friction protects long-term compounding.
Key Traps to Watch: Rule of 55, NUA, and ERISA
Before initiating a transfer, evaluate three critical edge cases that can impact your retirement strategy:
The "Rule of 55" Penalty Exemption
If you leave or lose your job during or after the calendar year you turn 55, IRS rules allow you to take penalty-free distributions from your current employer’s 401(k). If you roll those funds into an IRA, you forfeit this protection and must wait until age 59½ to make withdrawals without a 10% penalty.
Net Unrealized Appreciation (NUA) for Company Stock
If your old 401(k) holds highly appreciated company stock, rolling those shares directly into an IRA treats all future distributions as ordinary income. Using NUA rules allows you to transfer company stock to a taxable brokerage account, paying ordinary income tax only on the original cost basis while taxing the growth at lower long-term capital gains rates.
Asset Protection Differences
Workplace 401(k) plans receive unlimited federal protection against legal judgments and creditor claims under the Employee Retirement Income Security Act (ERISA). IRAs receive strong federal bankruptcy protection up to statutory limits, but general lawsuit protections for IRAs depend on individual state laws.
Conclusion: Making the Right Move for Your 401(k) Rollover
Managing an old 401(k) requires evaluating your fee structure, available investment options, and legal protections. For many investors, completing a direct rollover to an individual account or a low-cost workplace plan simplifies management and reduces ongoing costs. Taking control of legacy balances ensures every dollar continues working toward your long-term goals.
When you are ready to compare custodians and platform options, our broker reviews & rankings provide detailed evaluations to help you choose the right account provider.
Investing always involves risk to your capital, and past performance does not guarantee future results. Treat this guide as educational information to inform your financial planning rather than personalized tax or investment advice.
FAQ
3 questions
What happens if I miss the 60-day 401(k) rollover window
Missing the 60-day window on an indirect rollover causes the IRS to classify the distribution as an early withdrawal. The entire un-deposited amount becomes subject to ordinary income taxes, plus a 10% early withdrawal tax penalty if you are under age 59½. Limited hardship waivers exist through the IRS, but avoiding indirect transfers entirely is the safest approach.
Should I roll over my old 401(k) into a Traditional IRA or a Roth IRA?
Rolling a Traditional 401(k) into a Traditional IRA maintains tax deferral with zero immediate tax liability. Moving pre-tax 401(k) funds into a Roth IRA triggers a Roth conversion, requiring you to pay ordinary income tax on the entire converted balance in the tax year of the transfer. Choose based on your current tax bracket versus expected future tax rates.
What is the main difference between a direct and indirect 401(k) rollover?
In a direct rollover, funds transfer directly between financial custodians without you touching the cash. In an indirect rollover, the plan provider issues a check payable to you, withholding 20% for federal income tax. You must deposit the full sum—replacing the withheld 20% out-of-pocket—into a new account within 60 days to avoid tax penalties.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.