Mental accounting is a cognitive bias where investors categorize money into separate mental accounts based on its source or intended purpose. Because money is strictly fungible, meaning every dollar carries identical economic value, treating funds differently leads to distorted risk management, emotional windfall spending, and lower total returns.
Mental accounting is a cognitive shortcut where people treat identical units of money differently based on where the cash came from, where it is held, or how it is intended to be spent.
You might carefully budget your monthly salary while casually spending a cash tax refund on an impulse purchase, even though both dollars have equal purchasing power. For long-term investors, this psychological tendency creates hidden portfolio risks and sub-optimal returns. This guide breaks down how mental accounting works, why it distorts risk management, and how to view your assets as a single economic engine.
Quick Takeaways
01Mental accounting leads investors to treat identical dollars differently based on their source or category.
02Money is strictly fungible, meaning every dollar in a portfolio carries identical economic value regardless of its origin.
03Partitioning funds into separate "safe" and "play" buckets masks total portfolio risk and reduces long-term return potential.
04Evaluating all investments as one unified engine helps prevent emotional spending of windfalls and dividends.
What Is Mental Accounting?
Mental accounting is the behavioral finance concept describing how human brains subjectively categorize money into separate accounts rather than treating all capital as a single pool. First identified by Nobel laureate Richard Thaler, this psychological framework explains why people set up mental "buckets" for different sources of money. For instance, you might view income from your main job as "hard-earned," while treating a work bonus or dividend check as "play money."
In economics, money is strictly fungible. Fungibility means that every single dollar has the exact same value and purchasing power as any other dollar, regardless of how you obtained it or where you store it. A $100 bill earned from overtime labor buys the exact same goods as a $100 dividend payout or a $100 lottery win.
When you practice mental accounting, you break the law of fungibility. You assign different emotional value, risk limits, and spending rules to different buckets of cash. While this mental shortcut can help families stick to basic household budgets such as keeping rent money separate from dining-out cash, it creates serious inefficiencies when applied to portfolio management.
The CFA Institute highlights this bias as a primary driver of irrational asset management. The foundational concepts of behavioral financeexplain how these cognitive habits lead investors away from sound, evidence-based strategy.
How Mental Accounting Works in Everyday Investing
In everyday investing, mental accounting operates by assigning different values or risk tolerances to money depending on its source or intended purpose. Human psychology tends to group investment capital into three common mental categories: core savings, future goals, and speculative cash.
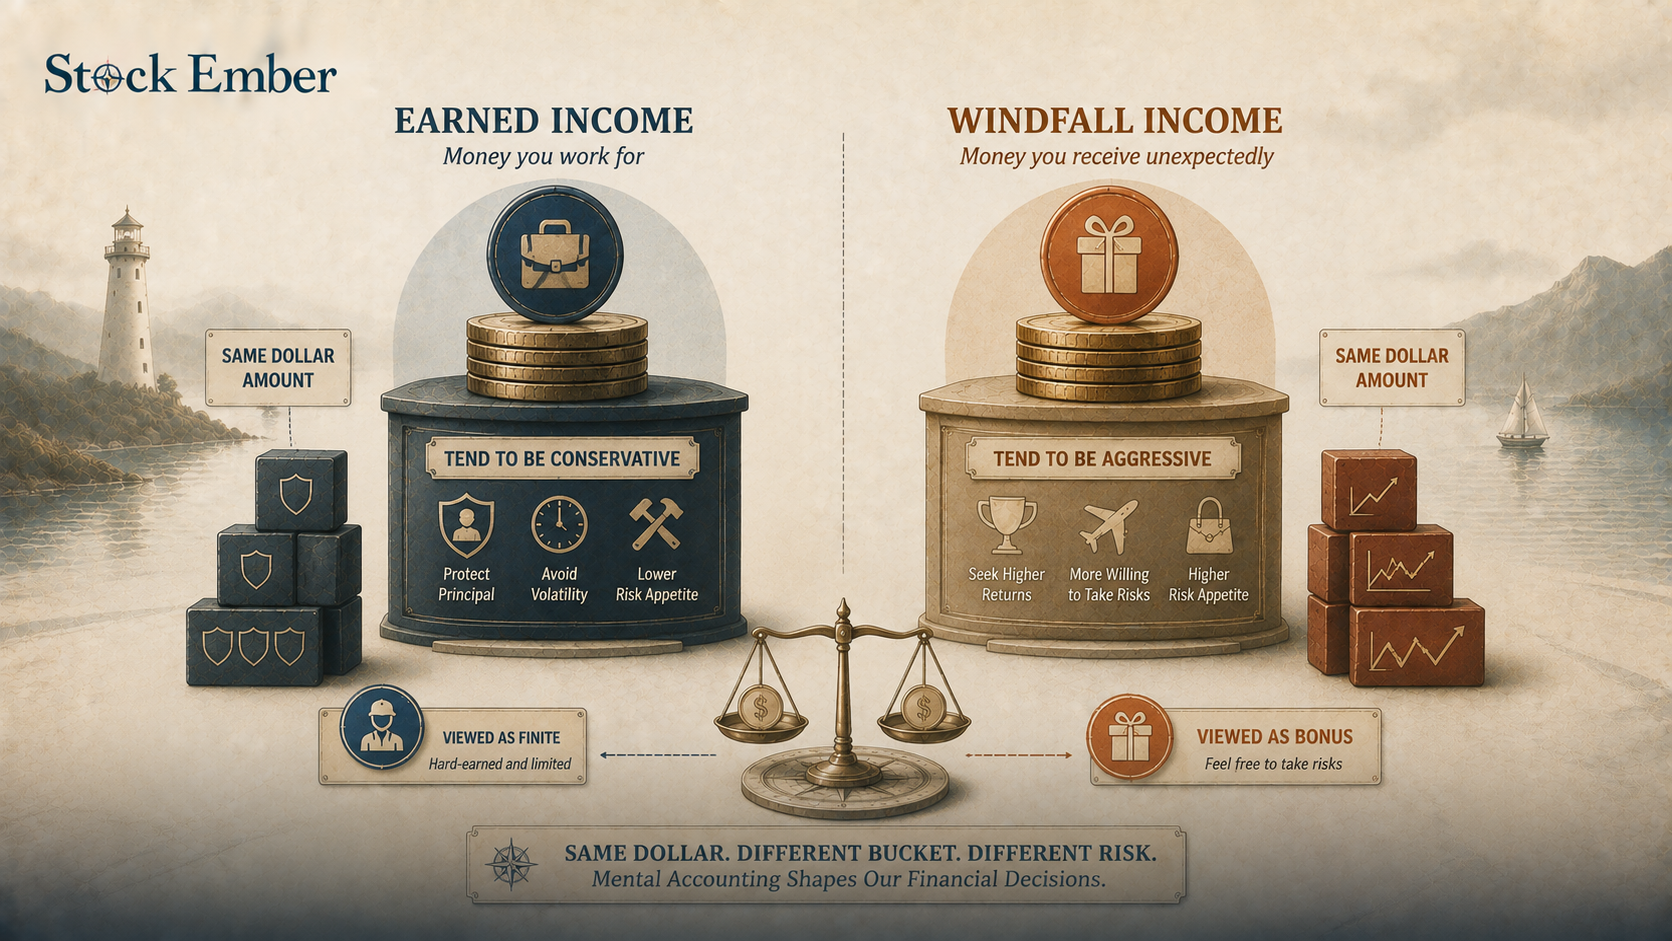
Diagram contrasting regular paycheck income with windfall money in portfolio decision making
The most frequent example is the "house money fallacy" or windfall effect. When an investor receives an unexpected cash influx such as a tax refund, an inheritance, or a sudden stock dividend, they often view it as "found money." Because the cash did not come directly from their monthly paycheck, they take speculative risks with it that they would never dream of taking with their principal investment.
Another everyday example involves separating capital by account type rather than total portfolio value. An investor might treat their primary retirement account with extreme caution, buying only conservative index funds, while simultaneously gambling on volatile single stocks in a personal brokerage account. Because the brain treats these as two separate mental boxes, the investor fails to recognize that a catastrophic loss in the speculative account harms their total net worth just as much as a loss in their retirement account.
Mental accounting bias harms long-term portfolios by distorting asset allocation and blinding investors to their overall risk exposure. When you view your investments as isolated accounts rather than one unified system, your total risk balance breaks down.
A major danger of this bias is holding conflicting risk profiles at the same time. For example, an investor might keep $20,000 in a low-interest bank account earning 1% a year because it is marked as "emergency capital." At the same time, they might carry $10,000 in credit card debt at an 18% interest rate, or take high-risk speculative positions in a separate trading account. Economically, using the cash to pay off the high-interest debt or balancing the portfolio yields an immediate, guaranteed financial gain. Psychologically, mental accounting prevents them from combining these accounts to fix the leak.
This habit also feeds into other behavioral traps, such as recency bias, where recent market swings cause investors to reshuffle money between their mental buckets at the worst possible times. During a market downturn, an investor might freeze their growth bucket and panic-sell assets, forgetting that their long-term timeline spans decades. By evaluating each bucket in isolation, you miss the bigger picture of your total asset allocation.
The 10-Year Opportunity Cost of Money-Bucketing
The 10-year opportunity cost of bucketing money stems from holding excess idle cash while treating investment income as spending money rather than reinvesting it. Over a decade, treating dividend payouts as "free income" to spend on lifestyle expenses severely drags down compound growth.
Consider a simple, hypothetical example. Suppose an investor holds a $100,000 portfolio that generates a 3% annual dividend payout ($3,000 in year one).
Scenario A (Mental Accounting): The investor views the $3,000 annual dividend as "found income" separate from their principal, transferring it to a checking account to buy consumer goods each year. Assuming a 5% annual price appreciation on the underlying stock, the portfolio grows to roughly $162,889 after 10 years, having paid out $30,000 in cash.
Scenario B (Unified Reinvestment): The investor recognizes that dividends are part of total return and automatically reinvests every dollar. Assuming the same 8% total annual return (5% price growth + 3% dividend yield), the portfolio grows to roughly $215,892 after 10 years.
The plain text math for total portfolio value under reinvestment looks like this:
Total Value = Initial Principal * (1 + Annual Total Return)^Years
$215,892 = $100,000 * (1 + 0.08)^10
By treating dividends as a separate spending bucket rather than part of the main growth engine, the mental accounting approach loses over $23,000 in compound potential over ten years.
Common Mental Accounting Pitfalls (and How to Avoid Them)
The most common mental accounting pitfalls include treating dividends as income to spend, refusing to rebalance across separate account types, and maintaining high-risk play money accounts.
Here are three frequent traps and how to correct them:
Treating Dividends as "Free Money": Stock payouts are not bonus cash added on top of your wealth; they are capital distributed directly from the company's net worth. When a dividend is paid, the stock price drops by the payout amount on the ex-dividend date. To avoid this trap, set up automatic dividend reinvestment (DRIP) across all accounts.
Managing Accounts in Silos: Holding a retirement fund, a health savings account, and a taxable brokerage account often leads to unbalanced risk. A tech stock in a taxable account adds tech exposure to your whole life. Combine all holdings into one overall asset allocation overview.
Running a "Play Money" Account: Dedicating 5% or 10% of your portfolio to high-risk gambling under the label "money I can afford to lose" creates poor discipline. A dollar lost in a play account reduces your net worth just as much as a loss in your primary fund.
In practice, many long-term investors find that aggregating all accounts into a single tracking spreadsheet or holistic portfolio dashboard eliminates the psychological urge to gamble with dividend payouts or windfall bonuses.
To overcome mental accounting bias, train yourself to view every financial decision through a single lens: How does this move impact my total net worth over the next ten years?
Conclusion
Mental accounting tricks the brain into treating identical dollars differently based on where they come from or how they are stored. By breaking the fundamental economic law of money fungibility, bucketing capital creates hidden portfolio risks, encourages reckless spending with windfalls, and sacrifices long-term compound growth. Evaluating all your investments, bank deposits, and income streams as a single economic engine protects your portfolio from emotional decision-making.
When you are ready to build a balanced, cost-effective portfolio structure, exploring our ETF reviews is a great next step. Investing always involves risk, including the possible loss of principal, and past market performance does not promise future results. Use this guide as an educational foundation for your own research, rather than personal financial advice.
FAQ
5 questions
What is an example of mental accounting in daily life?
A common example is treating a $500 cash tax refund as "found money" for an impulse holiday purchase while carefully budgeting $500 from a monthly salary for groceries. Economically, both $500 amounts carry identical purchasing power, but mental accounting assigns lower emotional value and spending discipline to the refund.
Why is mental accounting considered a behavioral bias?
Mental accounting is a behavioral bias because it violates the fundamental economic law of fungibility, which states that all money is interchangeable. By assigning subjective rules and risk limits to different accounts or income sources, investors make irrational financial decisions that increase total portfolio risk or diminish compound growth.
What is the principle of fungibility in mental accounting?
Fungibility is the core economic principle that every dollar is identical and interchangeable regardless of its origin, location, or intended use. Mental accounting directly breaks this law by treating dollars differently depending on whether they originate from regular wages, dividend payouts, or unexpected financial windfalls.
How does mental accounting bias affect stock portfolio risk?
Mental accounting leads investors to manage their assets in isolated silos, such as keeping a large cash balance in a "safe account" while making speculative bets with a "play money" trading account. This prevents investors from evaluating their overall asset allocation and obscures their total net worth risk exposure.
Can mental accounting ever be useful for financial planning?
Yes. In household budgeting, dividing money into distinct envelope funds or automated sinking funds can help individuals manage cash flow and curb impulsive spending. However, for investment portfolios, mental accounting often creates inefficient cash drag and masks true portfolio risk.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.