REIT tax advantages stem from their pass-through entity status, which eliminates corporate income tax when at least 90% of taxable income is distributed to shareholders. At the individual level, eligible US investors can also use the Section 199A deduction to shield up to 20% of ordinary REIT dividends from income tax.
REIT tax advantages refer to the special pass-through status granted to Real Estate Investment Trusts, allowing them to avoid corporate income taxes by distributing most of their profits directly to shareholders.
Investors seeking real estate income often look at high yields without realizing how taxes affect their real cash flow. Depending on whether you hold these assets in a taxable brokerage account or a retirement account, taxes can eat away at your growth. This guide breaks down how REIT tax rules work, how dividends are taxed, and how account location impacts long-term wealth.
Quick Takeaways
01REITs avoid corporate double taxation by distributing at least 90% of their taxable income to shareholders.
02REIT payouts are usually taxed as ordinary income rather than lower qualified dividend rates in taxable accounts.
03Eligible investors in the United States can use the Section 199A deduction to shield up to 20% of qualified REIT distributions from ordinary income tax.
04Holding REITs inside tax-advantaged accounts like IRAs prevents annual income tax drag from reducing compound growth.
What Are REIT Tax Advantages? (Corporate vs. Individual Level)
REIT tax advantages begin at the corporate level through a legal structure known as a pass-through entity. Regular corporations pay corporate income tax on their earnings before passing remaining profits to shareholders as dividends, which are then taxed again on personal tax returns. This process is called double taxation.
Real Estate Investment Trusts bypass this double tax layer. Under guidelines established by the Internal Revenue Service, a company must distribute at least 90% of its taxable income to shareholders every year to maintain its tax-exempt corporate status.
Because the REIT pays zero corporate tax on distributed profits, more cash remains available to payout to investors. This corporate tax exemption explains why REIT funds frequently offer higher distribution yields than traditional stocks. However, the tax burden shifts entirely to the individual investor who receives those distributions.
How REIT Dividends Are Categorized and Taxed
Dividends received from REITs do not all carry the same tax treatment on an annual Form 1099-DIV statement. Because real estate companies generate revenue through property operations, sales, and non-cash accounting expenses, payouts fall into three distinct tax buckets:
Distribution Type
Primary Source
Tax Treatment
Ordinary Dividends
Rental income and interest
Taxed at standard personal income tax rates
Capital Gain Distributions
Property sales profits
Taxed at lower long-term capital gains rates
Return of Capital (ROC)
Property depreciation accounting
Tax-deferred; lowers share cost basis
Most REIT distributions count as ordinary dividends. Unlike qualified dividends from regular public companies, ordinary dividends do not qualify for reduced federal tax rates. Instead, they face standard marginal income tax brackets.
Return of Capital distributions occur when property depreciation shelters cash flow. These payouts are not taxed in the year you receive them. Instead, they lower your cost basis per share, deferring tax until you sell your position.
The Section 199A QBI Deduction Explained
The Section 199A Qualified Business Income deduction allows eligible US taxpayers to deduct up to 20% of their qualified REIT dividends from their taxable income. Established under tax legislation, this rule helps narrow the tax gap between qualified stock dividends and ordinary pass-through distributions.
For an investor in a 24% tax bracket, assuming the investor qualifies for the full 20% deduction, the effective federal tax rate on that income falls to 19.2%. For an investor in the top 37% federal tax bracket, the effective tax rate falls to 29.6%.
This deduction applies whether an investor itemizes deductions or takes the standard deduction on their tax return. However, it only applies to ordinary REIT distributions held in taxable brokerage accounts. Payouts inside tax-sheltered retirement accounts do not receive the deduction because those accounts follow their own tax rules.
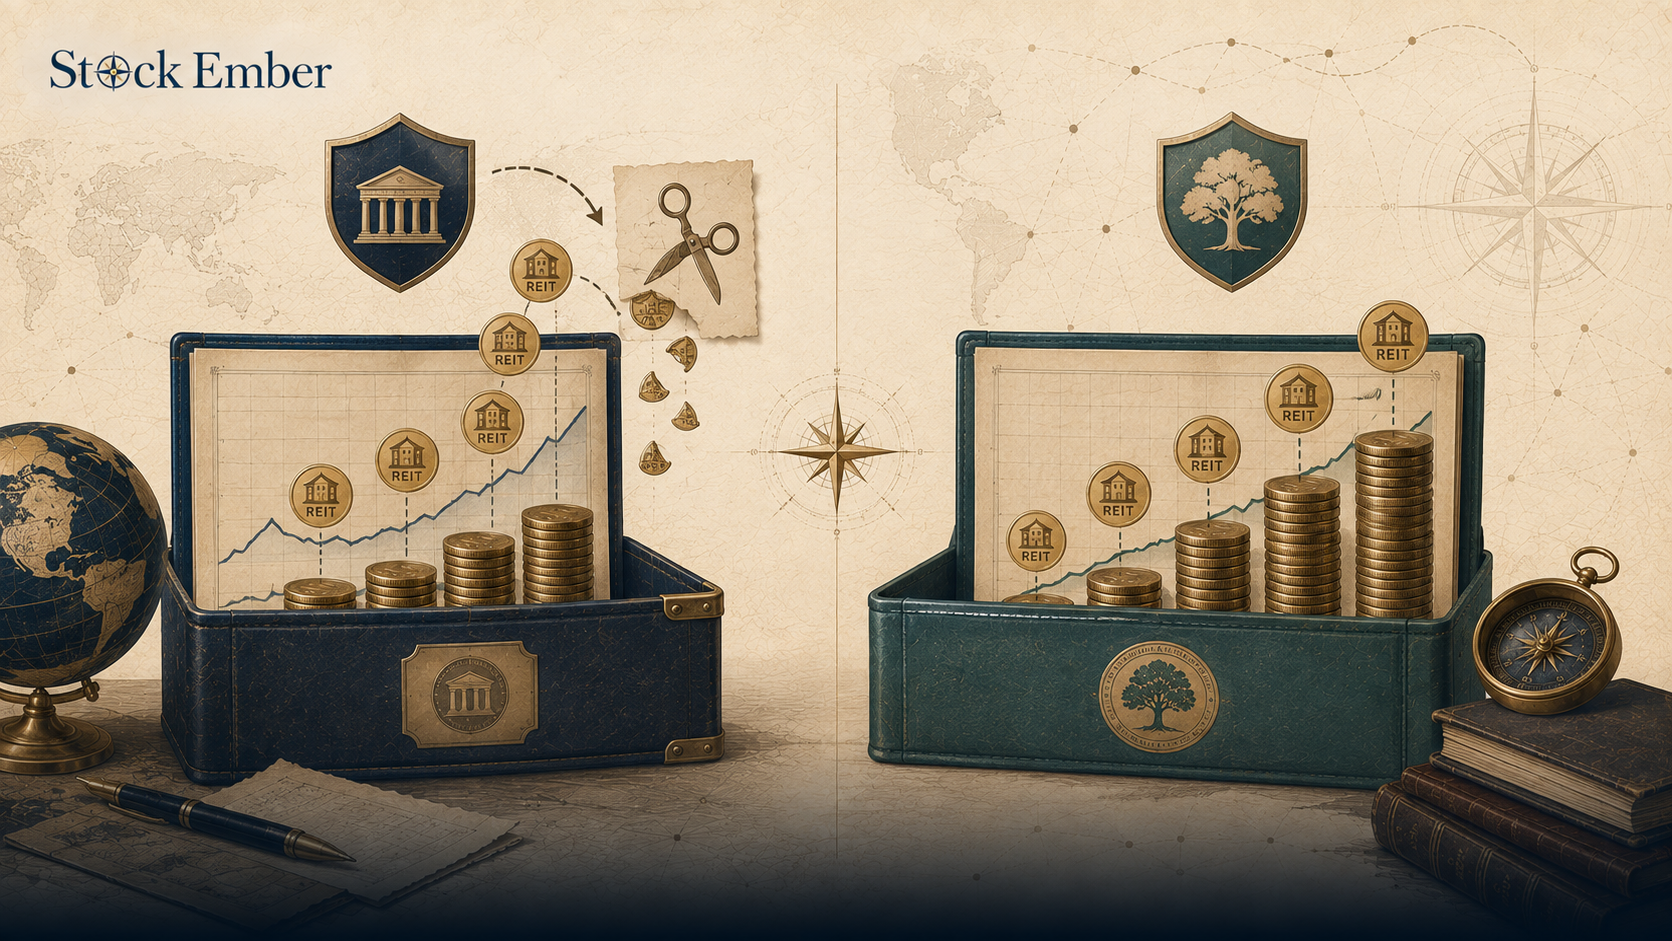
Diagram showing the 10-year growth difference between holding REITs in taxable accounts and tax-advantaged accounts.
The 10-Year Asset Location Impact: Taxable Accounts vs. IRAs
Choosing where to hold REIT investments plays a major role in determining your net long-term portfolio growth. Asset location refers to placing investments in the account type that minimizes annual tax drag.
Suppose an investor places $100,000 into a REIT fund paying a 5% dividend yield inside a standard taxable brokerage account. In year one, the portfolio generates $5,000 in income. Assuming a 24% marginal federal income tax rate and the full 20% Section 199A deduction, the effective federal tax rate on the distribution would be 19.2%, resulting in about $960 of federal income tax in the first year.
Over a 10-year holding period, paying taxes on distributions each year leaves less money available for reinvestment, which can reduce compounded growth. That annual tax bill reduces the total money left in the account to compound.
In practice, many long-term investors find that placing high-yielding REIT funds inside a Roth IRA or Traditional IRA preserves far more wealth because distributions compound tax-deferred or tax-free without annual tax drag.
Strategic Role in a Passive Buy-and-Hold Portfolio
Real estate assets offer distinct income and diversification characteristics when built into a long-term allocation strategy. Using low-cost index funds for passive investing gives investors broad real estate exposure without the headaches of physical property management.
During an extended economic expansion or bull market, real estate values and occupancy rates often rise, increasing rental income distributions. Combining real estate index funds with general stock and bond holdings helps build a balanced portfolio that generates cash flow across different economic phases.
To maintain an effective allocation over time, consider these simple guidelines:
Place REITs in tax-advantaged accounts first: Use IRAs or 401(k)s for REIT holdings to protect high income distributions from annual ordinary tax rates.
Cap total real estate exposure: Keep REIT allocations within a planned percentage of your total portfolio to maintain healthy asset diversification.
Focus on total return: Look at both dividend yield and long-term capital appreciation rather than chasing yield alone.
Common REIT Tax Pitfalls to Avoid
Many investors lose money to unexpected tax bills by making simple asset management mistakes. Staying aware of these traps keeps your net returns on target:
Expecting qualified dividend rates: Assuming REIT payouts qualify for lower long-term dividend tax rates instead of higher ordinary income rates.
Ignoring account placement: Stashing high-yielding REIT funds in taxable accounts when space is available in tax-sheltered retirement accounts.
Miscalculating Return of Capital: Forgetting that Return of Capital distributions lower your share cost basis, which increases taxable capital gains when you eventually sell shares.
Overlooking state income taxes: Forgetting that ordinary REIT distributions may also face state income taxes depending on where you live.
Conclusion
Understanding REIT tax advantages helps long-horizon investors balance higher dividend yields against annual income tax responsibilities. By capitalizing on corporate pass-through status and the Section 199A deduction, REITs can deliver efficient income. However, holding these investments inside tax-advantaged accounts is often the best way to prevent annual income tax drag from slowing down your compound growth over a 10-year horizon.
When you are ready to evaluate real estate funds for your portfolio, our ETF reviews provide clear, fee-focused analysis. Tax laws can change over time and individual tax liabilities depend on personal circumstances, so treat this educational guide as a starting point for your own research and consult a tax professional for specific filing guidance.
FAQ
5 questions
What are the main tax advantages of investing in a REIT?
The primary advantage is entity-level tax pass-through, meaning the REIT pays zero corporate income tax if it distributes at least 90% of taxable income. For individual US investors in taxable accounts, the Section 199A deduction allows up to 20% of ordinary REIT dividends to be excluded from federal income tax.
Are REIT dividends taxed as qualified dividends or ordinary income?
REIT distributions are generally taxed as non-qualified ordinary income because the REIT did not pay corporate tax on those earnings. However, a portion of distributions may be classified as capital gains or non-taxable Return of Capital depending on the underlying revenue source.
How does the 20% Section 199A QBI deduction work for REIT dividends?
Under Section 199A, eligible investors can deduct 20% of qualified REIT dividends from their taxable income. For example, an investor in the top 37% federal tax bracket effectively pays a 29.6% rate on ordinary REIT distributions when applying the deduction.
What is a Return of Capital (ROC) distribution in a REIT?
Return of Capital occurs when property depreciation shelters cash flow. ROC distributions are not taxed in the year received; instead, they reduce your cost basis per share, deferring tax liabilities until you sell the investment.
Should REITs be held in a taxable account or a tax-advantaged IRA?
Holding REITs in tax-advantaged accounts like a Roth IRA or Traditional IRA is generally more tax-efficient because distributions compound tax-free or tax-deferred without annual ordinary income tax drag.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.