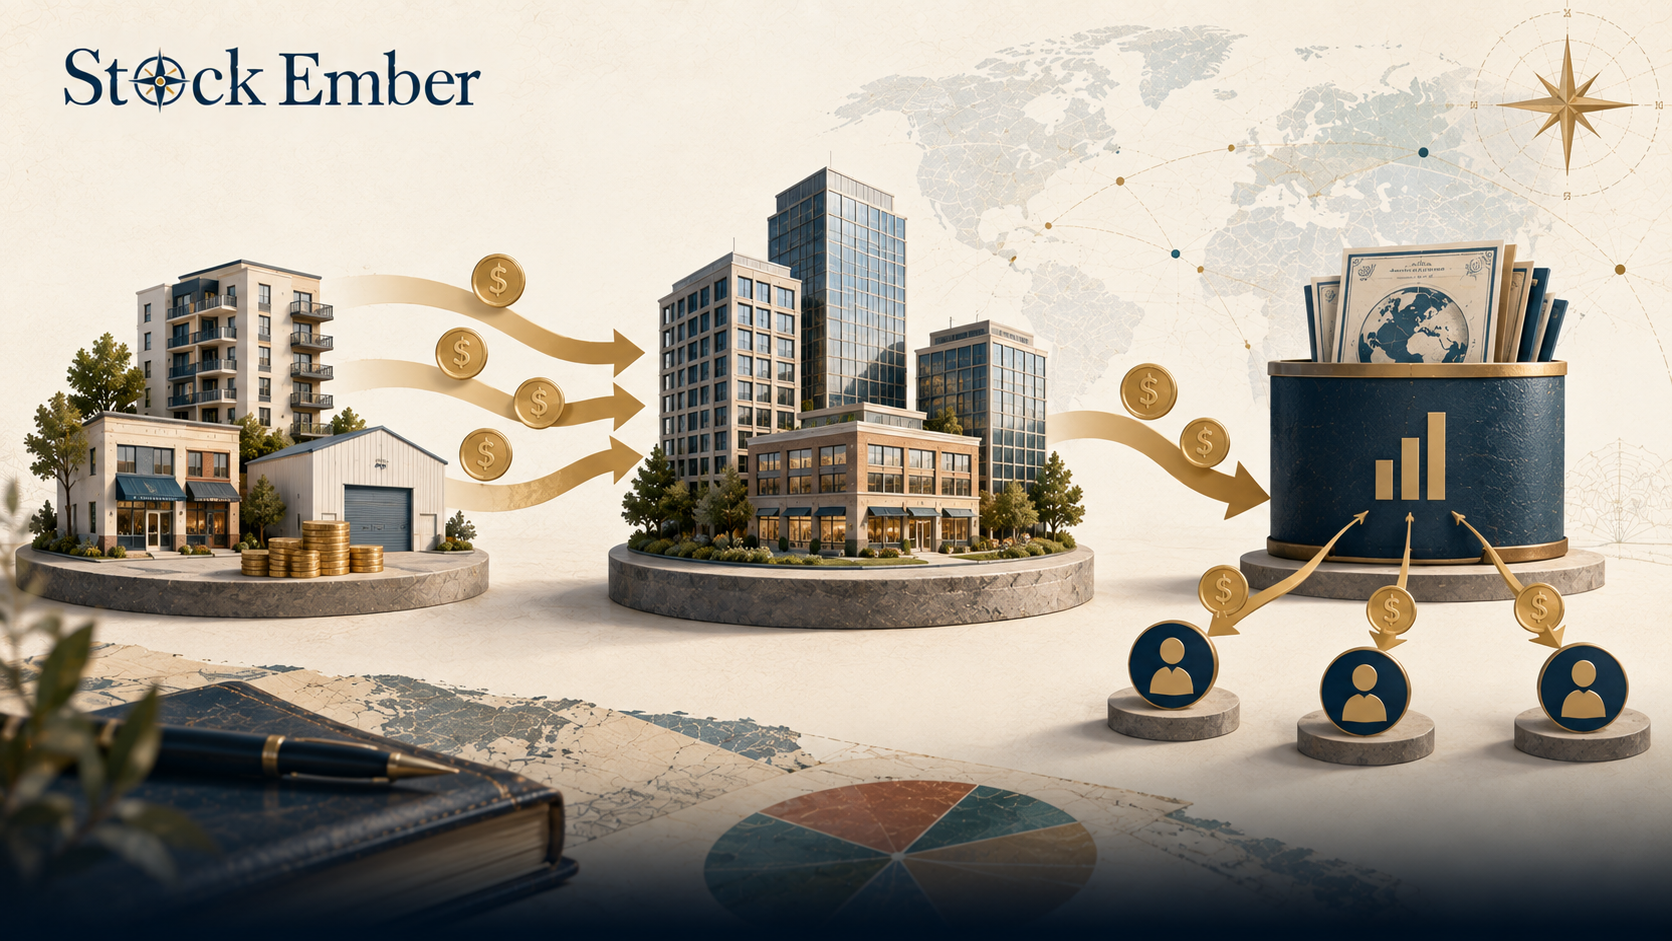
A REIT mutual fund is a pooled investment vehicle that owns a diversified portfolio of publicly traded real estate investment trusts. It provides individual investors with liquid commercial real estate exposure, collecting rental income across property sectors and distributing payouts to fund shareholders.
A REIT mutual fund is a pooled investment vehicle that holds a portfolio of publicly traded real estate investment trusts, allowing individual investors to access commercial property markets without directly buying or managing real estate.
Buying commercial real estate directly requires significant capital and landlord responsibilities. REIT mutual funds solve this by spreading your money across office towers, warehouses, data centers, and apartment buildings with daily liquidity. This guide explains how REIT mutual funds generate rental income, how payouts are taxed, how they compare to individual REITs and ETFs, and key fee traps to avoid when allocating portfolio cash.
Quick Takeaways
01REIT mutual funds pool money from investors to purchase shares across multiple property sectors, providing automatic diversification.
02Income comes primarily from property rents, which underlying REITs must distribute to shareholders to maintain tax privileges.
03REIT distributions are generally taxed as ordinary income rather than qualified corporate dividends, making tax-advantaged accounts ideal for holding them.
04Actively managed REIT mutual funds charge higher expense ratios that can drag down portfolio returns compared to low-cost passive real estate index funds.
What Is a REIT Mutual Fund?
A REIT mutual fund buys and manages a diversified basket of publicly traded real estate investment trusts. Instead of placing your money into a single company or property, one share of a REIT mutual fund gives you partial exposure to hundreds of commercial properties across different industries.
Real estate investment trusts are specialized companies that own, operate, or finance income-producing real estate. When you invest through a REIT mutual fund, a professional management team selects and monitors these trusts on your behalf. These underlying holdings span several main property types:
Industrial and Logistics: Distribution facilities, fulfillment centers, and storage hubs.
Residential: Multi-family apartment complexes, manufactured housing, and single-family rental communities.
Healthcare: Medical office buildings, senior housing facilities, and life science laboratories.
Data Centers: Specialized infrastructure facilities housing server racks for cloud computing.
Because these funds trade through mutual fund companies at the end of each business day, you can enter or exit positions at net asset value without needing to negotiate property sales or manage physical tenants.
How REIT Mutual Funds Generate Income and Payouts
REIT mutual funds generate returns through two main sources: dividend distributions collected from tenant leases and long-term property appreciation reflected in the fund's share price.
The steady income flow of REITs stems from federal tax law. According to distribution requirements enforced by the IRS, a qualifying REIT must distribute at least 90% of its ordinary taxable income to shareholders every year. Because underlying REITs pass their earnings directly to investors, they avoid corporate-level income taxes.
When the REIT mutual fund collects these dividend distributions from its underlying properties, it passes them along to mutual fund shareholders, usually on a quarterly or monthly schedule.
However, the tax treatment of these payouts requires attention:
Ordinary Income Tax Rates: Unlike standard corporate dividends, which often qualify for lower tax rates, most REIT dividend distributions are taxed as ordinary income.
Qualified Business Income (QBI) Deduction: Under current tax rules, individual investors can often deduct up to 20% of qualified REIT dividends, reducing the effective federal tax rate on distributions.
Capital Gains and Return of Capital: Occasionally, payouts include capital gains from property sales or non-taxable returns of capital, which alter your cost basis when sold.
Diagram showing rental cash flows passing from commercial properties through REIT mutual funds to investors.
REIT Mutual Funds vs. Individual REITs vs. REIT ETFs
Investors seeking real estate exposure must decide whether to buy individual REIT stocks, actively managed REIT mutual funds, or exchange-traded funds (ETFs). Each structure carries different trade-offs in fees, trading mechanics, and portfolio strategy.
If you practice passive investing, choosing between an active REIT mutual fund and a low-cost passive index fund comes down to control and expense management.
Feature
Individual REITs
Active REIT Mutual Funds
Passive REIT ETFs
Diversification
Single stock focus
Broad property portfolio
Broad index tracking
Management Style
Direct stock selection
Active manager picks
Passive rule-based tracking
Pricing / Trading
Intraday exchange price
End-of-day NAV price
Intraday exchange price
Average Expense Ratio
0% (brokerage dependent)
0.60% to 1.00%+
0.10% to 0.20%
Minimum Purchase
1 share
$1,000 to $3,000+ initial
1 share / fractional
Individual REITs allow you to target specific property sectors, but they require continuous research to avoid struggling property holdings. Active REIT mutual funds provide instant diversification and professional oversight, though their higher management fees create a drag on total return. Passive REIT ETFs offer similar broad exposure with low expense ratios and intraday liquidity.
Common Mistakes to Avoid with REIT Mutual Funds
Even though real estate funds provide steady income and diversification, investors often make mistakes that reduce long-term compounding.
1. Ignoring 10-Year Fee Drag
Actively managed REIT mutual funds often charge annual expense ratios ranging from 0.60% to 1.00% or higher. Over a ten-year holding period, a 0.75% annual fee on a $50,000 portfolio costs roughly $3,750 in direct fees alone, without counting lost compounding opportunities.
By contrast, a passive real estate index fund charging 0.12% costs about $600 over the same decade. Paying higher management fees makes sense only if the fund manager consistently beats market benchmarks after expenses.
In practice, many long-term investors find that building a real estate allocation using low-cost index funds delivers more reliable net returns than chasing active fund managers who struggle to overcome their own fee hurdles.
2. Placing High-Yielding REIT Funds in Taxable Accounts
Because REIT mutual fund distributions are taxed as ordinary income rather than lower qualified dividend rates, holding them in a regular taxable brokerage account can create an unnecessary annual tax drag. Placing REIT funds inside tax-advantaged accounts like an IRA or 401(k) allows dividend payouts to compound sheltered from annual income taxes.
3. Overlooking Interest Rate Sensitivity
Real estate values and REIT share prices share an inverse relationship with interest rate movements. When market interest rates rise, borrowing costs for commercial property developers increase, and fixed-income yields on government bonds become more competitive. As a result, REIT mutual funds can experience short-term price drops during rising interest rate cycles, even if underlying property rents remain steady.
Conclusion
REIT mutual funds provide an accessible path to commercial real estate ownership, combining broad property diversification with regular cash flow. While high distribution requirements make them appealing for income-focused portfolios, ongoing management fees and ordinary income tax rules require careful planning. Holding your real estate allocation inside a tax-advantaged account and opting for low-cost fund structures helps preserve your income for long-term compounding.
When you are ready to evaluate low-cost fund choices for your broader allocation, our ETF reviews offer a logical next step.
Investing in real estate funds carries market risk and past payouts do not guarantee future dividend yields, so use this guide as educational context rather than personalized investment advice.
FAQ
5 questions
What is a REIT mutual fund?
A REIT mutual fund is a pooled investment fund managed by financial professionals that invests in a portfolio of publicly traded real estate investment trusts. It gives investors broad exposure to commercial property sectors like warehouses, apartment buildings, and data centers without needing direct real estate ownership.
How are REIT mutual fund distributions taxed?
Dividend distributions from REIT mutual funds are generally taxed as ordinary income rather than lower qualified dividend rates. However, individual investors may be eligible for a 20% Qualified Business Income (QBI) deduction on qualified REIT dividends under Section 199A.
What is the difference between a REIT mutual fund and a REIT ETF?
REIT mutual funds trade once daily at net asset value (NAV) after market close and are often actively managed with higher expense ratios. REIT ETFs trade throughout the trading day on stock exchanges and typically track passive real estate indexes with lower management fees.
Do REIT mutual funds pay monthly dividends?
Most REIT mutual funds distribute dividend income on a quarterly schedule, though some income-focused real estate funds pay monthly distributions depending on the dividend payout schedules of their underlying property holdings.
Is it better to hold REIT mutual funds in a taxable account or an IRA?
Because REIT fund distributions are taxed at ordinary income rates, holding REIT mutual funds inside a tax-advantaged account like a Traditional IRA, Roth IRA, or 401(k) helps shield ongoing dividend payouts from annual income tax drag.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.