A municipal bond ETF is a liquid exchange-traded fund that holds a diversified basket of state and local government debt securities. It provides investors with regular interest distributions that are generally exempt from federal income tax, with overall tax efficiency determined by an investor's marginal tax bracket.
While corporate bonds often subject high-earning investors to heavy tax burdens, municipal debt provides an attractive alternative by keeping interest income federally tax-exempt. Investing through an ETF allows you to capture these benefits across a diversified, professionally managed portfolio in a single trade. This guide breaks down how these funds function, how to calculate your net tax savings, and the key risks to consider before allocating capital.
Quick Takeaways
01Municipal bond ETFs hold collections of state and local government bonds that deliver federally tax-exempt monthly interest distributions.
02The real financial benefit depends on your marginal tax bracket; higher earners receive far greater tax-equivalent yields than lower-bracket investors.
03ETFs offer daily exchange liquidity and instant diversification compared to individual bonds, though their perpetual portfolio structure exposes investors to ongoing interest rate sensitivity.
04While monthly income is generally tax-exempt, selling ETF shares at a profit triggers taxable capital gains, and certain private-activity bonds within a fund may trigger the Alternative Minimum Tax (AMT).
What Is a Municipal Bond ETF?
A municipal bond ETF is a pooled investment fund that buys debt issued by states, cities, counties, and local public authorities to finance essential public projects like highways, water systems, schools, and airports.
When local governments need capital to build or upgrade infrastructure, they issue municipal bonds ("munis"). Instead of requiring you to research and purchase individual city or state bonds, an ETF bundles hundreds or thousands of these bonds into a single security.
You can trade shares of the fund throughout the market day through a standard brokerage account, earning monthly cash distributions funded by the interest payments of the underlying municipal borrowers.
Municipal bonds represent a specific category within the broader universe of types of bonds available to fixed-income investors, distinguished primarily by their unique tax status and government backing.
How Municipal Bond ETFs Work (and the Tax Advantage)
Municipal bond ETFs function by collecting interest from their underlying bond portfolios and passing those payments through to shareholders as monthly income distributions, largely free from federal income tax.
Holding a tax free municipal bonds ETF allows investors in high federal tax brackets to retain a larger portion of their yield compared to holding taxable corporate or Treasury bond funds. Depending on the fund's design, the tax treatment generally falls into two categories:
National Municipal Bond ETFs: These funds hold debt issued by local governments across many different states. Distributions are exempt from federal income tax, though investors may still owe state or local taxes on the income depending on where they live.
Single-State Municipal Bond ETFs: These funds invest exclusively in debt issued within a single state (such as California or New York). For residents of that specific state, distributions are often "triple tax-free", exempt from federal, state, and local income taxes.
To evaluate whether a tax-free yield beats a taxable bond yield, investors calculate the Tax-Equivalent Yield (TEY).
For example, if you are in a 32% federal tax bracket and a municipal bond ETF yields 4.0%, the math works as follows: 4.0% / (1 − 0.32) = 5.88%. A taxable corporate bond fund would need to yield 5.88% just to match the cash you keep after taxes. Conversely, for investors in lower tax brackets (such as 12% or 22%), taxable bond ETFs often yield more net income after accounting for taxes.
Federal tax exemption rules for municipal interest payments are established by tax authorities and outlined by investor.gov.
Comparison chart of direct municipal bonds versus municipal bond ETFs.
Direct Municipal Bonds vs. Municipal Bond ETFs
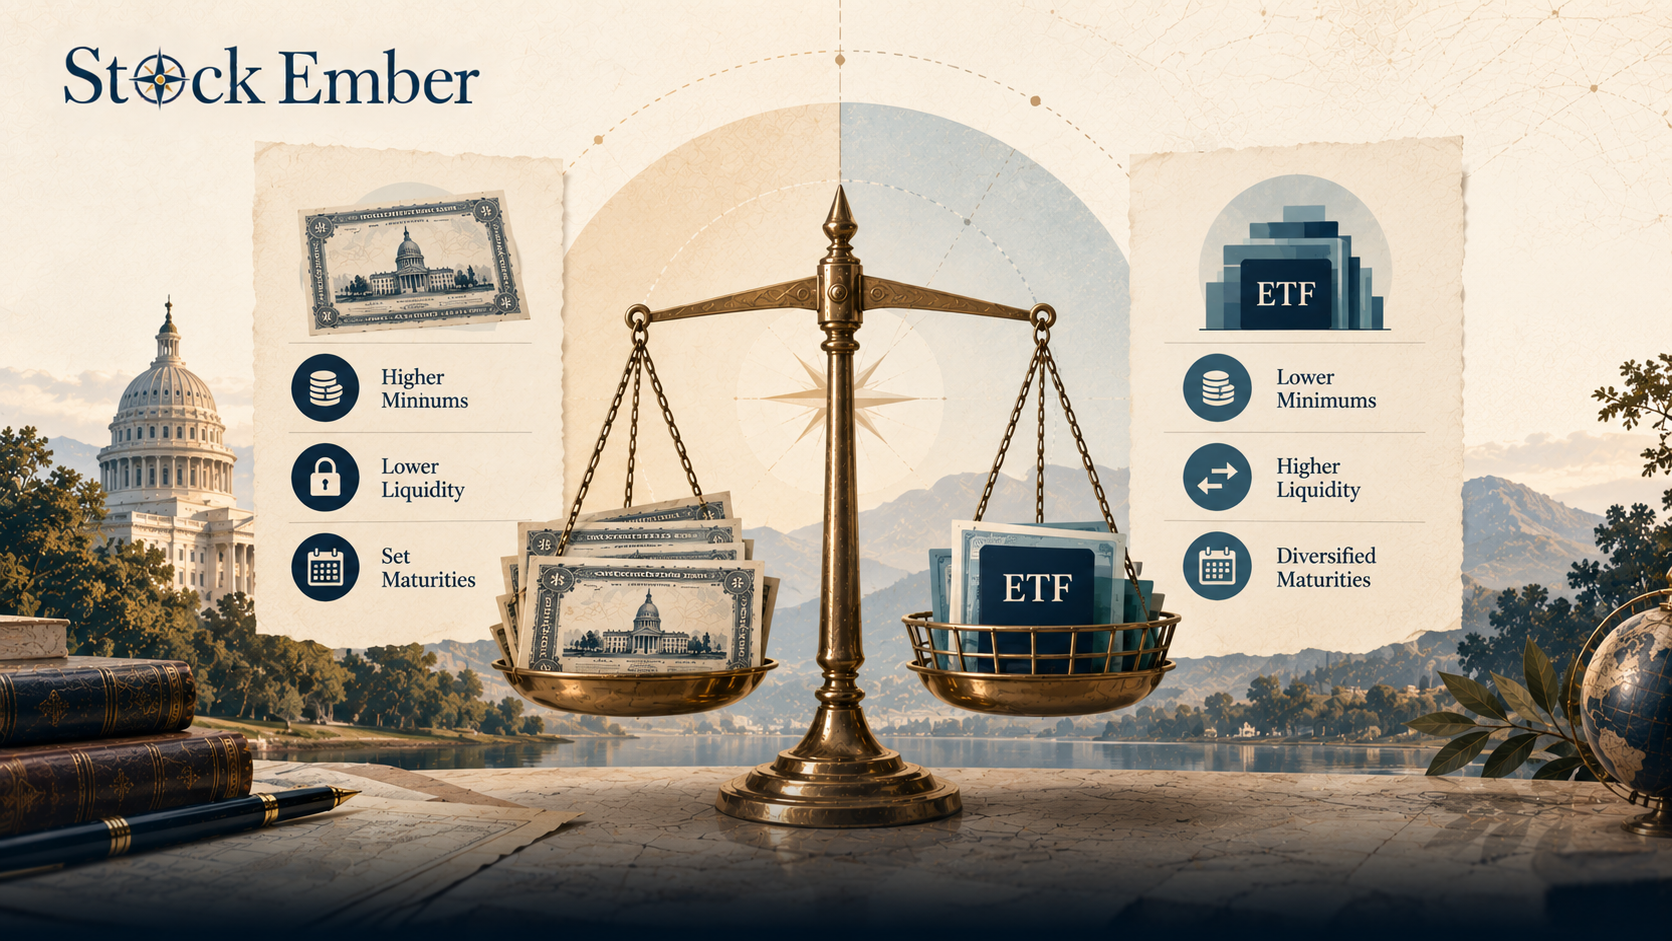
Choosing between buying individual municipal bonds and investing through an ETF comes down to trading individual maturity dates for daily trading liquidity, low investment minimums, and broad credit diversification.
Feature
Direct Municipal Bonds
Municipal Bond ETFs
Minimum Investment
High (typically $5,000 per bond; $100,000+ for diversification)
Low (price of a single share, often under $100)
Maturity
Fixed maturity date (principal returned at maturity)
Lower OTC liquidity for retail sizes; wider bid-ask spreads
High liquidity on stock exchanges; tight bid-ask spreads
Cost Structure
Broker markups during purchase/sale execution
Ongoing expense ratio (e.g., 0.12% or ~$60/year on $50,000)
Best For
Buy-and-hold investors aiming to collect predictable cash flow to maturity
Active rebalancing, dollar-cost averaging, and immediate diversification
In practice, many long-term investors find that holding individual munis works well if you plan to hold every bond to maturity, whereas ETFs offer far greater flexibility for systematic dollar-cost averaging and portfolio rebalancing.
Key Risks and Pitfalls to Watch
While municipal issuers have historically maintained lower default rates than similarly rated corporate borrowers, according to long-term credit studies published by Moody's Investors Service, municipal bond ETFs still carry interest rate risk, tax nuances, and credit risks that can impact total returns.
Rising interest rates represent the primary source of price volatility. Because bond prices move inversely to interest rates, an ETF with a target duration of 7 years will lose roughly 7% of its share value if market interest rates rise by 1 percentage point.
Taxation also holds important nuances. While monthly income distributions are federally tax-exempt, selling your ETF shares at a profit triggers taxable capital gains. Furthermore, certain municipal bond ETFs hold "private-activity bonds" (issued for projects like private airports or industrial development). Income from these specific bonds can trigger the Alternative Minimum Tax (AMT) for high-earning taxpayers.
Finally, credit risk remains a factor. Economic downturns can strain state and municipal budgets. While evaluating overall municipal bond safety demonstrates strong historical stability, unexpected credit downgrades or fiscal distress in major municipalities can suppress an ETF's share price.
Conclusion
Choosing a municipal bonds ETF over individual bonds comes down to liquidity, cost, and diversification.
A municipal bonds ETF provides a liquid, accessible method for investors in higher tax brackets to capture tax-exempt income across state and local government debt. By calculating your tax-equivalent yield, weighing the flexibility of ETFs against direct bond maturity schedules, and accounting for duration sensitivity, you can determine how these funds fit into your broader fixed-income allocation.
When you are ready to evaluate specific funds, our ETF reviews offer a closer look at fee structures, index tracking, and portfolio composition. Investing always involves risk, including the loss of principal, so treat this guide as educational baseline research rather than personalized financial advice.
FAQ
5 questions
Are municipal bond ETFs completely tax-free?
Not entirely. While monthly interest distributions are typically exempt from federal income tax (and sometimes state/local taxes for in-state funds), selling ETF shares for a profit triggers taxable capital gains. Additionally, income from underlying private-activity bonds may trigger the Alternative Minimum Tax (AMT).
How is tax-equivalent yield on a municipal bond ETF calculated?
Tax-equivalent yield (TEY) is calculated by dividing the tax-free municipal yield by (1 minus your marginal federal tax rate). For example, if a fund yields 4.0% and your federal tax bracket is 32%, the calculation is 4.0% / (1 − 0.32) = 5.88%.
What is the difference between direct municipal bonds and municipal bond ETFs?
Direct municipal bonds require higher minimum investments, have fixed maturity dates, and pay principal back at maturity. Municipal bond ETFs trade on stock exchanges with daily liquidity, charge ongoing expense ratios, offer continuous multi-issuer diversification, and hold a perpetual portfolio duration without maturing.
Do municipal bond ETFs trigger capital gains taxes?
Yes. Although the interest income distributed by the ETF is federally tax-exempt, capital gains realized from selling fund shares at a profit or from the fund manager selling underlying holdings at a gain are subject to standard capital gains taxation.
Can you lose money in a municipal bond ETF?
Yes. Municipal bond ETFs are subject to interest rate risk; when market interest rates rise, the principal share price of the fund declines. They are also subject to credit risk if underlying municipal bond issuers face fiscal strain or credit downgrades.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.