IRA withdrawal rules determine the tax liability and penalties applied to distributions from tax-advantaged retirement accounts. Distributions taken before age 59½ generally incur ordinary income tax plus a 10% early withdrawal penalty, while qualified Roth contributions remain tax-free anytime. Under SECURE 2.0 legislation, required minimum distributions (RMDs) must begin at age 73.
IRA withdrawal rules are IRS regulations that govern when and how you can access funds from tax-advantaged retirement accounts, defining the exact tax rates and penalties that apply to distributions.
Taking money out of an Individual Retirement Account without planning can trigger tax penalties and destroy long-term compounding growth. At the same time, waiting too long to make distributions leads to severe tax fines under mandatory payout schedules. Understanding these rules ensures you protect your retirement savings from preventable tax erosion. This guide explains age benchmarks, account mechanics, penalty exceptions, and distribution traps.
Quick Takeaways
01Traditional IRA distributions prior to age 59½ generally face ordinary income tax plus a 10% early withdrawal penalty.
02Roth IRA principal contributions can be withdrawn tax-free and penalty-free at any time, but earnings require reaching age 59½ and meeting a 5-year holding requirement.
03Required Minimum Distributions (RMDs) currently begin at age 73 under SECURE 2.0 legislation.
04Specific IRS exceptions—such as qualified first-time home purchases up to $10,000—allow penalty-free early distributions.
05Withdrawing funds early destroys future tax-deferred compound growth, taking a far bigger toll on long-term wealth than the immediate tax bill alone.
IRA Withdrawal Age Thresholds: Standard, Early, and Mandatory
Your ira withdrawal age dictates whether your distributions are subject to penalties, tax-free treatment, or mandatory distribution requirements. The IRS establishes three distinct age tiers that every retirement investor must follow, and these IRA withdrawal rules apply regardless of which custodian holds your account:
Under Age 59½ (Early Distributions): Withdrawals made before reaching age 59½ are classified as early distributions. In a Traditional IRA, early payouts trigger ordinary income tax plus a 10% early withdrawal penalty unless you meet a specific IRS exception.
Age 59½ to 73 (Penalty-Free Window): Once you turn 59½, you can take distributions from your IRA without facing the 10% early withdrawal tax. You are not required to take payouts during this window, giving you full control over when to trigger taxable distributions.
Age 73 and Older (Mandatory Distributions): Under current SECURE 2.0 legislation, account holders must begin taking required minimum distributions starting at age 73. Failing to take an RMD results in an IRS penalty tax equal to 25% of the unwithdrawn amount (which drops to 10% if corrected promptly).
Understanding these age triggers helps you avoid unexpected penalties while planning tax-efficient income in retirement.
Traditional IRA vs. Roth IRA Withdrawal Rules
The primary difference between Traditional and Roth account rules lies in how and when your contributions were taxed.
According to the Internal Revenue Service, retirement accounts carry specific tax treatment and withdrawal constraints. In a Traditional account, traditional ira withdrawal tax rules apply to all distributions because contributions were made with pre-tax dollars. Every dollar withdrawn—both original contributions and investment growth—is added to your gross income and taxed at your ordinary income tax rate.
By contrast, roth ira distribution rules treat principal and earnings separately. Because Roth contributions are made with post-tax income, you can withdraw your original contribution dollars at any time, at any age, without paying additional income tax or penalties.
Feature
Traditional IRA
Roth IRA
Contribution Tax Treatment
Pre-tax (tax-deductible)
Post-tax (after-tax dollars)
Withdrawal of Contributions
Taxed as ordinary income
Tax-free and penalty-free anytime
Withdrawal of Earnings
Taxed as ordinary income
Tax-free if age 59½ + 5-year rule met
Early Withdrawal Penalty
10% penalty under age 59½
10% penalty on earnings only
RMD Requirements
Mandatory starting at age 73
No RMDs during owner's lifetime
Managing your broader accounts and tax strategy requires looking at both account types together. Comparing a traditional vs Roth IRA shows that while Traditional accounts offer upfront tax relief, Roth accounts deliver complete tax flexibility during retirement.
The Roth IRA Ordering Rules & 5-Year Requirement
Roth IRAs follow strict FIFO (First-In, First-Out) distribution ordering rules set by the IRS. When you withdraw money from a Roth account, the funds come out in this specific order:
Regular Contributions: Always tax-free and penalty-free.
Conversions and Rollovers: Distributed on a first-in, first-out basis. Tax-free, but subject to a separate 5-year holding period to avoid the 10% penalty if under age 59½.
Earnings: Distributed last. Tax-free and penalty-free only if you are at least age 59½ AND have met the 5-year rule.
The Roth IRA 5-year rule requires five consecutive tax years to pass from your first contribution before earnings can be withdrawn tax-free. This clock begins on January 1st of the tax year for which you made your initial contribution, regardless of which month you actually deposited the funds.
IRS Early Withdrawal Penalty Exceptions
If you need to access Traditional IRA funds before age 59½, the IRS provides several statutory exceptions—outlined in IRS Publication 590-B—that allow an ira penalty free withdrawal. While these exceptions remove the 10% penalty, you still owe ordinary income tax on any pre-tax distributions.
Common penalty exceptions include:
First-Time Home Purchase: You can withdraw up to $10,000 lifetime to buy, build, or rebuild a primary residence for yourself or qualified family members.
Qualified Higher Education Expenses: Distributions used for tuition, fees, books, and required supplies at an eligible post-secondary institution avoid the 10% fee.
Unreimbursed Medical Expenses: Payouts used to pay medical bills that exceed 7.5% of your Adjusted Gross Income (AGI) are exempt from the penalty.
Substantially Equal Periodic Payments (SEPP): Under IRS Rule 72(t), you can avoid penalties by taking a series of scheduled payments calculated over your life expectancy for at least 5 years or until age 59½, whichever is longer.
The True Cost of Early IRA Distributions: A 10-Year Portfolio Model
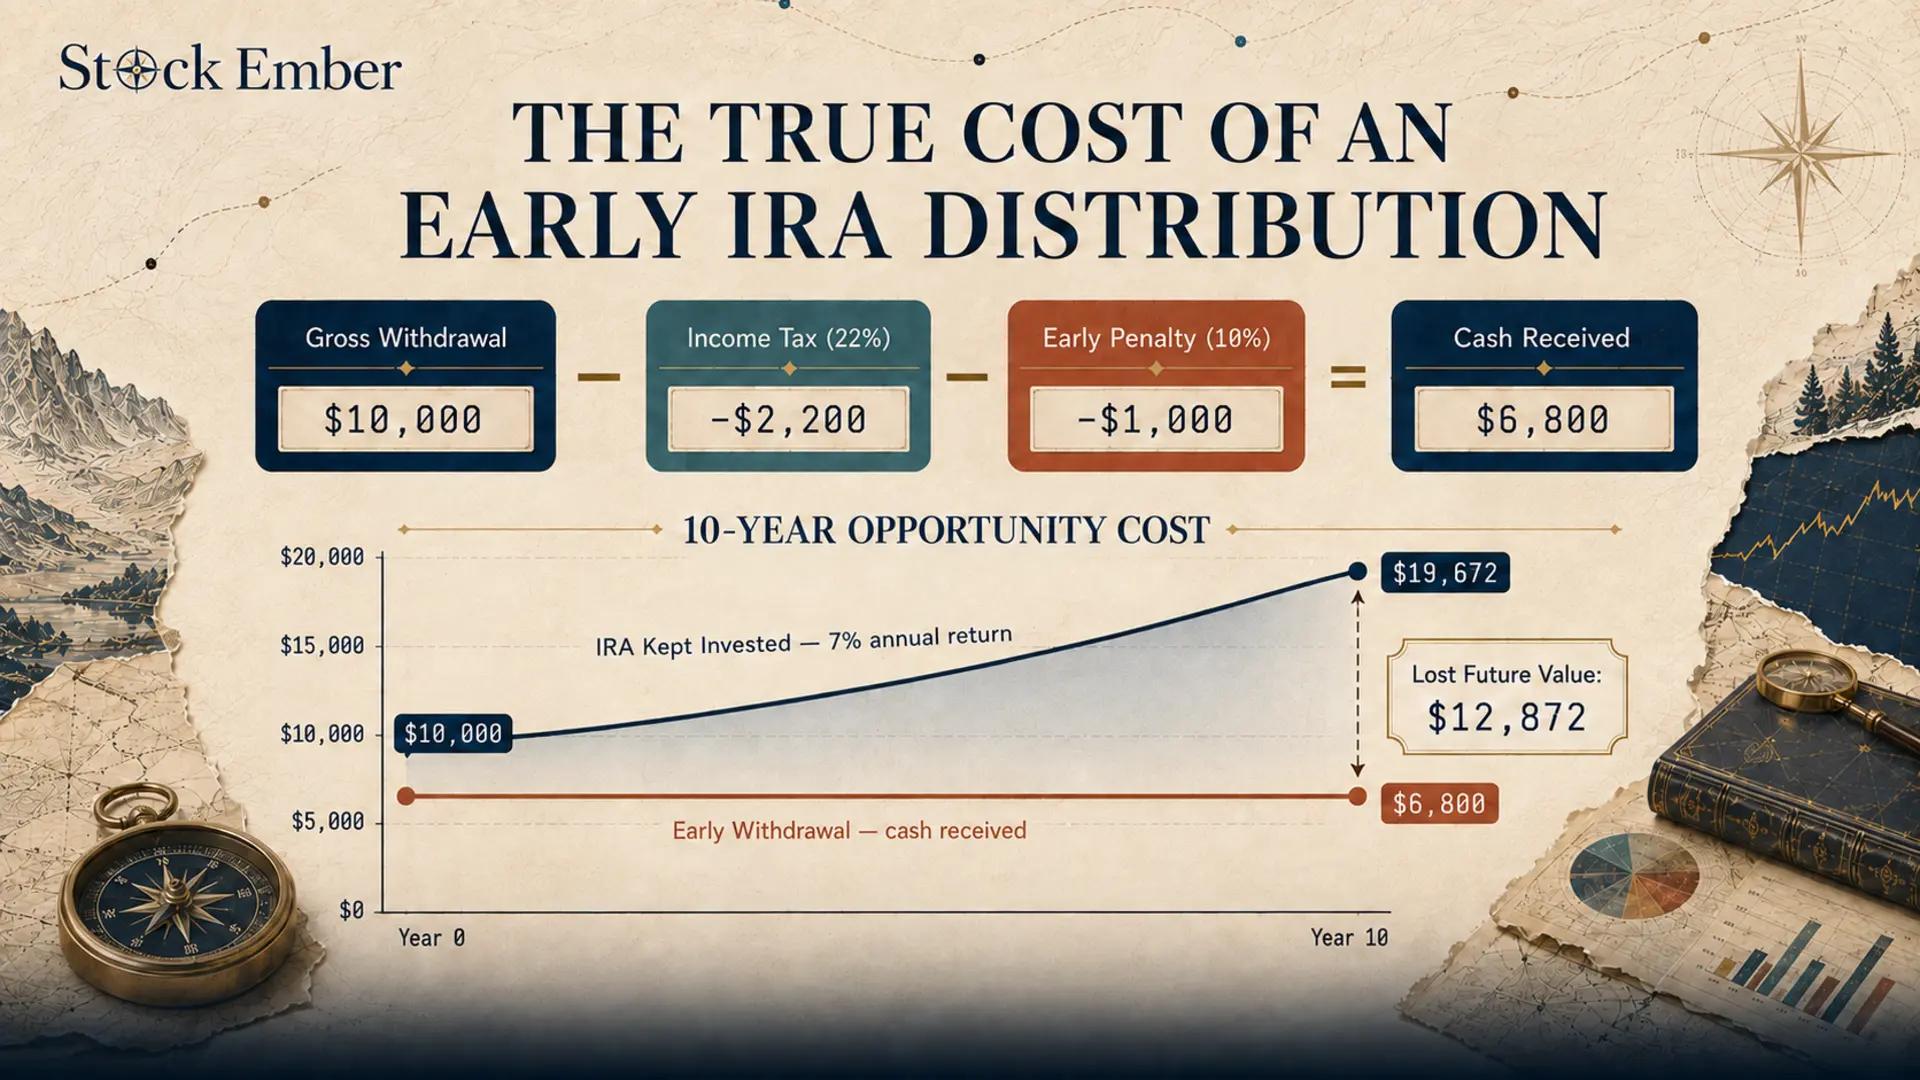
Focusing only on the immediate 10% penalty obscures the full financial impact of an early withdrawal. Premature payouts destroy the future compounding power of your capital.
Chart showing 10-year compounding losses from an early IRA withdrawal
The total immediate tax hit on an early pre-tax distribution follows a simple equation:
Net Distribution = Gross Withdrawal − (Ordinary Income Tax + 10% Penalty)
Consider an investor in the 22% federal income tax bracket who takes an early $10,000 distribution from a Traditional IRA:
Gross Withdrawal: $10,000
Ordinary Income Tax (22%): $2,200
Early Penalty (10%): $1,000
Immediate Cash Received: $6,800
Total Tax & Penalty Lost: $3,200
Now look at the 10-year opportunity cost. Had that $10,000 remained invested inside the tax-deferred account earning an average 7% annual compound return, it would have grown to approximately $19,672 over ten years.
By pulling out $10,000 early to get $6,800 in cash, the investor sacrificed $19,672 in future portfolio value. The true cost of that distribution was not just $3,200 in upfront taxes—it was $12,872 in lost compounding capital.
Note: This 7% figure is a hypothetical average return for illustration only — actual market returns are not guaranteed and can vary significantly.
Common IRA Withdrawal Mistakes to Avoid
Managing distributions requires careful administrative execution. Three frequent errors catch account holders off guard:
Missing RMD Deadlines: Forgetting to take an RMD by December 31st triggers a severe 25% penalty on the missing amount. Always set up automated distributions with your custodian to guarantee compliance.
Violating the 60-Day Rollover Limit: If you take an indirect distribution to perform a 401(k) to IRA rollover, you have exactly 60 days to deposit those funds into the target account. Missing this window turns the transfer into a taxable distribution subject to early penalties.
Triggering Unintended Tax Bracket Spikes: Taking a large, lump-sum Traditional IRA withdrawal in a single tax year can push your income into a higher federal tax bracket, significantly raising your marginal tax rate on every dollar withdrawn.
Ignoring these IRA withdrawal rules when planning a rollover is one of the most common mistakes investors make.
Conclusion
Understanding IRA withdrawal rules allows you to protect your wealth from avoidable tax penalties while maximizing tax-deferred growth. By honoring key age thresholds like 59½ and 73, using Roth ordering rules, and relying on IRS penalty exceptions only when necessary, you keep your investment capital working for you.
When you are ready to evaluate platforms for managing your retirement savings, exploring our broker reviews and rankings provides a solid starting point for selecting the right custodian.
Investing always involves risk, and tax regulations change over time. Treat this guide as educational information to inform your long-term planning, rather than personalized tax or legal advice.
FAQ
4 questions
When can I withdraw money from a Traditional IRA without a penalty?
You can take penalty-free withdrawals starting at age 59½. Any taxable portion withdrawn is added to your income for the year and taxed at your ordinary income tax rate.
What is the penalty for taking money out of an IRA early?
If you withdraw funds before age 59½, you generally face a 10% early withdrawal penalty from the IRS, in addition to paying standard income tax on the amount taken out.
Are there any penalty exceptions for early withdrawals?
Yes. The IRS waives the 10% early penalty for specific qualified reasons, including up to $10,000 for a first-time home purchase, qualified higher education expenses, certain large medical bills, or disability.
How do withdrawals from a Roth IRA differ from a Traditional IRA?
You can withdraw your original contributions to a Roth IRA at any time, tax-free and penalty-free. However, earnings can only be withdrawn tax-free if the account is at least 5 years old and you are age 59½ or older.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.