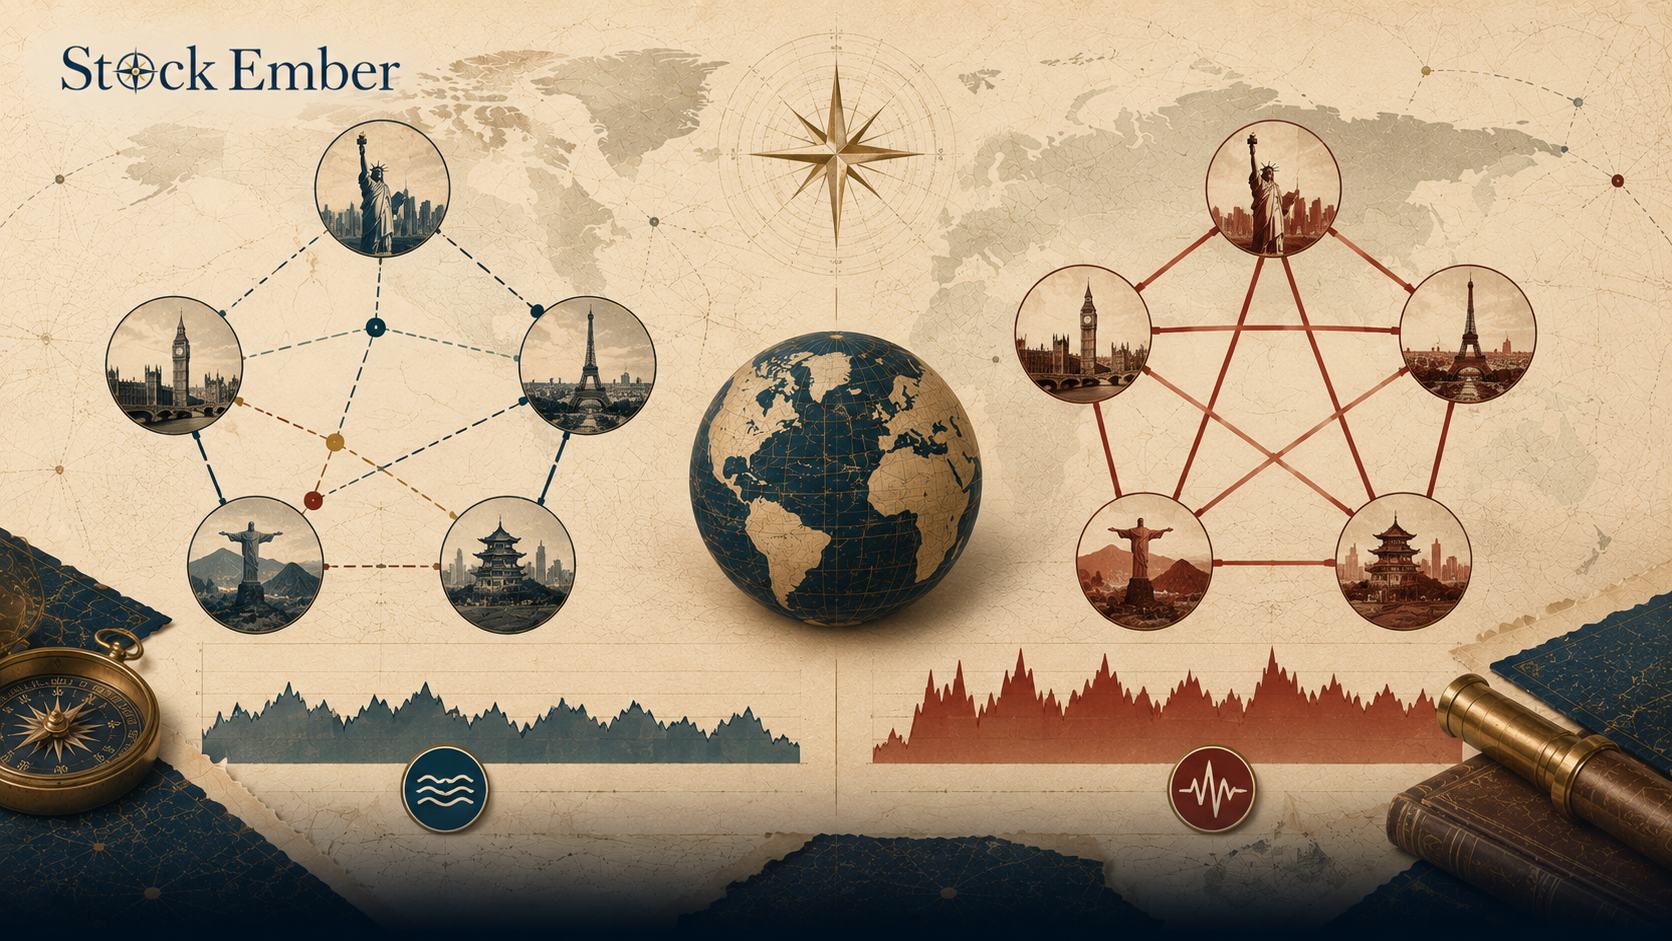
International diversification is the strategy of allocating portfolio assets across foreign stock and bond markets to reduce single-country economic concentration risk. By spreading investments across global economies, investors capture international growth while buffering their portfolios against localized recessions or domestic currency swings.
In portfolio management, international diversification is the strategy of spreading investments across foreign stock and bond markets to reduce single-country economic concentration risk and capture global growth opportunities.
Relying entirely on your home market leaves your portfolio vulnerable to local recessions, currency swings, or regulatory changes. Expanding your investment horizon globally helps protect your long-term wealth by spreading risk across different economies. This guide breaks down how international markets work, the impact of currency risk, and how hidden fees affect foreign returns.
Quick Takeaways
01International diversification spreads risk across global economies, reducing reliance on the financial performance of any single country.
02Holding foreign assets exposes your portfolio to currency fluctuations, which can either boost or reduce net returns depending on exchange rate shifts.
03Developed and emerging markets offer different risk profiles, with emerging economies providing higher growth potential alongside greater volatility.
04Global stock correlations tend to rise during major market panics, meaning foreign stocks do not eliminate short-term crash risk.
What Is International Diversification?
Understanding international diversification begins with recognizing the limits of domestic investing. Many investors suffer from home country bias, the natural tendency to invest mostly in companies from their own country because those brand names feel familiar.
However, domestic stocks represent only a portion of the total global equity market. Holding assets across multiple nations prevents your long-term financial health from depending entirely on one country's inflation rate, interest rate policies, or economic growth. If your home economy experiences a prolonged slowdown, growth in foreign markets can help offset domestic losses.
Investors split international assets into two main categories:
Developed Markets: Established economies with mature financial systems, stable legal structures, and high living standards (such as Japan, the United Kingdom, Germany, and France).
Emerging Markets: Developing economies experiencing rapid industrialization and expansion (such as India, Brazil, and Vietnam), which offer higher growth potential but carry higher political and economic risk.
How International Diversification Works in Practice
Building a globally diversified portfolio involves choosing how much weight to assign to international holdings versus domestic assets. Many global index benchmarks follow market-capitalization weighting, where a country's representation in a fund matches the total size of its stock market.
Moderate Volatility; Exposure to Foreign Currency Shifts
Emerging Markets
Emerging Asia, Latin America
High Growth Potential
Higher Volatility; Geopolitical & Liquidity Risks
When you hold international funds, your capital spreads across thousands of global corporations. This broad exposure ensures that an economic downturn or regulatory shift in one region does not pull down your entire nest egg.
Why Global Exposure Matters for Long-Term Buy-and-Hold Investors
Investing globally grants access to specialized industries and economic engines that may be rare in your domestic market. For example, specific technology manufacturers or commodity producers may operate almost entirely outside your home country.
For buy-and-hold investors, passive investing through broad total world stock ETFs offers an efficient way to capture global growth. Total world index funds automatically adjust their country weights as global markets expand or contract, keeping your portfolio balanced without requiring active market timing.
In practice, many long-term investors find that holding a single total world fund eliminates the temptation to constantly tweak geographic allocations based on short-term market headlines.
The Silent Drag: How Currency, Taxes, and Fees Impact Foreign Returns
While spreading assets globally reduces single-country risk, international holdings introduce unique structural costs that can quietly drag down multi-decade returns.
Consider the ten-year cost of holding $100,000 in foreign equity funds compared to a pure domestic index fund. International ETFs often carry slightly higher expense ratios due to the operational complexity of trading across foreign exchanges. If an international fund charges a 0.25% expense ratio compared to 0.03% for a domestic fund, that fee gap takes thousands of dollars out of your compounding balance over a ten-year holding period.
Additionally, international distributions face foreign dividend withholding taxes. Many foreign governments automatically deduct taxes from dividends before the cash reaches your account. Unless held in specific tax-advantaged setups or claimed through foreign tax credits, these unrecoverable tax withholdings create a steady annual drag on compounding wealth.
Major Pitfalls and Market Risks to Watch
Adding foreign equities to your portfolio introduces specific risks that every long-term investor must manage:
Currency Volatility: When you invest in foreign assets, your returns depend on both asset price movements and currency exchange rates. If a foreign stock rises 10% but that country's currency falls 10% against your home currency, your net return drops to roughly zero.
Rising Crisis Correlations: A common misconception is that foreign stocks will always rise when domestic stocks fall. During severe global financial panics, correlations between developed stock markets approach 1.0, meaning almost all equity markets drop together in the short term.
Geopolitical and Regulatory Shifts: Emerging market holdings face political instability, capital controls, or sudden regulatory changes that can affect asset valuations overnight.
Advanced portfolio frameworks, such as factor investing, attempt to navigate these international risks by selecting foreign stocks based on specific attributes like value, momentum, or quality rather than market weight alone.
The U.S. Securities and Exchange Commission notes that international assets expose investors to unique currency and regulatory risks that differ from domestic holdings.
Chart showing stock market correlation levels during global financial market crashes.
Conclusion
Applying international diversification provides a strong structural defense against single-country concentration risk. By spreading your assets across developed and emerging economies, you protect your long-term wealth from localized recessions while tapping into global corporate growth. However, successful global investing requires realistic expectations: holding foreign assets introduces currency friction, slightly higher fund fees, and tax complexities that must be managed alongside market volatility.
When you are ready to evaluate low-cost global funds to build a diversified portfolio, our ETF reviews provide a practical place to start.
Investing always involves risk of capital loss, and international holdings do not guarantee higher returns or total protection against market downturns. Treat global allocation principles as educational tools to guide your long-term planning.
FAQ
5 questions
What is international diversification in investing?
International diversification involves spreading portfolio investments across multiple countries and regions rather than concentrating capital in a single domestic market. This approach limits exposure to localized economic downturns, currency devaluation, and country-specific policy shifts.
Why is international diversification important for a long-term portfolio?
Non-domestic stock markets represent over 40% of total world market capitalization. Investing globally allows buy-and-hold investors to access specialized foreign industries, capture global GDP growth, and prevent their wealth from depending entirely on one country's economy.
What percentage of a portfolio should be allocated to international stocks?
Global stock benchmarks often use market-capitalization weighting, placing roughly 60% in domestic equities and 40% in international markets. However, individual allocations vary based on personal risk tolerance, time horizon, and home country economic factors.
What are the main risks of international stock diversification?
Key risks include currency volatility, foreign dividend withholding taxes, higher fund expense ratios, and geopolitical instability in emerging markets. Additionally, foreign exchange rate shifts can alter your net returns when converted back to domestic currency.
Does international diversification protect against a global market crash?
No. During acute global financial panics, correlations between developed stock markets tend to rise significantly, causing global markets to decline together. International diversification helps manage long-term single-country economic risk rather than short-term crash volatility.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.