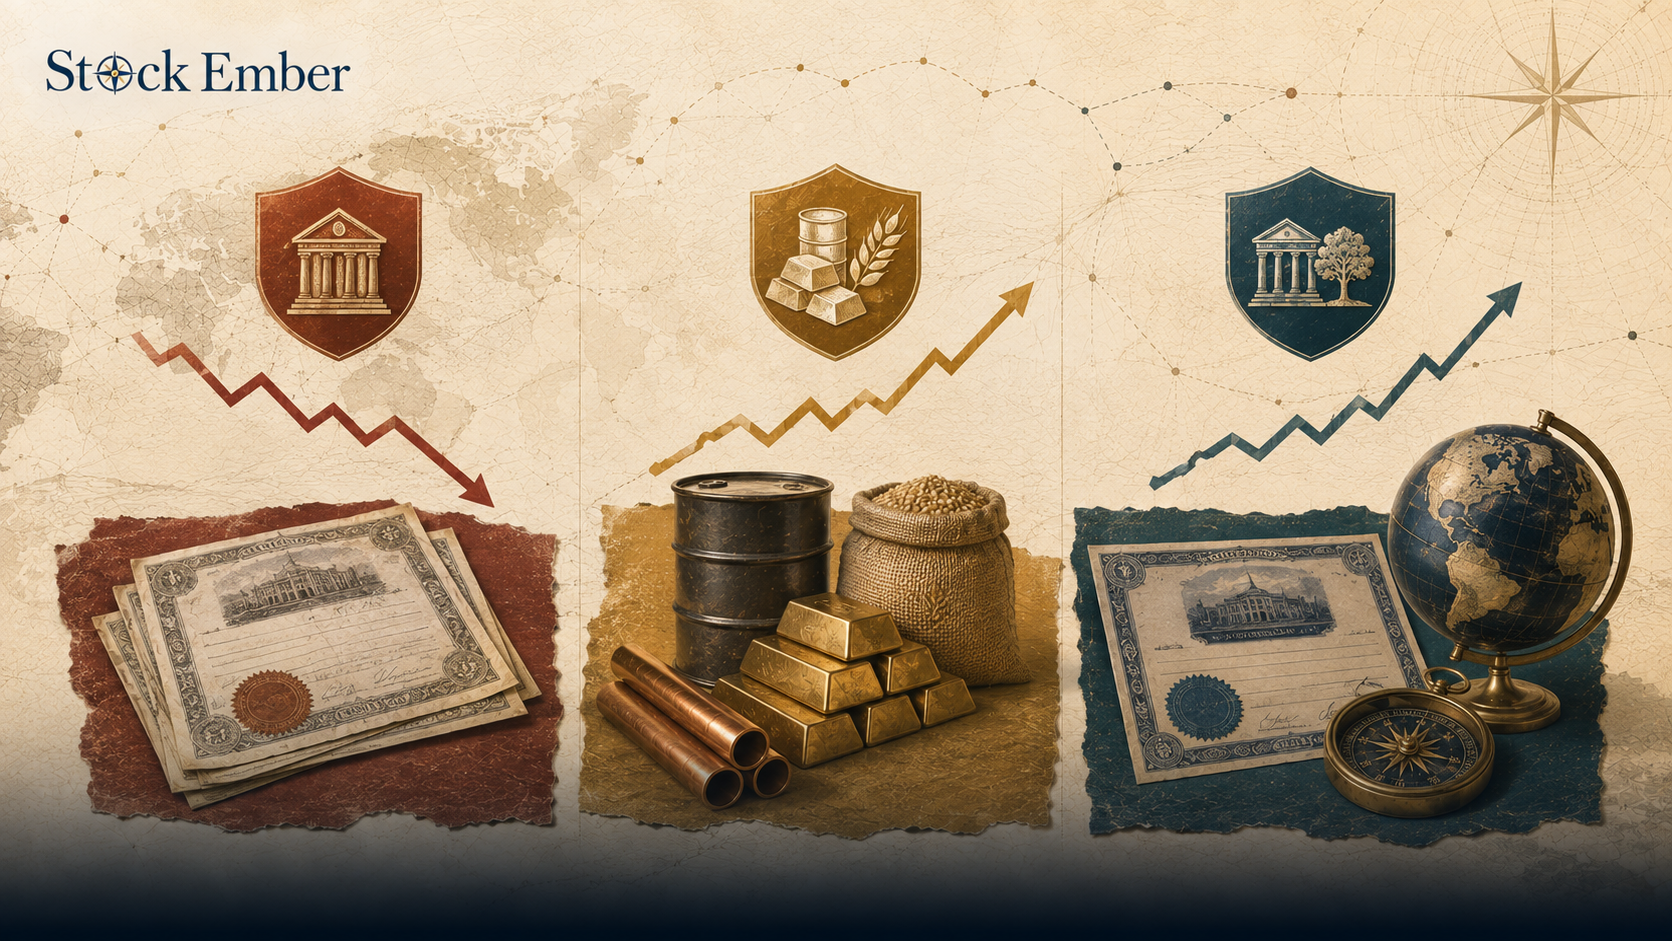
Investing during stagflation requires focusing on real assets, inflation-linked bonds, and defensive equities with pricing power while avoiding aggressive market timing. Maintaining a low-cost, broadly diversified portfolio protects purchasing power without suffering from high trading fee drag.
Stagflation is an economic environment marked by stagnant economic growth, elevated unemployment, and persistently high inflation. It creates a difficult backdrop for traditional equity and fixed-income assets.
When living costs rise while the economy stalls, investors often wonder how to protect their purchasing power without taking on unsafe risks. Trying to time economic cycles usually backfires through high costs and poor execution. This guide explains how stagflation affects different investments and how a disciplined long-horizon strategy helps keep your portfolio on track.
Quick Takeaways
01Stagflation combines weak economic growth with high consumer price inflation, pressuring both stocks and traditional nominal bonds.
02Inflation-protected securities and high-quality companies with pricing power offer relative resilience during persistent price increases.
03Rapidly swapping portfolio assets during economic scares creates heavy fee and tax drag that erodes long-term wealth.
04Maintaining a low-cost, diversified portfolio remains the most reliable way to preserve real purchasing power over a 10-year horizon.
What Is Stagflation and Why Does It Challenge Portfolios?
Stagflation occurs when an economy faces slow growth, rising unemployment, and high inflation simultaneously. Most economic periods feature either high inflation during strong growth or low inflation during a slowdown. When both problems strike at once, standard market playbook strategies struggle.
For stock investors, slowing consumer demand reduces company sales while rising input prices squeeze profit margins. Corporate earnings fall, and investors often pay lower multiples for those earnings, dragging down equity valuations.
For bondholders, elevated inflation erodes the purchasing power of fixed interest payouts. To offset rising prices, central banks usually raise interest rates, which causes existing nominal bond prices to decline.
Because stocks and bonds can fall at the same time during stagflationary shocks, traditional balanced portfolios experience higher volatility. Understanding these mechanics helps investors avoid emotional decision-making when markets experience broad pressure across standard asset classes.
How Stagflation Impacts Different Asset Classes
Not all investments react to inflation and low growth in the same way. Looking at asset behavior helps explain where defensive strength usually lies.
Inflation-Linked Debt and Short Duration Standard nominal bonds struggle when inflation rises because their fixed coupon payments buy less over time. In contrast, Treasury Inflation-Protected Securities adjust their principal value based on official consumer price metrics, as outlined by the US Treasury. Short-duration bonds also suffer less price damage than long-term debt because their principal turns over quickly into higher current yields.
Real Estate and Mortgage REITs Physical real estate can adjust rents upward over time, offering some resilience against inflation. Specialized income vehicles like mortgage Real Estate Investment Trusts (REITs), however, often struggle during stagflation because rising interest rates squeeze their borrowing costs and net interest margins.
Equities with Strong Pricing Power Companies in essential sectors like healthcare, utilities, and consumer staples tend to hold up better than speculative growth businesses. Firms with dominant market positions can pass rising input costs directly to consumers without losing sales volume. In contrast, businesses with heavy debt burdens or distant profit expectations face severe valuation contraction when borrowing costs rise.
Diagram illustrating relative performance factors across asset classes during high inflation and slow growth.
The 10-Year Cost of Tactical Churning During Stagflation
When news headlines warn of economic stagnation, many investors feel compelled to make sudden allocation changes. Shifting rapidly between cash, gold, energy stocks, and short-term debt is known as tactical churning.
While moving in and out of hot sectors feels proactive, it introduces hidden portfolio friction. Every trade incurs potential transaction fees, bid-ask spreads, and taxable capital gains events.
Consider an investor with a $100,000 portfolio who panics during an economic slowdown. Suppose frequent trading and switching into active niche funds creates an additional 1% annual drag from fees and transaction friction. Over a 10-year holding period, this additional 1% annual drag would reduce the final portfolio value by roughly $17,600 in this hypothetical scenario only, real-world results will vary, assuming an illustrative 7% nominal annual return before these additional costs.
In practice, many long-term investors find that the capital gains taxes triggered by reactive selling hurt total compound growth far more than the temporary economic cycle itself.
Practical Portfolio Strategies for Long-Term Investors
Building resilience against stagflation does not require guessing the exact month an economic cycle will end. Knowing how to invest during stagflation starts with understanding which asset classes hold up when growth stalls and prices keep climbing. Instead, focus on structural habits that protect capital through all economic regimes.
Core strategy relies on low-cost passive investing using broad market index funds. Broad index funds allow you to own established global companies across multiple sectors at minimal operating expense.
A disciplined approach includes three simple practices:
Maintain broad asset diversification: Spread investments across global equities, inflation-protected bonds, and cash reserves to avoid single-sector exposure.
Rebalance on a fixed schedule: Adjust asset weights back to target allocations once or twice a year rather than reacting to daily headlines.
Dollar-cost average consistently: Continue purchasing index shares at fixed intervals so you automatically buy more shares when market valuations fall.
These habits ensure your portfolio stays aligned with long-term goals while keeping investment expenses low.
Common Mistakes to Avoid
Investors often make predictable errors when facing combined inflation and weak growth. Avoiding these common traps helps preserve capital for future expansion:
Fleeing entirely into cash: Moving a portfolio completely into bank deposits protects nominal dollars but guarantees real purchasing power loss when inflation stays elevated.
Chasing past commodity spikes: Buying commodities after a major price run-on often leads to buying at cyclical tops right before demand cools.
Taking high credit risks for yield: Reaching for risky junk bonds to beat inflation exposes your principal to default risk during economic contractions.
Abandoning target asset allocations: Pausing long-term investment plans during economic uncertainty locks in paper losses and misses eventual market recoveries.
Conclusion
Stagflation presents a unique challenge, but it remains a temporary phase in the broader economic cycle. By avoiding market timing, minimizing trading costs, and holding resilient asset classes, long-term investors can handle uncertain periods without disrupting their compound growth goals. Focus on low-cost index funds, maintain a steady rebalancing schedule, and keep your long-horizon strategy intact.
When you are ready to evaluate broad-market funds for your portfolio, our ETF reviews offer clear breakdowns of low-cost options. Investing always involves risk of loss, so treat these historical patterns as educational context for your own research.
FAQ
5 questions
What is the best asset class during stagflation?
Historically, real assets like physical commodities and Treasury Inflation-Protected Securities (TIPS) have held up better than traditional nominal bonds. Defensive equities with strong pricing power also show relative resilience, though no single asset class guarantees profit during economic shifts.
Do stocks perform well during stagflation?
Stocks generally face headwinds during stagflation because slowing demand reduces sales while inflation squeezes profit margins. However, defensive sectors like utilities, healthcare, and consumer staples with strong pricing power tend to perform better than high-valuation growth equities.
Is gold a reliable hedge against stagflation?
Gold has historically served as a store of value during inflationary cycles, but its price can be volatile over shorter horizons. Rather than relying heavily on a single commodity, long-term investors benefit more from broad asset class diversification.
How does stagflation affect real estate and mortgage REITs?
Physical real estate can adjust rents upward over time, offering some inflation resilience. However, specialized income vehicles like mortgage REITs can struggle during stagflation because rising interest rates squeeze their borrowing costs and net interest margins.
How should passive investors handle stagflation without market timing?
Passive investors should maintain their target asset allocations, rebalance on a fixed schedule, and dollar-cost average into low-cost index funds. Avoiding rapid portfolio churning prevents fee and tax drag that erodes long-term returns.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.