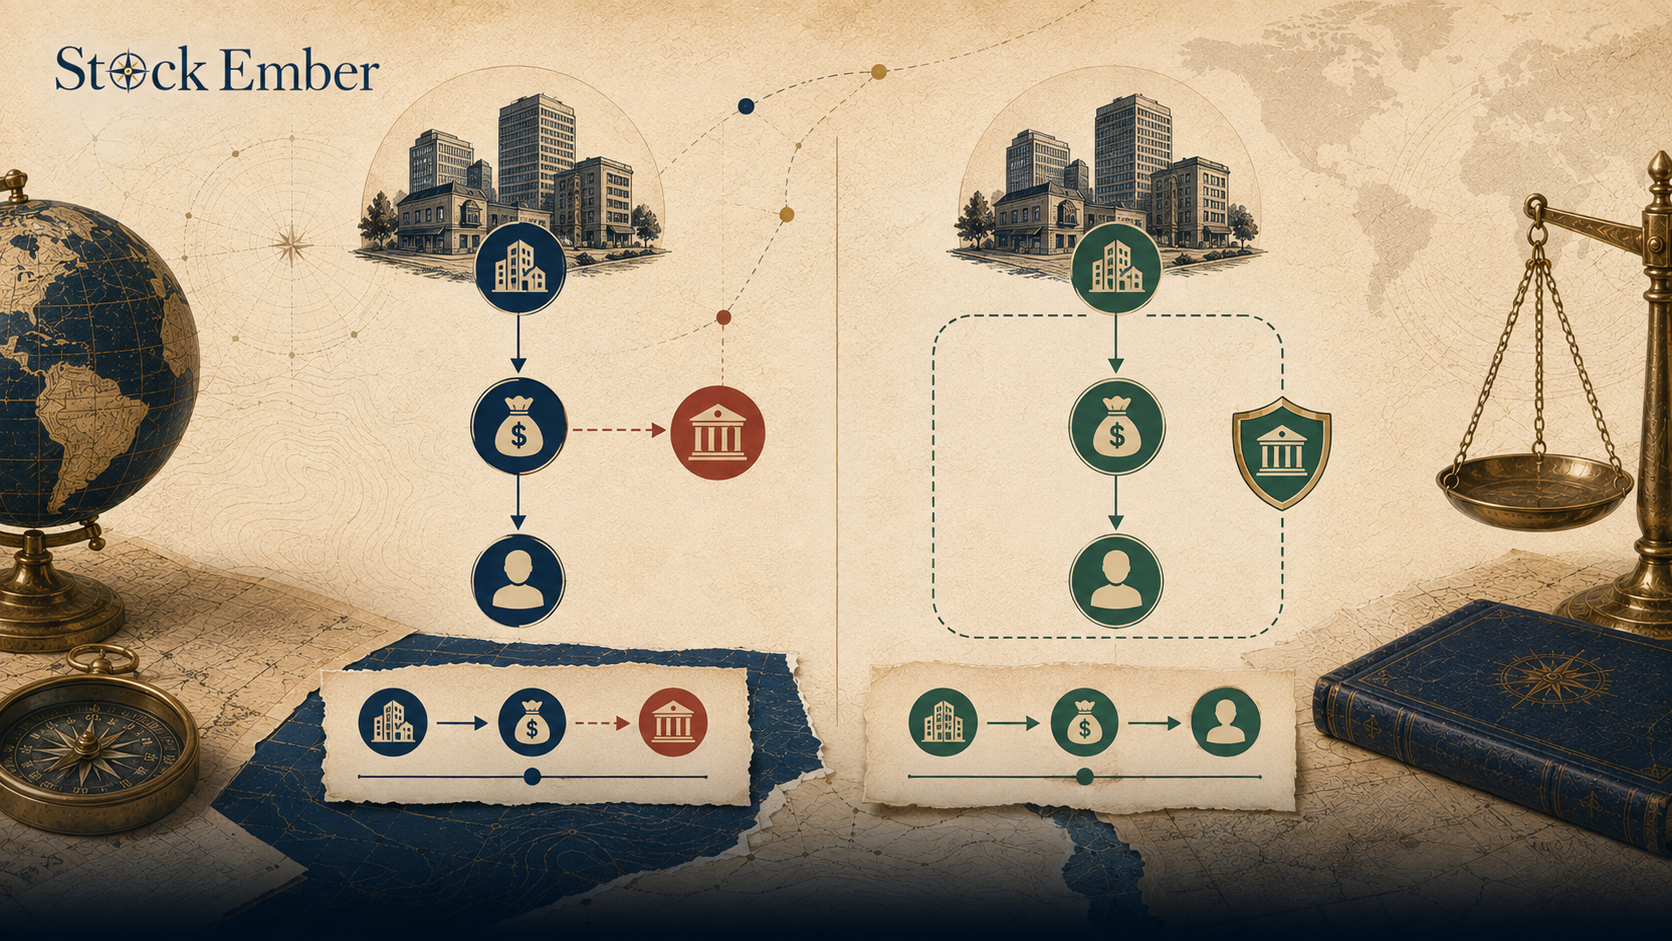
At the shareholder level, Real Estate Investment Trusts (REITs) are generally taxed at ordinary income tax rates rather than lower qualified dividend rates. However, because REITs pass through at least 90% of taxable income without corporate tax, eligible investors can deduct up to 20% of qualified ordinary dividends under Section 199A.
At the shareholder level, how are REITs taxed depends on payout type: most distributions are taxed as ordinary income rather than qualified dividends, though up to 20% may qualify for the Section 199A deduction.
A high dividend yield from a real estate investment trust can look very attractive to income-focused investors. However, receiving a 6% or 7% annual payout often comes with a surprise tax bill if you hold those shares in a standard taxable account. This guide breaks down corporate pass-through rules, Form 1099-DIV tax boxes, the Section 199A deduction, and smart account location strategies.
Quick Takeaways
01Most REIT dividends do not qualify for lower capital gains tax rates and are taxed at your full federal income tax bracket.
02REIT payouts reported on Form 1099-DIV are split across ordinary dividends, capital gains, and non-taxable return of capital.
03Under Section 199A, eligible individual investors can deduct up to 20% of qualified REIT ordinary dividends from their taxable income.
04Holding high-yield REIT shares in tax-advantaged accounts like IRAs protects your compounding wealth from annual tax drag.
Corporate vs. Shareholder Tax Status
To understand how real estate investment trusts are taxed, you must look at their corporate structure. Unlike standard C-corporations, a Real Estate Investment Trust (REIT) is a pass-through entity under United States tax laws.
The U.S. Securities and Exchange Commission notes that real estate investment trusts pass at least 90% of their taxable income directly to shareholders each year. In exchange for making these large distributions, the REIT pays zero corporate income tax at the company level. This pass-through structure avoids the double taxation that applies to traditional corporate earnings.
However, because the business pays no tax at the corporate level, the tax burden shifts entirely to you, the individual shareholder. Because the company did not pay corporate taxes on that profit, the IRS generally does not grant REIT payouts the lower "qualified dividend" tax rate.
How REIT Distributions Are Classified (Form 1099-DIV)
When tax season arrives, your brokerage sends you IRS Form 1099-DIV. Rather than listing your entire payout under one simple dividend rate, REIT distributions are divided into three distinct tax categories.
Form 1099-DIV Box
Distribution Type
Federal Tax Treatment
Impact on Investor Portfolio
Box 1a
Ordinary Dividends
Taxed at standard federal income tax rates
Treated as regular earnings; subject to the highest tax bracket.
Box 2a
Capital Gain Distributions
Taxed at preferential long-term capital gains rates
Applies when the REIT sells a property for a profit.
Box 3
Nontaxable Distributions (Return of Capital)
Tax-deferred; not taxed in the current year
Reduces your cost basis in the stock, delaying capital gains tax until sale.
Nontaxable return of capital (Box 3) occurs when property accounting rules, like depreciation, offset real cash flows. If you buy a share for $50 and receive a $2 return of capital distribution, you pay no tax today. However, your cost basis drops to $48. When you eventually sell the share for $60, your taxable profit increases from $10 to $12.
The Section 199A QBI Deduction Explained
While ordinary REIT dividends face regular income tax brackets, individual investors receive an important tax break created by the Tax Cuts and Jobs Act.
Understanding how are REITs taxed under Section 199A is the first step toward claiming the full 20% deduction. This deduction is reported in Box 5 of Form 1099-DIV.
For example, if you sit in the 24% federal tax bracket, the 20% Section 199A deduction reduces the taxable portion of your REIT dividend to 80%. That brings your effective federal tax rate on that dividend down from 24% to 19.2%. You do not need to itemize deductions on your tax return to claim this benefit.
The Silent Drag: How REIT Taxes Impact Taxable Brokerage Accounts
Receiving high cash payouts in a standard taxable brokerage account creates an annual tax drag that quietly slows your multi-decade wealth building.
Consider the ten-year cost of holding $100,000 in a high-yielding REIT inside a taxable account versus a tax-sheltered account. Suppose the holding yields 6% annually in ordinary dividends, generating $6,000 in Year 1 income.
In a 24% tax bracket (with an effective 19.2% rate after the 199A deduction), you owe roughly $1,152 in federal income taxes in Year 1 alone. Over a ten-year holding period, paying taxes on those annual distributions takes tens of thousands of dollars out of your account. That lost tax capital can no longer compound, significantly reducing your long-term account growth compared to an account where payouts accumulate tax-free.
In practice, many long-term investors find that reviewing annual Form 1099-DIV statements helps them organize their assets by placing high-yield income holdings inside tax-advantaged accounts.
Strategic Asset Location: Where to Hold REITs
Because of ordinary income tax treatment, asset location is key to maximizing your net returns. Knowing how REITs are taxed helps you decide whether they belong in a taxable account or a retirement account.
Tax-Advantaged Accounts (Traditional IRA, Roth IRA, 401k): These accounts are ideal for holding real estate trusts. Inside a Roth IRA, your distributions grow and can be withdrawn completely tax-free in retirement. In a Traditional IRA, taxes are delayed until you draw income.
Taxable Brokerage Accounts: Better suited for broad-market passive investing strategies through total market index funds. Broad index funds generate mostly qualified dividends and low turnover, minimizing annual tax friction.
Diagram illustrating tax drag on REIT dividends across taxable and tax-advantaged accounts.
Asset location choices also matter during unusual macro environments. For instance, during periods of economic slowdown and rising costs, such as stagflation, physical real estate assets often adjust rents upward to track rising prices. Holding income-generating real estate assets within a tax-sheltered IRA helps you preserve real purchasing power without losing dividend growth to immediate tax liabilities.
Conclusion
Understanding how REITs are taxed ensures that a high distribution yield translates into real wealth growth rather than an unexpected tax burden. While REITs avoid corporate income tax by passing 90% of earnings to shareholders, those payouts are generally taxed as ordinary income at your personal tax bracket. Taking advantage of the 20% Section 199A deduction and placing high-yield holdings inside tax-advantaged retirement accounts helps protect your compounding momentum over time.
When you are ready to evaluate low-cost real estate funds and broad index funds to balance your long-term portfolio, our ETF reviews provide a practical place to start.
Investing always involves risk of loss, and tax laws vary by personal situation and subject to statutory changes. Treat baseline tax guidelines as educational information to guide your planning rather than individual tax advice.
FAQ
5 questions
Are REIT dividends taxed as qualified dividends?
No, REIT dividends are generally not qualified dividends. Because REITs avoid corporate income taxes at the company level by distributing 90% of earnings, payouts are taxed as ordinary income at your individual federal income tax bracket.
What is the 20% Section 199A deduction for REIT dividends?
Under IRS Section 199A, eligible individual investors holding REITs can deduct up to 20% of their qualified REIT ordinary dividends from taxable income. This lowers the effective tax rate on those distributions in taxable accounts.
How does Return of Capital (ROC) affect your taxes?
A return of capital distribution is non-taxable in the year you receive it. Instead, it reduces your cost basis in the REIT shares, deferring tax liabilities until you sell the holding, which then increases your taxable capital gain.
Which IRS tax form reports REIT distributions?
REIT payouts are reported on IRS Form 1099-DIV. Your distributions will be categorized across Box 1a (ordinary dividends), Box 2a (capital gain distributions), Box 3 (nontaxable return of capital), and Box 5 (Section 199A QBI).
Should you hold REITs in a taxable account or an IRA?
Because REIT distributions are subject to ordinary income tax rates, holding them inside tax-advantaged accounts like a Traditional or Roth IRA protects payouts from annual tax drag, allowing dividend income to compound faster.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.