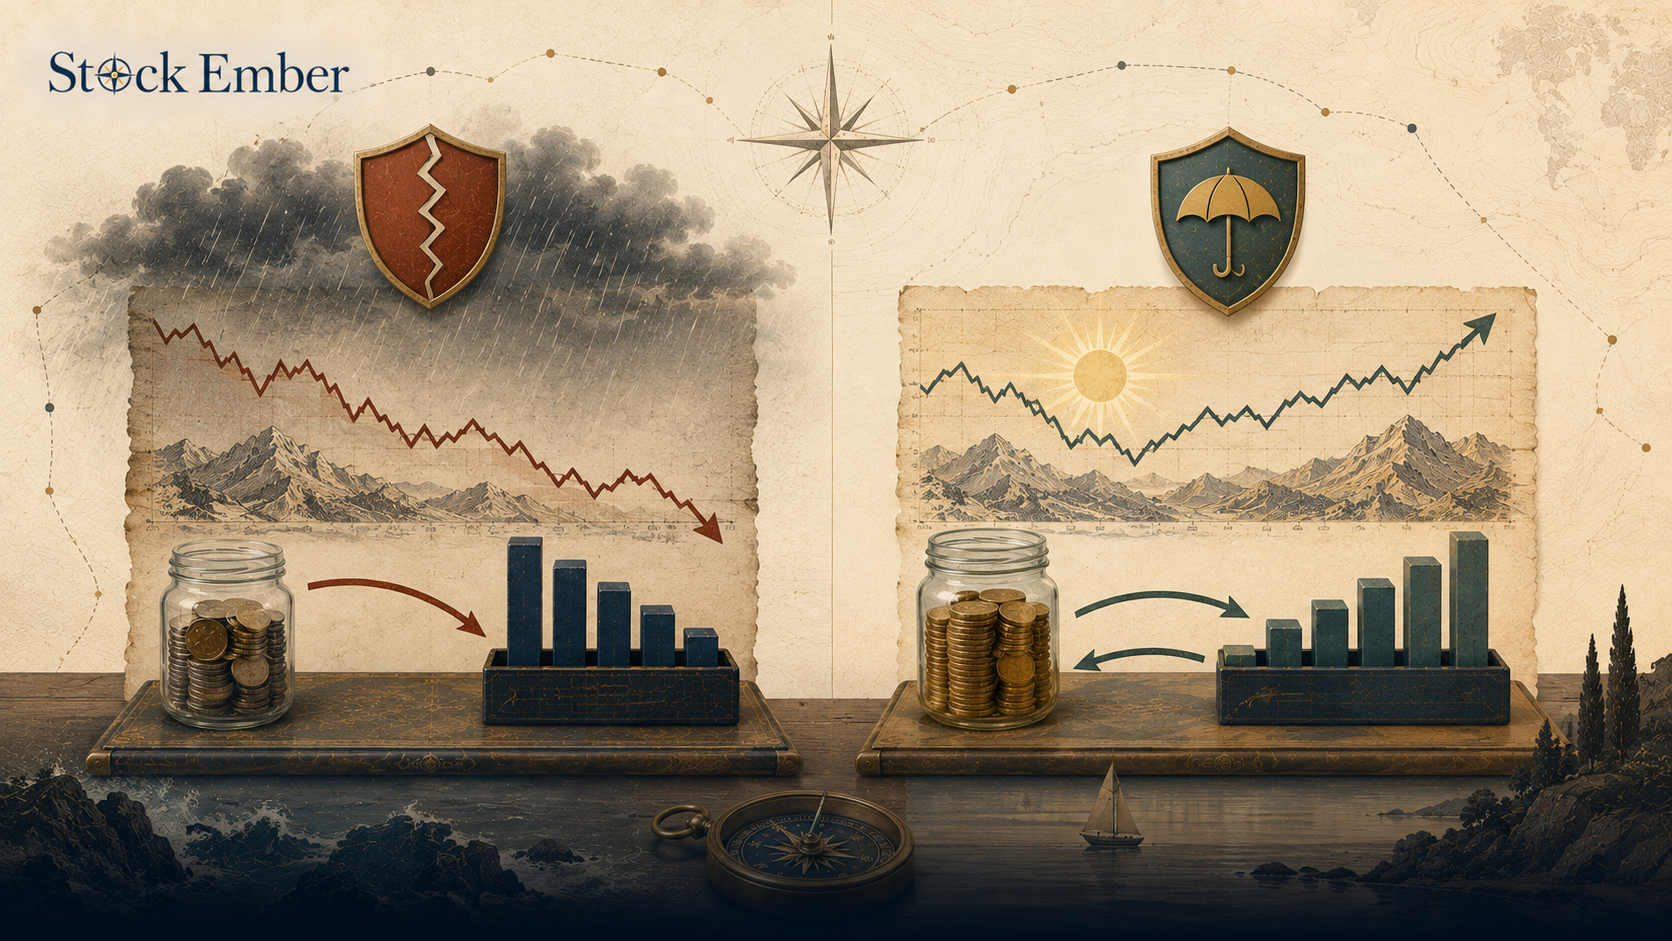
The FIRE movement retirement strategy relies on saving 50% or more of net income to accumulate a portfolio equal to 25 times annual living expenses. Over multi-decade retirement windows lasting 40 to 50 years, investors use conservative withdrawal rates alongside broad-market index funds to preserve real purchasing power.
The FIRE movement retirement strategy is a personal finance framework designed to achieve financial independence and enable early retirement by combining high savings rates with long-term index investing and disciplined withdrawal rules.
For many working professionals, the traditional retirement age feels decades too far away. Building a portfolio that can support 40 or 50 years of living expenses requires a clear understanding of accumulation math, asset location, and withdrawal mechanics. This guide breaks down how the FIRE strategy works, how to calculate your baseline targets, and how to protect your portfolio over a multi-decade horizon.
Quick Takeaways
01The FIRE movement relies on saving 50% or more of net income to build a portfolio equal to roughly 25 times annual living expenses.
02Early retirement windows lasting 40 to 50 years often require withdrawal rates below the traditional 4% benchmark to withstand inflation and market downturns.
03Sequence-of-returns risk early in retirement can permanently damage portfolio durability if cash buffers and liquid assets are absent.
04Using low-cost index funds within a passive investing framework protects compound growth from management fees and excessive trading drag.
What Is the FIRE Movement and How Does Math Work?
The FIRE movement, which stands for Financial Independence, Retire Early, is an accumulation framework centered on maximizing the gap between income and lifestyle expenses. Instead of saving the traditional 10% to 15% of gross earnings over a 40-year career, FIRE practitioners aim to save 50% or more of their net income.
Saving a high percentage of income works through a dual mechanism: it accelerates portfolio contributions while simultaneously lowering annual living expenses. A higher savings rate shortens the total years needed to reach financial independence because living on less capital requires a smaller total nest egg.
The central benchmark in early retirement planning is the "FIRE number," calculated using the 25x rule:
FIRE Target = Annual Living Expenses * 25
For example, an individual who expects to spend $40,000 annually in retirement targets a total portfolio of $1,000,000. This target corresponds to a 4% initial withdrawal rate from a $1,000,000 portfolio.
The 4% Withdrawal Benchmark and Longevity Risks
The 4% withdrawal benchmark traces back to William Bengen's 1994 research on historical withdrawal rates and was later supported by the 1998 Trinity Study. The rule states that a retiree can withdraw 4% of their initial portfolio value in year one, adjusted annually for inflation, with a low historical probability of running out of money.
However, the original 4% benchmark was designed for a standard 30-year retirement horizon starting at age 65. Early retirees who step away from full-time work in their 30s or 40s face a retirement window that can span 40 to 50 years or longer.
Over extended timeframes, static 4% withdrawals carry higher failure risks due to longevity risk and long-term inflation erosion. Official guidance from economic authorities like the Federal Reserve Board shows that inflation fluctuating over long horizons erodes real purchasing power. Consequently, many early retirees adopt conservative withdrawal baselines between 3.0% and 3.5%, or use flexible spending rules that adjust downward during severe market downturns.
Portfolio Friction: Sequence of Returns, Taxes, and Market Liquidity
Sequence-of-returns risk refers to the risk that a major stock market decline occurs during the first few years of early retirement. When an investor draws income from a shrinking portfolio, they sell assets at depressed valuations, permanently reducing the underlying share count and impairing future capital recovery.
To protect against early market drawdowns, investors maintain an emergency buffer in cash or short-term paper. Having sufficient market liquidity in reserve allows retirees to fund living expenses during market slumps without liquidating equity positions at temporary bottoms.
Taxes and account structures also create portfolio friction. Early retirees must plan around access rules for tax-sheltered accounts like 401(k)s and IRAs, where withdrawals before age 59 1⁄2 may be subject to a 10% additional tax unless an IRS exception applies. Holding a mix of taxable brokerage accounts and retirement accounts ensures accessible cash flow across every age phase.
Diagram illustrating sequence-of-returns risk and cash buffer protection in early retirement portfolios.
Practical Portfolio Strategies for Sustaining FIRE
Sustaining an early retirement portfolio over multiple decades requires keeping investment expenses as low as possible. Relying on broad-market index funds through passive investing ensures your capital tracks total market growth without losing returns to active fund management fees.
Managing a long-term early retirement portfolio involves three simple operational habits:
Maintain target asset allocation: Balance global equities for growth with fixed-income assets and cash for volatility protection.
Rebalance periodically: Rebalance holdings annually to sell top-performing asset classes and buy underperforming ones back to target weights.
Keep a cash buffer: Reserve 1 to 2 years of living expenses in high-yield cash accounts to avoid selling equities during market contractions.
In practice, many long-term investors find that maintaining spending flexibility, reducing discretionary travel or major purchases during market dips, protects portfolio longevity far more effectively than trying to time market tops.
Variations of FIRE: Lean, Fat, and Barista Models
The early retirement community has developed several variations to suit different personal values, income levels, and risk tolerances:
LeanFIRE: Focuses on minimalist living and keeping annual expenses low, often under $40,000 per year. This approach requires a smaller total portfolio target but offers less spending flexibility during unexpected cost increases.
FatFIRE: Tailored for individuals who want a higher standard of living in retirement, with annual budgets exceeding $100,000. Achieving FatFIRE requires a significantly larger capital base and higher career earnings during the accumulation phase.
BaristaFIRE and CoastFIRE: Intermediate models where individuals leave high-stress corporate careers but maintain part-time work or flexible side jobs to cover current living expenses while letting existing investment accounts compound quietly in the background.
Common FIRE Retirement Pitfalls to Avoid
Achieving early retirement requires avoiding several common traps that can jeopardize long-term financial security:
Assuming static 4% withdrawals work forever: Relying blindly on a fixed 4% withdrawal rate over a 50-year horizon without adjusting for inflation or market crashes.
Underestimating healthcare costs: Failing to budget for private health insurance premiums and out-of-pocket medical expenses before qualifying for government programs.
Ignoring tax drag in taxable accounts: Placing high-turnover or dividend-heavy funds in taxable accounts without considering annual income tax liabilities.
Overestimating investment returns: Building accumulation models around overly optimistic stock market return assumptions while ignoring potential multi-year stagnant market cycles.
Conclusion
The FIRE movement retirement model offers a structured roadmap for achieving financial freedom through high savings rates, low-cost index compounding, and thoughtful withdrawal planning. By focusing on asset location, maintaining liquid cash reserves, and adopting flexible withdrawal habits, investors can build a resilient portfolio capable of lasting through extended retirement horizons.
When you are ready to explore low-cost index funds for your financial independence strategy, our ETF reviews provide detailed analysis of broad-market options. Investing always carries risk of loss and past performance does not guarantee future results, so treat this educational guide as a framework for your own long-term planning.
FAQ
5 questions
What is the FIRE movement retirement strategy?
The FIRE (Financial Independence, Retire Early) movement is a personal finance framework that combines high savings rates with low-cost index investing to achieve financial freedom ahead of traditional retirement age. By saving 50% or more of net income, practitioners build a portfolio designed to cover living expenses over an extended retirement horizon.
How do you calculate your FIRE retirement target?
You calculate your FIRE retirement target using the 25x rule, which multiplies your expected annual living expenses by 25. For example, if you require $40,000 per year to cover expenses, your target portfolio is $1,000,000. This benchmark is based on the traditional 4% initial safe withdrawal rate model.
Is the 4% withdrawal rule safe for a 40-year early retirement?
The 4% rule was originally modeled on a 30-year retirement window. For early retirees facing 40 to 50 years in retirement, a static 4% withdrawal rate carries higher failure risks due to longevity and inflation. Many early retirees use conservative rates between 3.0% and 3.5% or flexible spending rules.
What are the main types of FIRE strategies?
The primary FIRE variations include LeanFIRE (minimalist spending under $40,000 annually), FatFIRE (higher-budget retirement exceeding $100,000 annually), and BaristaFIRE or CoastFIRE (working part-time or allowing existing investments to compound while covering current costs with active income).
How do you protect an early retirement portfolio from sequence-of-returns risk?
You protect an early retirement portfolio from sequence-of-returns risk by maintaining an emergency cash buffer equal to 1 to 2 years of living expenses. Having liquid reserves prevents you from being forced to sell stocks at depressed valuations during major market downturns early in retirement.
Disclaimer
This guide was written with AI assistance and reviewed by the StockEmber editorial team for accuracy. StockEmber provides independent education, not personal financial advice. Some links may support our work at no additional cost to you.
The StockEmber Team is our in-house desk of independent research writers. We test brokerage platforms, read the fine print on fees and custody, and cover ETFs and long-horizon investing for people who plan to hold for decades — not days.